Setting Up a Loan Calculator in Excel
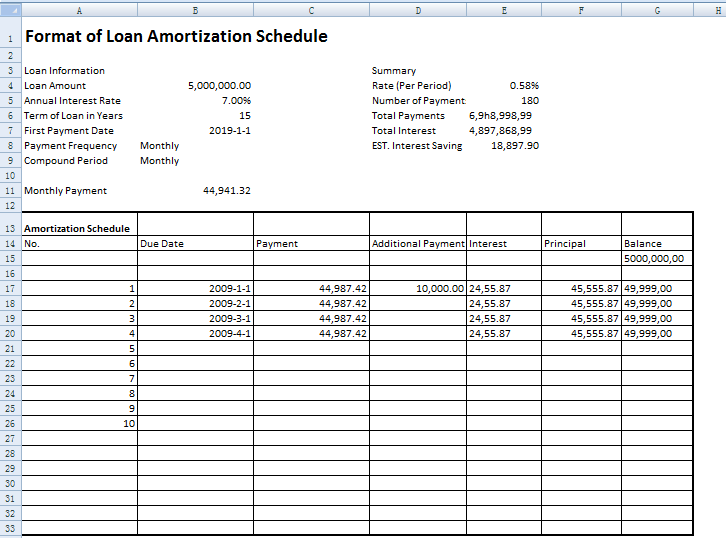
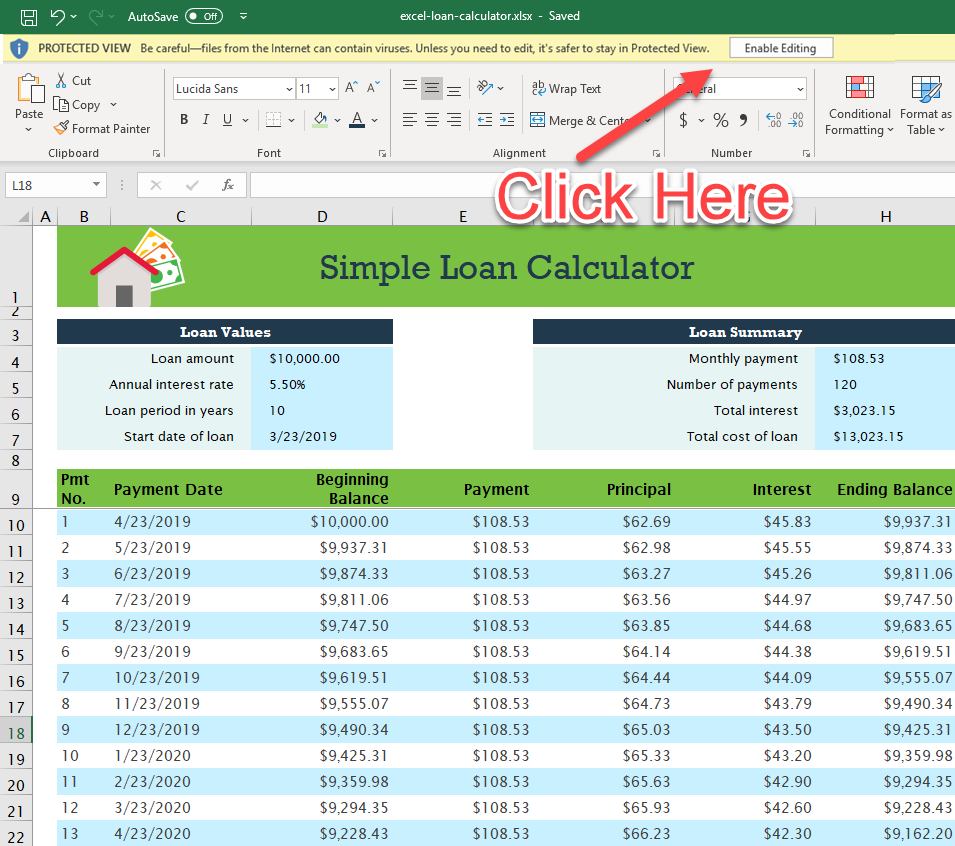
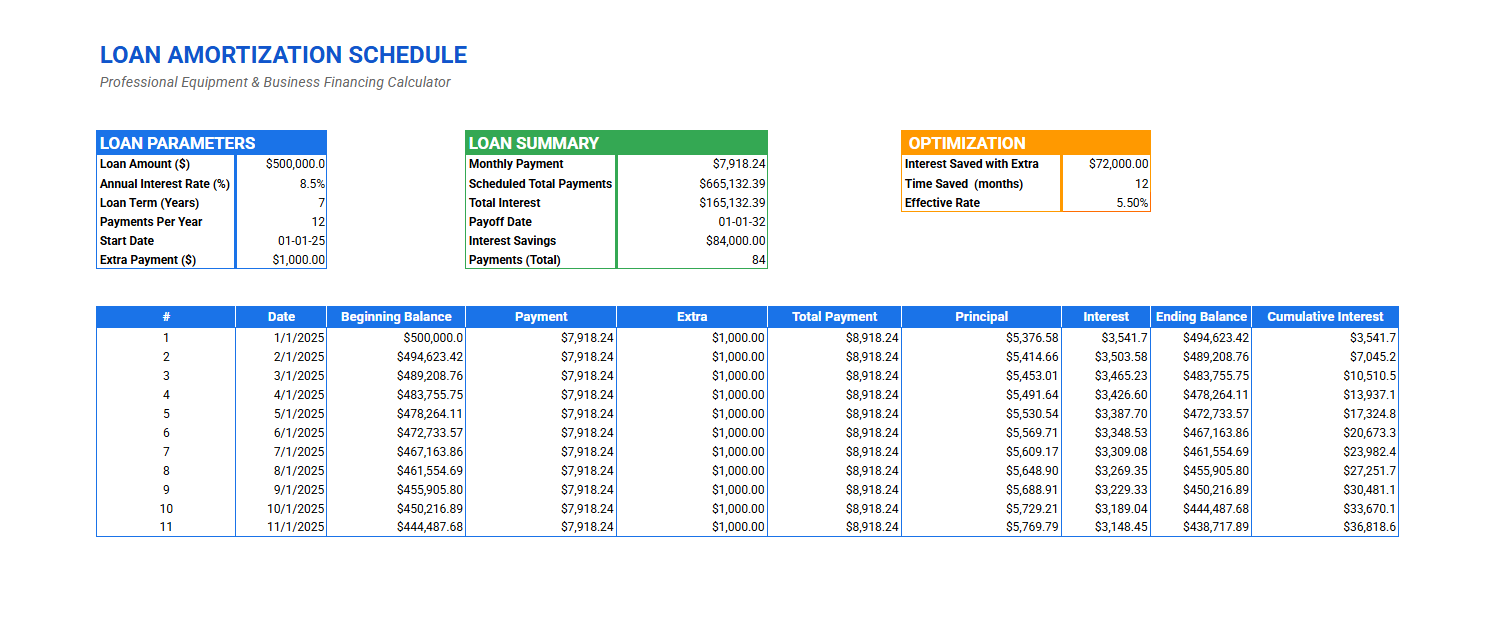
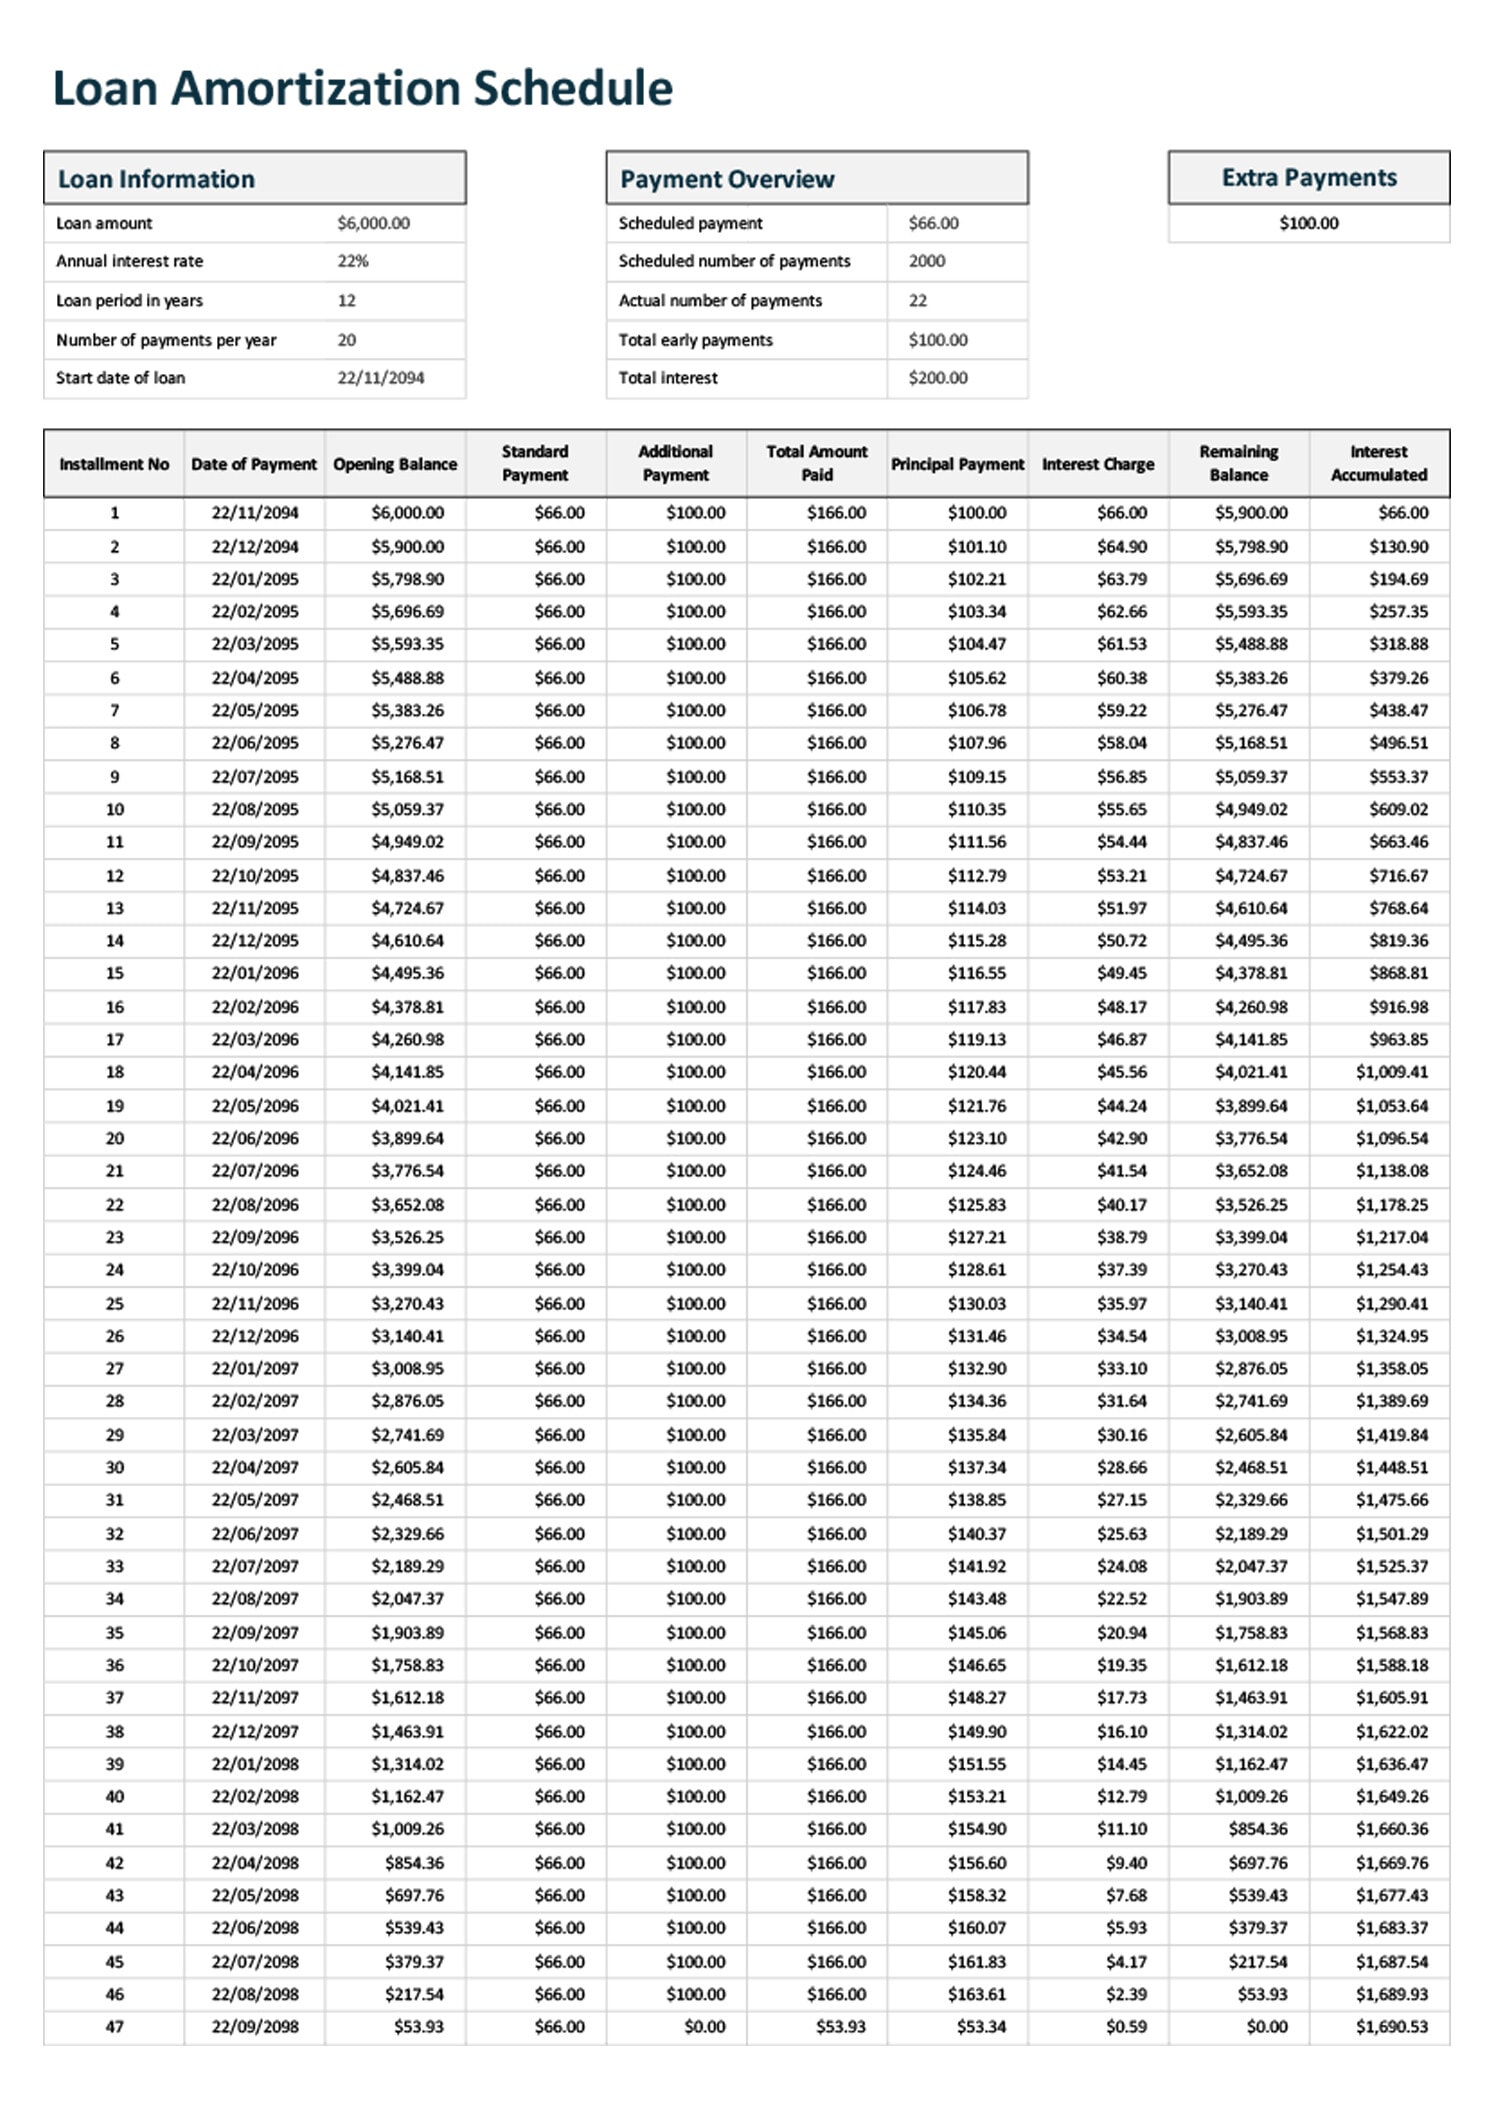
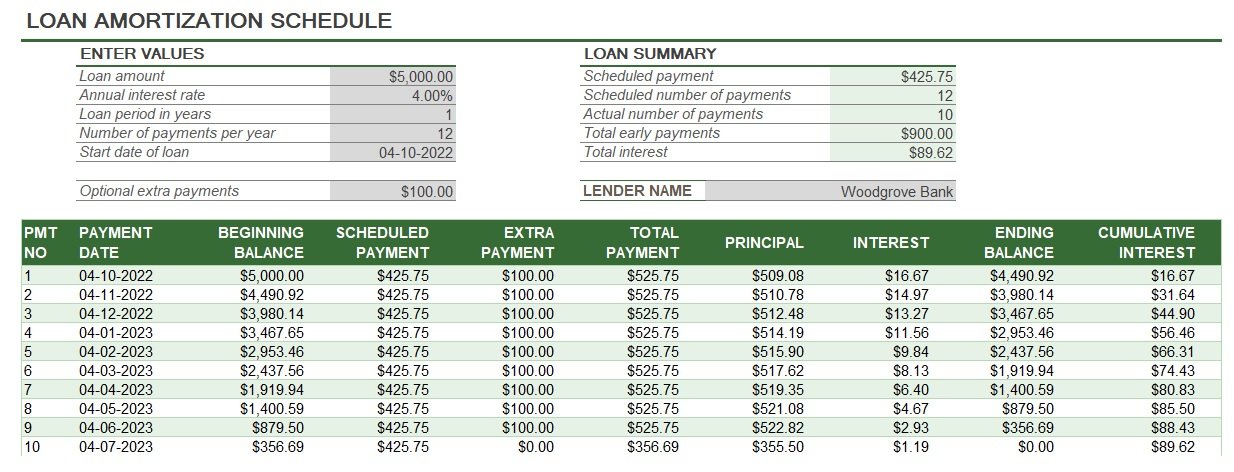
A loan format in Excel is really just a spreadsheet where you put in the principal amount, interest rate, and term, and it spits out your monthly payment. That's about it. The basic building block is the PMT function, which looks like this: =PMT(rate, nper, pv). You put your periodic rate in the first slot, total number of payments in the second, and the loan amount as a negative in the third so the result comes out positive. Most people skip the PV sign issue and just slap a minus in front of the cell reference instead. Either way works.Here is a concrete example. Say you have a 25,000 loan at 6.5% annual interest over 5 years. In cell B1 you put the principal, B2 the annual rate, and B3 the term in years. Your monthly payment formula goes in B4: =PMT(B2/12, B3*12, -B1). That gives you roughly 487.42 per month. Simple enough until things stop being simple. The standard amortization table has five columns: Payment Number, Payment Amount, Principal Portion, Interest Portion, and Remaining Balance. Column A is your payment numbers from 1 to however many months you're paying. Column B is always the same payment. Column C uses the PPMT function: =PPMT(rate, period, nper, pv). Column D uses IPMT the same way but for interest. Column E tracks the balance with something like =Previous Balance - Principal Paid, starting from your original loan amount. I spent three years doing this by hand for small business loans before I bothered building a reusable template. The first one I made was ugly. Cell references were scattered across six different sheets. I spent more time hunting down broken formulas than actually analyzing anything. What saved me was locking the formula structure into a single clean table and using absolute references for the loan inputs at the top. That cut my setup time from about forty minutes per new loan to maybe eight.
Where This Breaks Down
The PMT-based approach assumes a fixed rate and equal monthly payments. It completely falls apart if you're dealing with variable rates, balloon payments, or loans that have grace periods where you only pay interest for the first few months. I ran into this last year with a commercial real estate loan that had a 12-month interest-only period followed by a 30-year amortization schedule. The PMT function had zero utility for the first year. What I ended up doing was splitting the table into two sections. The first section used a simple interest calculation: =Remaining Balance * (Annual Rate / 12). Then in month 13, I recalculated the payment based on the remaining balance at that point using PMT with the new remaining term. It took an extra hour to set up but it handled the schedule correctly. Another thing nobody tells you: Excel rounds each row's principal and interest to two decimal places by default, which means your final payment will usually be off by a few cents from what the formula predicts. Over 120 months that rounding drift can add up to a dollar or two. I just add a small rounding adjustment to the last row or set the final payment cell to equal the remaining balance exactly. It's not glamorous but it keeps the table accurate. The bigger limitation is that none of this accounts for fees, insurance, or taxes if you need a full PITI calculation. You'd need to add those as separate line items. And if your loan has prepayment penalties or late fee structures, you are well past what a standard Excel format can handle cleanly at that point. You start building custom logic with IF statements and nested conditions, and the thing gets fragile fast. One wrong bracket and the whole amortization schedule goes sideways.
Practical Tips
Format your payment column as currency and your interest rate as a percentage. It sounds obvious but I have seen more spreadsheets where someone typed 6.5 instead of 0.065 and the whole table produced nonsensical results. Use data validation on your input cells so people can't accidentally paste text into a number field. Freeze the top rows so the headers stay visible when you scroll through a 360-month schedule. And name your input cells. Principal, AnnualRate, TermYears. It makes the formulas readable instead of having to figure out what B2 represents six months later. If you want a working template you can adapt, I keep one on my shared drive. It has the basic amortization table, input cells with data validation, and a chart showing the principal versus interest split over the life of the loan. Not much more than that. Just something that works without requiring a finance degree to maintain.
Get the Full Details