The Basics Nobody Gets Right
A loan from owner to business is when the person who owns a company puts their own personal money into the business bank account, and it needs to be recorded as a liability, not revenue. That's the most common mistake I see — owners treat the deposit like income or equity contribution without thinking about it, which then messes up the balance sheet and gets messy during tax season. The entry itself takes about thirty seconds once you know what you're doing, but getting it wrong once means six months of reconciliation work later. The journal entry is straightforward in theory. You debit Cash for the amount received and credit a liability account, typically Owner Loan Payable or Due to Shareholder. That's it. Two lines. But here's where people stumble: they don't set up a separate liability account for each individual who has loaned money to the business, and then when there are multiple investors or family members involved, everything collapses into one undifferentiated line item that nobody can trace back to a source.
Loan From Owner To Business Journal Entry
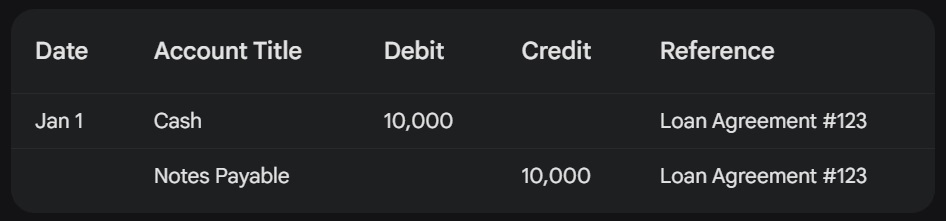
Here is the actual entry. When the owner transfers $10,000 from their personal account to the business checking account: Debit: Cash $10,000
Credit: Owner Loan Payable $10,000 If you are using QuickBooks Online or Xero, you create a new liability account under the current liabilities section called something like "Owner Note Payable" and tag the transfer to that account. Don't lump it into accounts payable — that account is for vendors, not people who own the company. AP aging reports are used by auditors and creditors. Mixing owner loans into AP makes your balance sheet look confused and raises questions that aren't worth answering.
If the loan has terms — interest rate, repayment schedule, maturity date — you should also be documenting that in a separate loan agreement file. I keep these in a folder on the shared drive named after the owner and the year the loan originated. Something like /Loans/JSmith_2024.pdf. You will need this document if you ever face an audit, a bank application, or a situation where the owner wants to leave and you need to settle up. Without it, you are working from memory, and memory is unreliable when someone is owing you twelve thousand dollars from eighteen months ago.
Get the Full Details

Where It Gets Complicated
Interest is the thing that trips people up. If the loan is interest-bearing, you need to accrue interest monthly or quarterly depending on your reporting cycle. The entry for accrued interest is a debit to Interest Expense and a credit to Accrued Interest Payable, which sits under the same liability bucket as the principal. When you make a payment that covers both principal and interest, you split it: debit Owner Loan Payable for the principal portion, debit Interest Expense for the interest portion, and credit Cash for the total. Most accounting software will let you do this manually, but if you are not careful you'll accidentally expense the entire payment and erode your equity without anyone noticing for a year. I had a situation a couple years ago where a business owner had taken out three separate loans from himself over four years. Different amounts, different dates, no interest charged on any of them. When he sold the business, the buyer's accountant asked for a complete breakdown of owner financing, and I spent two days digging through bank statements from 2019 to figure out which deposits were loans versus actual capital contributions versus reimbursed expenses. The workaround I ended up using was pulling every transaction from the owner's personal account that matched a business deposit, then cross-referencing with the general ledger to identify anything credited to Owner Loan Payable. It took about four hours, and it would have taken five minutes if the original books had been maintained properly from the start. The lesson there isn't dramatic. It's just that maintaining clean records for owner loans saves time later. A lot of time.
Common Mistakes and What to Do Instead
Mistake one: recording the loan as owner's equity. This inflates equity and understates liabilities, which makes your debt-to-equity ratio look better than it actually is. If you are applying for a SBA loan or any kind of business credit, lenders will see through this quickly and it damages credibility. Equity accounts are for money the owner is putting in permanently. Loans are money that has to come back out. Mistake two: never reconciling the owner loan account. I've seen businesses where the Owner Loan Payable account had a balance of $47,000 and nobody knew why. Payments had been made, additional loans had been taken, interest had accrued, and the sub-ledger was never updated. The account sat there at $47,000 for two years until someone finally went through and corrected it. Don't let that happen. Review this account quarterly at minimum. Even ten minutes a quarter takes less time than the alternative. Mistake three: treating owner loans the same as trade payables in your accounts payable workflow. Some people route owner loans through the AP module because it's convenient. This is wrong. AP modules are designed for external vendors with invoice-driven workflows. Owner loans don't have invoices. They have loan agreements and repayment schedules. Keep them in the general journal or in a dedicated loan tracking module if your software supports it.
The Tax Side You Can't Ignore
The IRS has rules about owner loans that most small business owners don't know about. If you charge little or no interest on a loan to your business, the IRS may impute interest under the below-market loan rules. This is codified in IRC Section 7872 and it matters even for loans between a sole proprietor and their own business, though the practical enforcement is thinner for single-owner entities. For multi-owner companies, it's something your tax preparer should be tracking. The practical threshold is that loans above $10,000 with no interest or below-market interest can trigger imputed interest calculations. If you loan the business $50,000 at zero percent interest, the IRS may treat a portion of that as imputed interest income to the owner and interest expense to the business, even though no money changed hands for interest. It doesn't mean anyone writes a check for it. It means your tax return needs to reflect it. Talk to your CPA about this before you assume it doesn't apply to your situation. The cost of addressing it proactively is usually a few hundred dollars. The cost of finding out about it after an audit notice arrives is significantly higher. There is also the issue of loan forgiveness. If an owner decides to forgive part or all of a loan they made to the business, that forgiveness is generally treated as a capital contribution for tax purposes. The entry is a debit to Owner Loan Payable and a credit to Contributed Surplus or Additional Paid-in Capital, depending on your entity structure and chart of accounts. Getting this wrong can create unexpected taxable income for the owner. I once saw a case where a loan forgiveness of $15,000 was incorrectly recorded as a reduction in expenses, which understated taxable income and led to a penalty that exceeded the original error by three times.
What Happens When the Business Fails
This is the part nobody likes to think about. If the business goes under and the owner loan is never repaid, you need to write it off. The entry would be a debit to Owner Loan Payable and a credit to Cash if you paid it back, or a debit to Owner Loan Payable and a credit to a loss account if the business simply cannot repay it. For a sole proprietorship, the distinction between personal and business is thin anyway. For an LLC or corporation, that loan is a real asset on the owner's personal balance sheet and a real liability on the business balance sheet, and the write-off has implications for both. The realistic problem here is that many owners never document the loan formally. No promissory note, no repayment schedule, no board resolution if it's a corporation. When the business fails and someone asks where the money went, there is no paper trail. I recommend that every owner loan over $1,000 have at minimum a dated promissory note signed by the owner and the business, kept in the corporate records. It doesn't need to be a lawyer-drafted document for small loans. A simple one-page note with the amount, date, interest rate (even if zero), and repayment terms is enough to establish the existence and terms of the loan for tax and legal purposes.
Quick Reference for the Entry
When owner lends money to business: Debit: Cash
Credit: Owner Loan Payable When owner makes interest payment:
Debit: Interest Expense
Credit: Cash When owner loan is repaid: Debit: Owner Loan Payable
Credit: Cash

When owner forgives loan: Debit: Owner Loan Payable
Credit: Contributed Surplus Keep the account clean, keep the documents organized, and don't let it sit there unreviewed for more than a year. That's all there is to it.