How to Build a Loan Payback Calculator in Excel That Actually Works
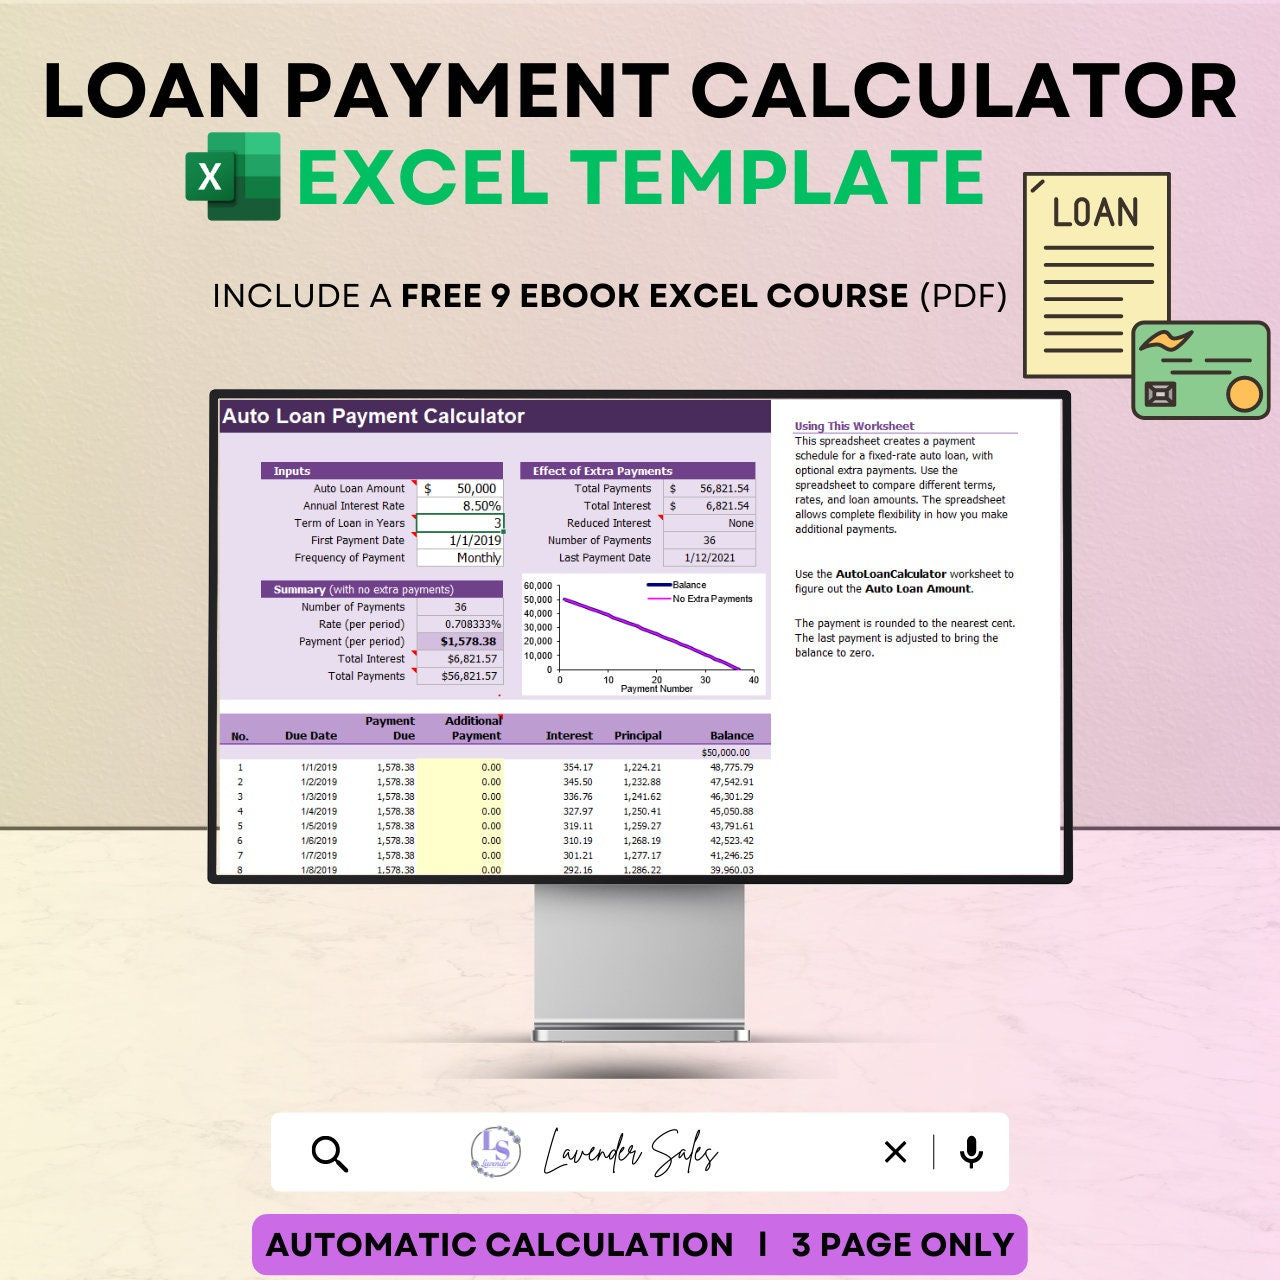
The simplest way to create a loan payback calculator in Excel is to use the PMT function for monthly payments and the CUMPRINC function for tracking principal reduction over time. Most people overcomplicate this by trying to build custom amortization schedules when the built-in financial functions do the heavy lifting for you. Here is what you need in your spreadsheet. In cell A1, label it "Loan Amount" and put the principal in B1. In A2, label it "Annual Interest Rate" and put the decimal rate in B2. In A3, label it "Loan Term (Years)" and put that number in B3. Now you can calculate monthly payments with the formula =PMT(B2/12,B3*12,-B1). The negative sign on B1 flips the result to a positive number so it reads cleanly.
Loan Payback Calculator Excel Setup
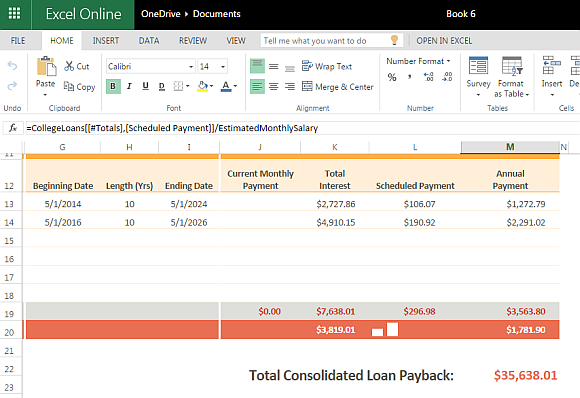
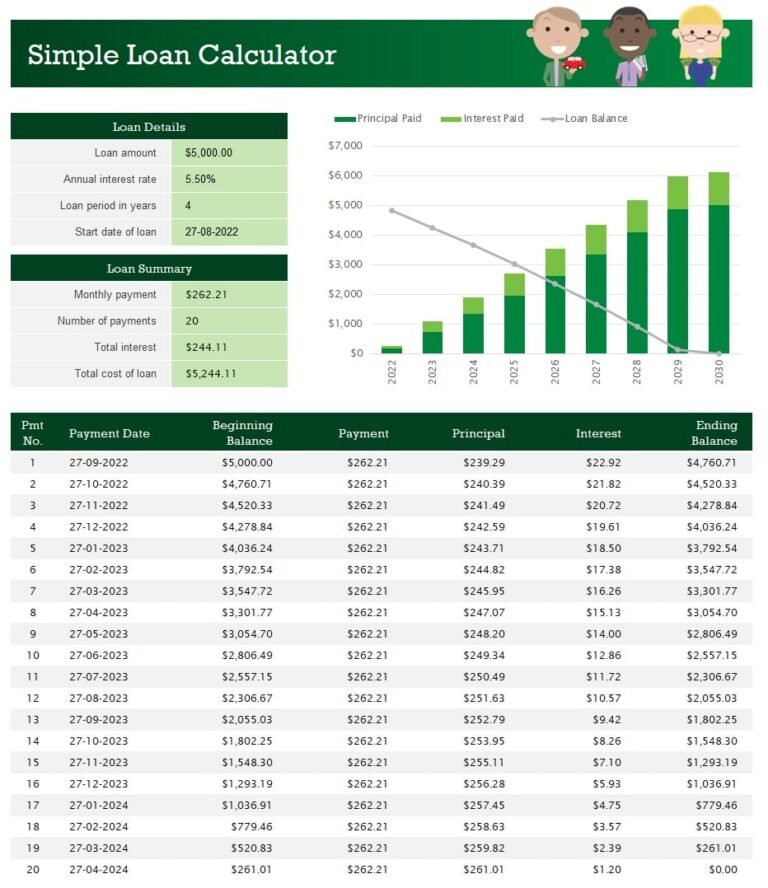
To find out exactly how long your loan will take to pay back under different scenarios, you need the NPER function. The formula =NPER(B2/12, -C5, B1) where C5 is your monthly payment will tell you the total number of months required. Divide that result by 12 to get years and months, which is more readable for most people reviewing the output. For a full amortization schedule, set up columns for Payment Number, Beginning Balance, Payment, Principal, Interest, and Ending Balance. The Beginning Balance for row 1 is your loan amount. The Interest portion of each payment is =B2/12*BeginningBalance. The Principal portion is your total payment minus the Interest portion. The Ending Balance is Beginning Balance minus Principal. Then the next row's Beginning Balance is the previous row's Ending Balance. Drag that down for the full term and you have a complete payoff schedule without writing a single custom formula beyond the first two rows. I ran into a specific problem last year when a client needed to model a loan with irregular payment dates because their funding closed mid-cycle. The standard NPER and PMT functions assume uniform periods, which threw off their projected payoff date by nearly three months. I solved it by building a day-count-based schedule using the XIRR function to calculate the actual yield and a custom cash flow table that tracked each payment against the exact number of days between disbursement and payment date. It took about 45 minutes to set up instead of the 10 minutes a standard model would have taken, but the accuracy difference was material for their reporting requirements.
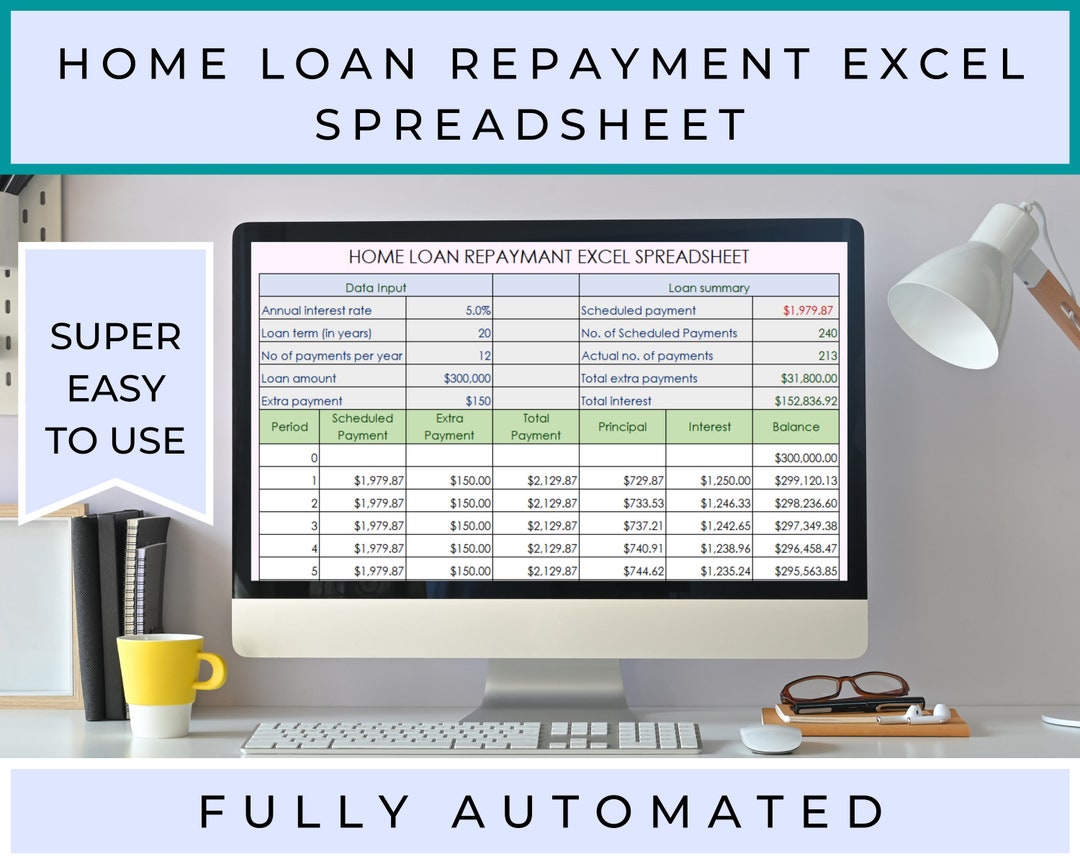
There are a few things most beginners miss when they build these calculators. The first is that the PMT function returns a payment based on constant payments and a constant interest rate. If your loan has an adjustable rate, the calculator becomes useless after the first adjustment period unless you rebuild the entire model with the new rate. The second is that many people forget to account for escrow. Your PMT calculation gives you principal and interest only. Property taxes and insurance are often bundled into the total monthly payment but are invisible in the formula, which means your actual housing expense is higher than what the calculator shows. Another counter-intuitive detail is how extra payments work. If you want to model making additional principal payments, you cannot simply change the loan term or payment amount in the standard setup. You need to add a column for "Extra Payment" and recalculate the ending balance each period by subtracting both the regular principal and the extra payment from the beginning balance. A small extra payment of just $100 per month on a 30-year loan at 6 percent can cut the payoff timeline by roughly 4 to 5 years depending on when you start making them. The savings in total interest are significant but not always obvious from looking at the monthly payment alone. The biggest limitation of a basic Loan Payback Calculator Excel model is that it assumes you will make every payment on time, every month, forever. Life does not work that way. If you miss a payment, the interest compounds on the unpaid balance and your payoff date shifts. A good workaround is to add a simple scenario analysis using data tables. Set up a table that shows payoff dates for different assumptions about missed payments or variable income, so you can see how sensitive your timeline is to payment consistency.
Get the Full Details

For people who need something more robust, especially if they are modeling multiple loans with different terms, rates, and payment frequencies, Excel is still capable but gets unwieldy quickly. At that point, a dedicated loan modeling tool or even a simple Python script with the numpy financial functions becomes more efficient. But for a single loan or a handful of loans, a well-structured Excel model with the functions described above will serve you well and usually takes less than 20 minutes to build from scratch.