Building a Loan Payment Calculator in Excel
Most people use PMT wrong, and it's not even that complicated once you see what's actually happening under the hood. I've been throwing together loan calculators for clients since the mid-2000s, and the same mistakes show up in every single file.Loan Payment Calculator Excel
The basic structure starts with four inputs: loan amount, annual interest rate, loan term, and payment frequency. Excel's PMT function handles the math, but the inputs have to be formatted correctly or everything breaks silently.The most common error I see is plugging in an annual rate directly. PMT expects the rate per period. A 6% annual rate on monthly payments means 6%/12 = 0.5% per month. If you skip this step, your payment will be wildly off and you won't catch it until you cross-check against a bank statement.
The formula itself looks like this: =PMT(rate, nper, pv, [fv], [type]) Where rate is the periodic rate, nper is total number of payments, pv is the present value (loan amount), fv is optionally zero (the balance at the end), and type is 0 for end-of-period payments or 1 for beginning-of-period.I built a Mortgage Loan Calculator template that handles this conversion automatically, so users just input their annual rate and the sheet figures out the monthly equivalent. Saves people from making the exact mistake I'm describing here.
Setting Up the Amortization Schedule
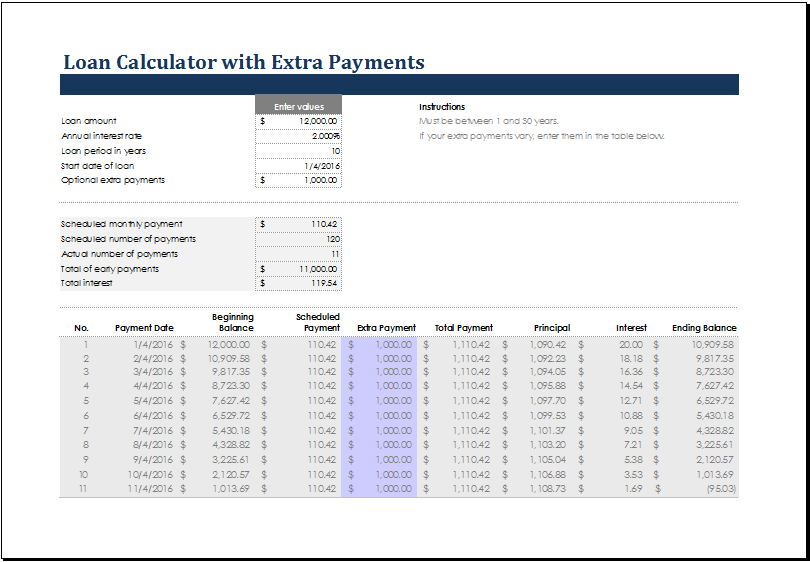
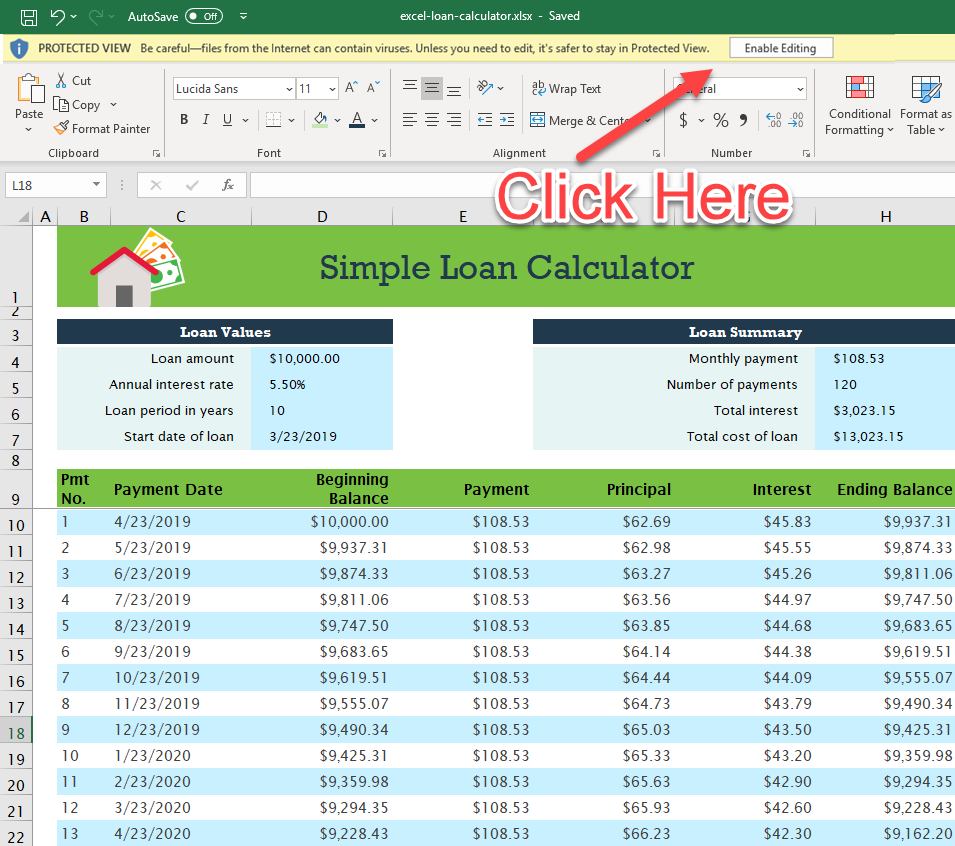
A single PMT cell is useful, but the real value comes from the full amortization schedule. Each row shows how much of the payment goes toward principal versus interest, and what the remaining balance is.The interest portion for any given period is straightforward: it's the beginning balance multiplied by the periodic rate. The principal portion is the total payment minus the interest portion. The new balance is the previous balance minus the principal paid.
Get the Full Details
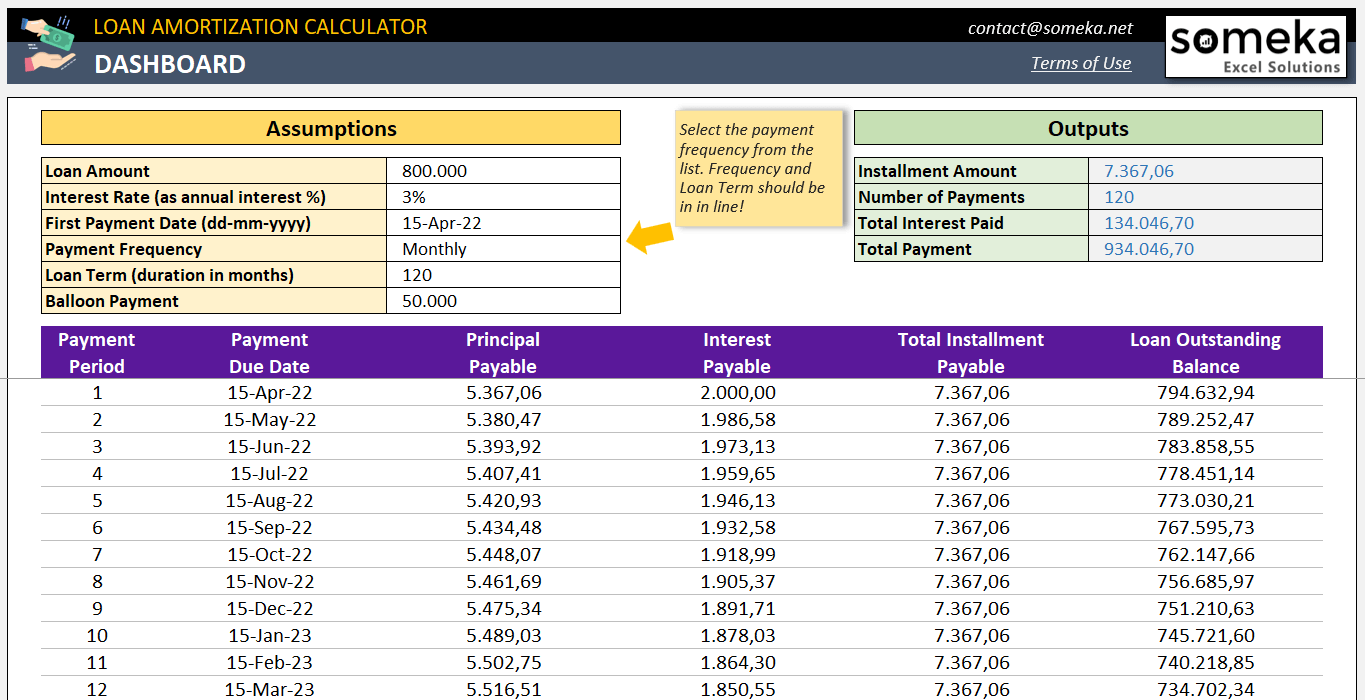
When I was building this for a commercial real estate client last year, they had a balloon payment structure with irregular final terms. The standard amortization schedule broke because the last payment differed from all the others. The workaround was splitting the schedule into regular periods and a final adjustment row that calculated the remaining balance manually.
Common Pitfalls That Actually Matter
Excel calculates PMT assuming equal payments throughout the loan term. Real loans sometimes have graduated payment structures, adjustable rates, or deferred interest periods. The function doesn't account for any of that.If your loan has an adjustable rate that changes every few years, you'll need to rebuild the schedule each time the rate adjusts, or build multiple PMT calculations with conditional logic. One borrower I worked with had an ARM that reset every five years, and his initial amortization schedule was completely irrelevant after the second adjustment. I ended up building a macro that recalculated the entire schedule whenever the rate changed.
Another issue: negative results. When you enter the loan amount as a positive number, PMT returns a negative payment. This is Excel's convention, but it confuses people who expect a positive dollar figure. Prefix the formula with a negative sign or use a negative PV argument to flip it.What the Calculator Can't Do
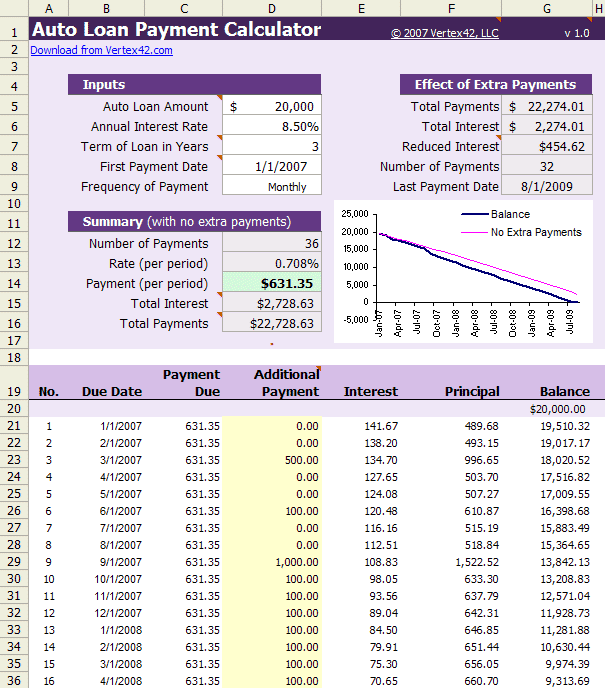
PMT assumes payments are made at the same interval as the compounding period. If your loan compounds monthly but you make biweekly payments, the formula becomes inaccurate. You'd need to calculate the effective biweekly rate or build a custom function.Prepayment penalties are another blind spot. The calculator shows what happens if you pay extra, but it can't model penalty fees that some lenders charge for early payoff. Those exist in the fine print, not in the spreadsheet.