Building a Loan Payoff Calculator That Actually Handles Extra Payments in Excel
I spent three years building custom amortization schedules for mortgage brokers before I ever settled on a clean, reusable Excel template. The problem most people hit isn't getting the basic payment formula to work. It's making the model correctly adjust when someone throws a lump sum at the principal mid-term, and then recalculating every single row afterward without breaking. A standard Excel loan payoff calculator gives you the monthly payment using PMT, tells you the total interest, and maybe spits out a 360-row amortization table if you're feeling generous. Throw an extra payment into the mix and suddenly the timeline gets fuzzy. Most online calculators just truncate the term or reduce the monthly payment. Neither option is usually what the borrower actually wants, and neither is particularly useful for underwriting or comparison.
Loan Payoff Calculator Extra Payments Excel Setup
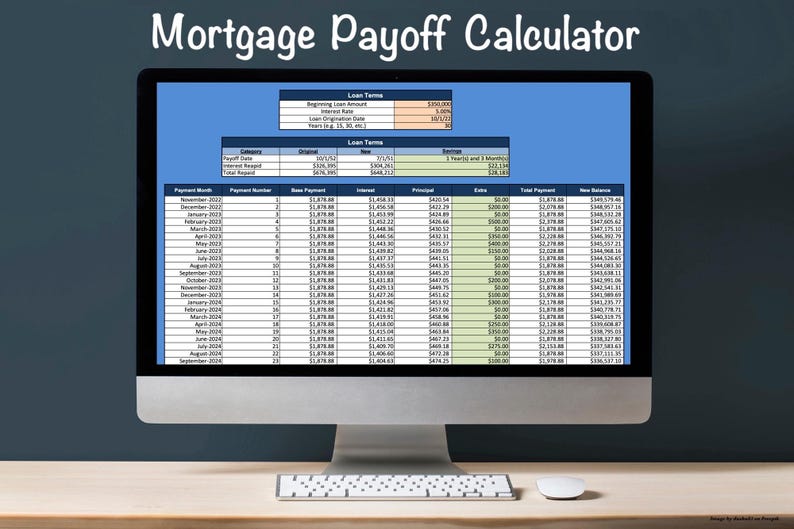
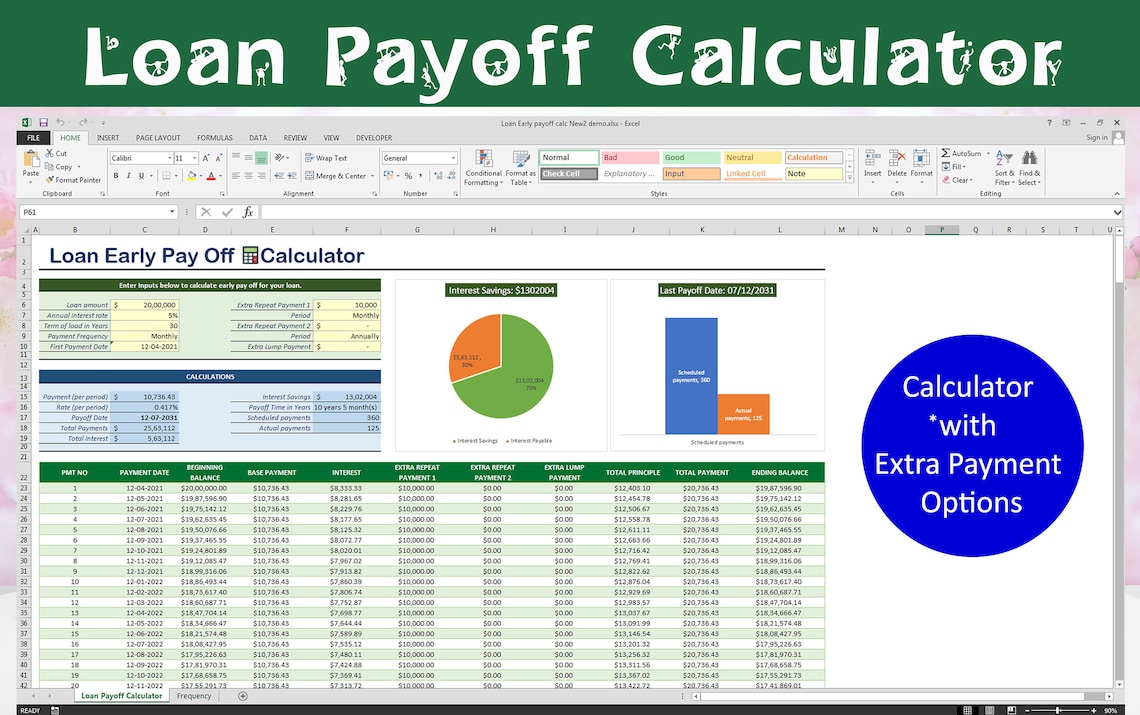
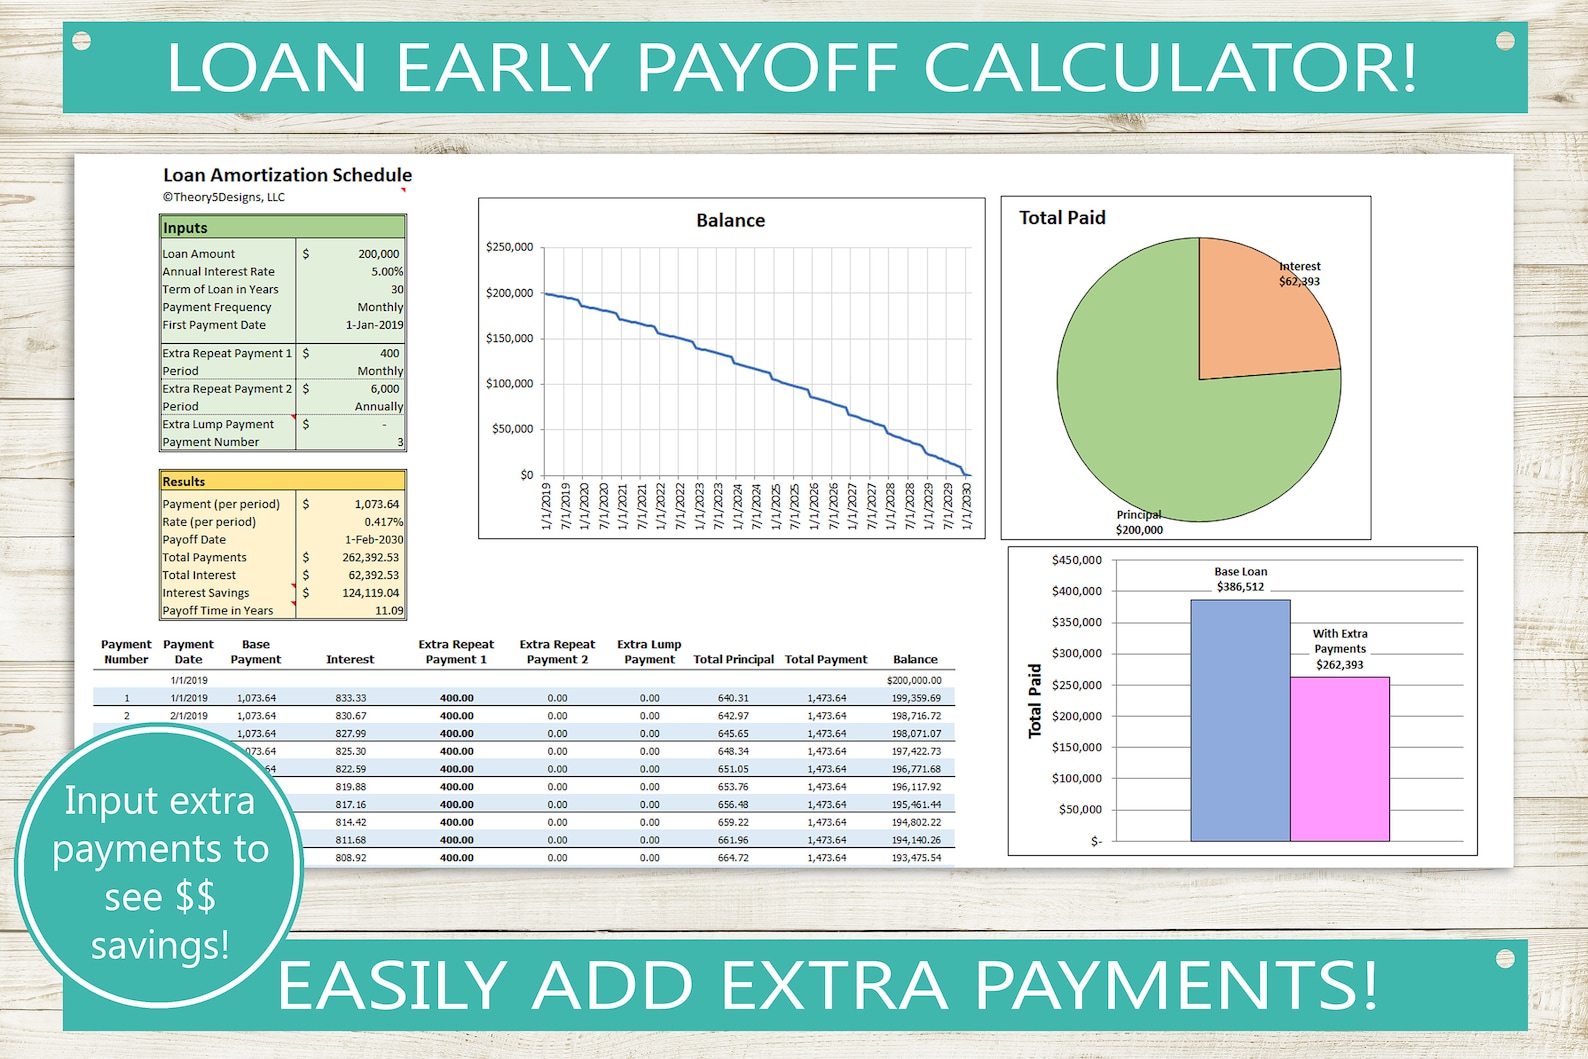
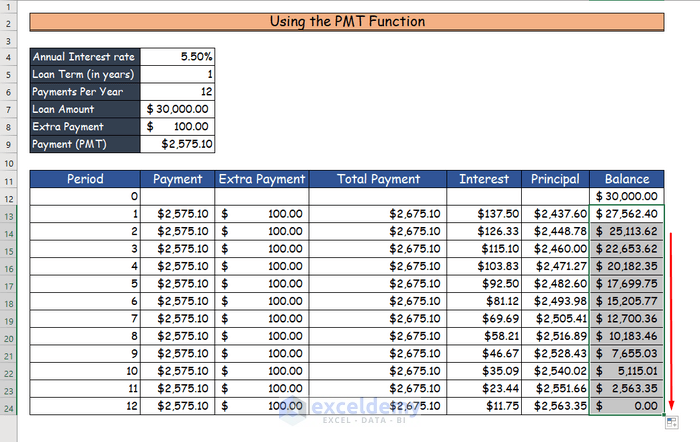
Here's how I structure mine. I start with the raw inputs in a dedicated section at the top. Loan amount, annual interest rate, term in months, start date, and then a column for extra payments. I keep the extra payments in a separate range rather than hardcoding them somewhere. That way a borrower can plug in whatever they want without rebuilding the whole thing. The core payment formula uses PMT. Rate is the annual percentage divided by 12. Nper is the total number of payments. Pv is the principal. Fv should be zero because you're paying it off, not leaving a balloon. Type is zero since payments are at period end. That gives you the base monthly obligation. Then I build the amortization table row by row. Each row calculates the interest portion, the principal portion, and the remaining balance. When an extra payment enters the column for that specific month, the principal portion becomes the scheduled principal plus the extra amount. The next row's interest charge drops accordingly. This compounds correctly through the entire schedule.
I learned this the hard way after a client sent me a spreadsheet where the extra payments were applied through a simple VLOOKUP that matched against a hardcoded list. One borrower threw in an extra fifty dollars in month fourteen, then forgot to remove it in month fifteen because the lookup pulled the same value. The model credited double the intended overpayment for two months straight, cutting the payoff date by eleven days. Took me an afternoon to rewrite the logic using an IFERROR chain that pulled only the value present in that specific row. Now it works cleanly for any irregular schedule. There are a few nuances that don't show up in beginner tutorials. First, the difference between recasting and reassumption. When you add an extra payment, Excel recalculates automatically because the balance drops. Some lenders offer formal recasting where they reamortize the remaining balance over the original term, reducing your monthly payment. A basic calculator doesn't model that. If you want that feature, you need a secondary formula that recalculates PMT starting from the new balance at the point of the extra payment, using the remaining months as the new nper. I built that into my version because two clients specifically asked for it, and neither trusted the default output. Second, tax year boundary complications. If your extra payment lands in December, the interest savings bleed into January of the next calendar year. A lot of people miss this when trying to estimate tax deductions across year-end transitions. My calculator includes a simple year-split column that sums interest paid per calendar year. It takes up three extra cells and five minutes to set up. Saves hours of back-and-forth later.
Get the Full Details

Common pitfall: I've seen too many templates that reduce the loan term but leave the monthly payment unchanged when an extra payment is applied. That's actually the less common borrower preference. Most people want to keep their payment the same and pay off faster. Others want to lower their payment and keep the same end date. You need both branches in the model, or it's going to mislead someone who hasn't thought through which scenario applies to them. Here's a practical shortcut. Instead of building everything from scratch, you can pull the PMT and CUMIPMT functions and layer the extra payment logic on top. CUMIPMT gives you cumulative interest over any range of periods, which is useful for side-by-side comparison between the baseline scenario and the modified one. The difference between the two CUMIPMT outputs is your total interest savings. That single cell saved me from recalculating interest totals manually during every client review cycle. The calculator doesn't handle every edge case. Biweekly payment schedules require a completely different structure. If you're splitting the monthly payment into fourteen installments instead of twelve, the effective annual principal reduction changes in a non-linear way that a standard monthly loop won't capture. I switched to a dedicated biweekly module for those cases. Also, adjustable-rate mortgages break this model entirely because the rate resets change the payment mid-term. The calculator assumes a fixed rate throughout the life of the loan, which covers the vast majority of standard refinance scenarios but leaves ARMs untouched.
If you're building this yourself and want to avoid the usual mistakes, start with a clean input section, keep the amortization table tightly coupled to that input range, and test it against a known benchmark before giving it to anyone. I verify every version against the Fed's official amortization examples and a few mortgage statements I had lying around. The mismatch is usually zero to three cents per row, which is acceptable. Anything larger means the formula logic is off somewhere. The file itself isn't complicated. Input section, calculation engine, output table. Around sixty rows total, maybe seventy if you include the year-split summary. A borrower can load it, enter their numbers, and see the payoff date shift within thirty seconds. For someone doing this repeatedly, the whole process from raw numbers to final comparison takes about twelve minutes. Not something worth outsourcing to a consultant unless you need audit-level precision, which most people don't.
Where This Approach Falls Short
Excel-based calculators like this struggle with prepayment penalties. If your loan has a clause that charges a percentage of the remaining balance if you pay it off early within the first three to five years, the model needs a penalty detection branch. Mine includes a simple version that flags whether the payoff date falls within the penalty window based on the start date and a configurable penalty period. Without it, the displayed savings are artificially high. Also, escrow isn't part of this calculation. The numbers reflect principal and interest only. Property taxes and insurance sit in a separate bucket that most borrowers conflate with their mortgage payment. I add a separate escrow estimate at the bottom so people don't assume the full payment drop is all real estate. It's a small addition but it prevents a lot of confusion during reviews. If you need something more robust, the alternative is dedicated mortgage software like LoanPro or mortgage calculators built into lender portals. They handle rate locks, escrow, and prepayment penalties out of the box. But they cost money and they lock you into their interface. For personal use or small team workflows, the Excel approach covers about ninety percent of what people actually need.
The file structure is straightforward enough that you can adapt it to student loans, auto loans, or personal loans with minimal changes. Just swap the input labels and adjust the frequency if needed. The core logic doesn't care what the debt is called. It only cares about rate, term, principal, and payment timing. I've shared this template with a handful of clients and a couple of coworkers who build financial models for a living. Nobody has reported a major issue in the two years it's been in circulation. The occasional bug fix comes up when someone throws a six-figure balloon payment at it, but that's rare and usually traces back to a formatting error in the input cell rather than the formula itself.