Building a Loan Repayment Calculator in Excel
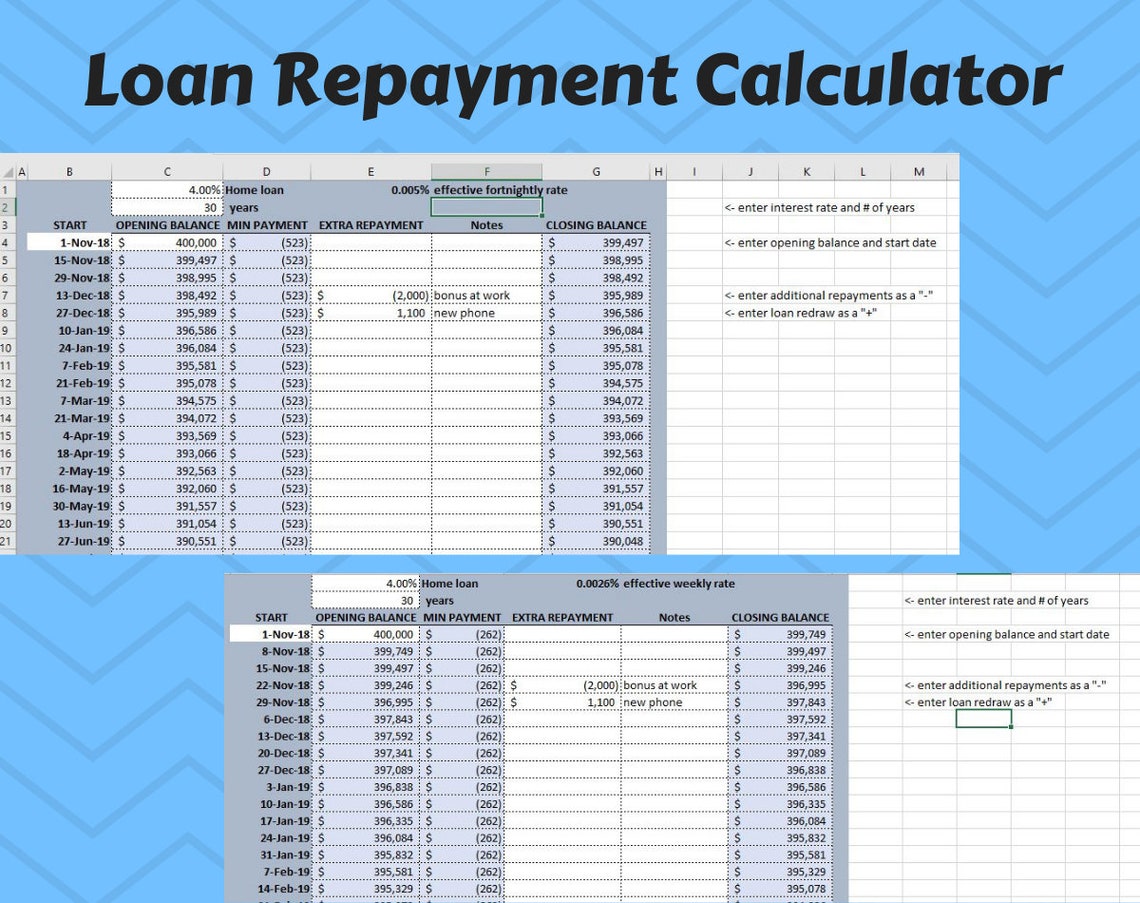
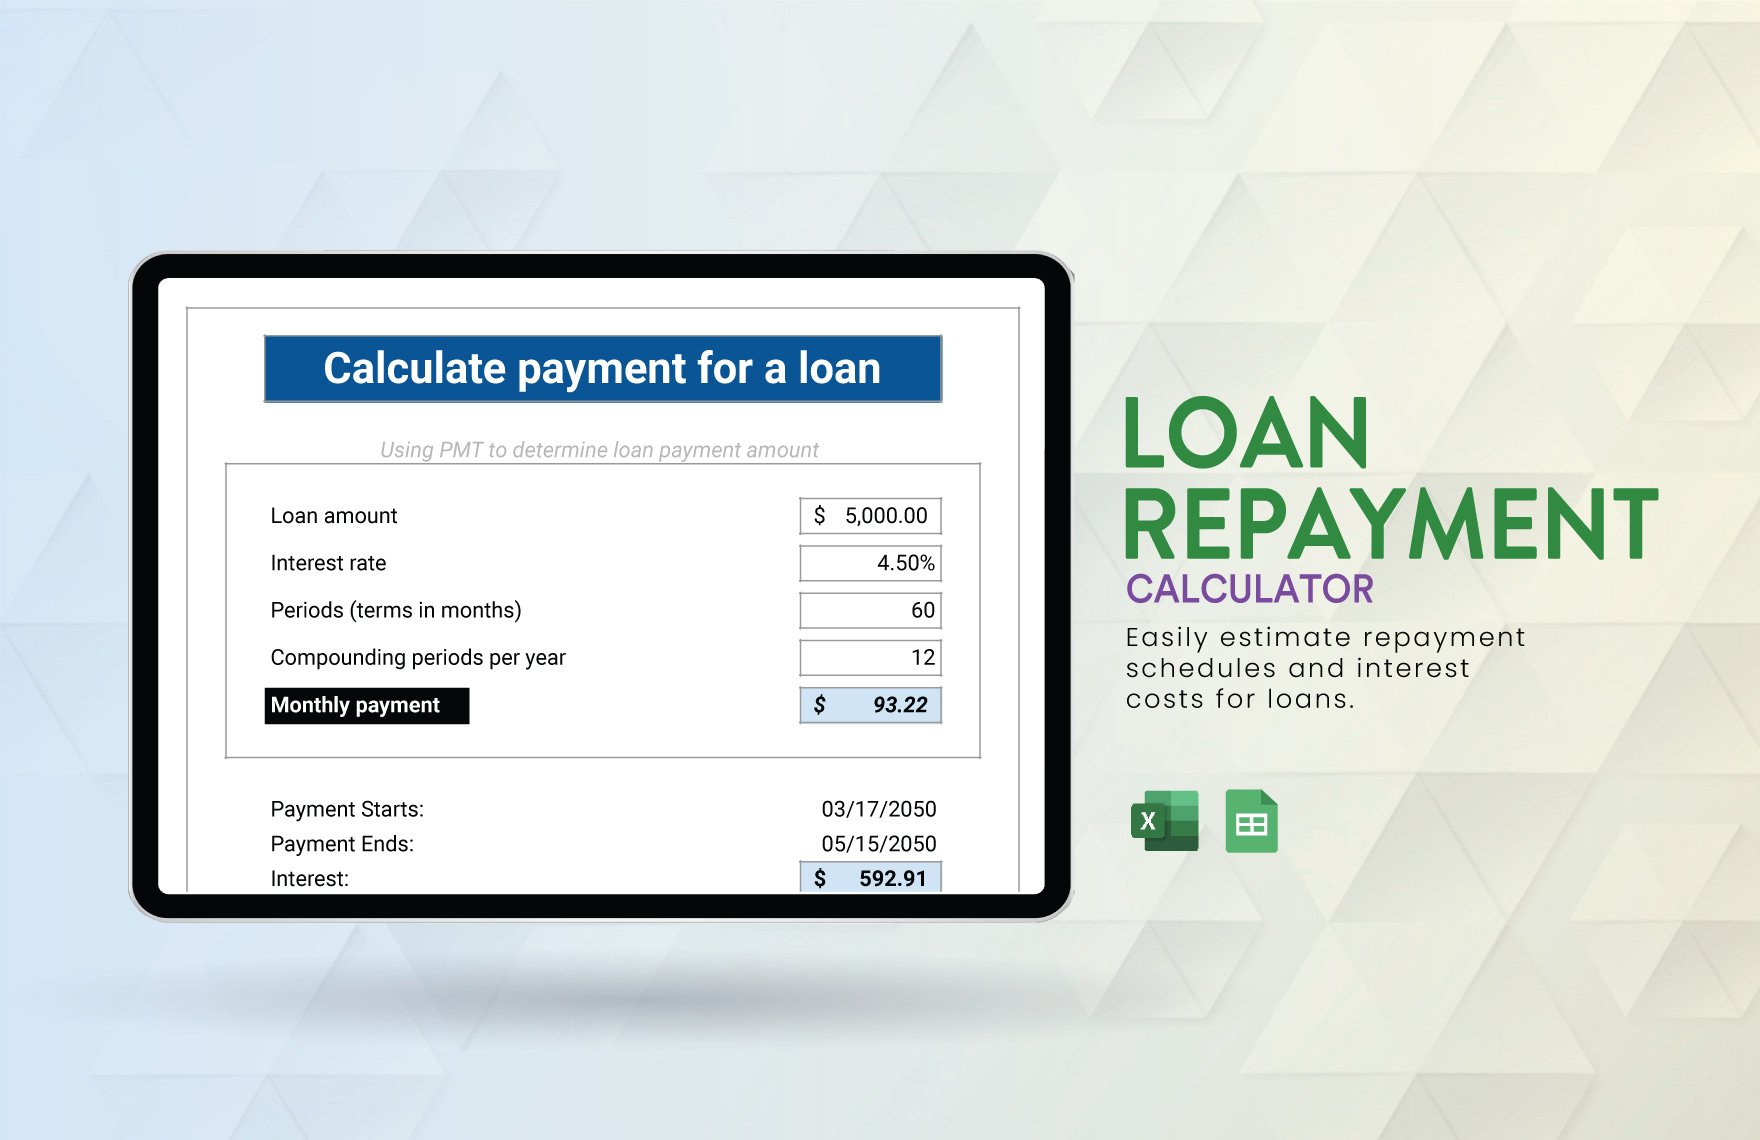
Most people don't need a fancy app to calculate loan repayments. A basic Excel spreadsheet does the job just as well, and it gives you full control over the inputs. The PMT function is the standard way to do this in XLS format. It handles the math so you don't have to derive the amortization formula from scratch. Start with a clean sheet. Put your labels in column A and your input values in column B. The essential inputs are the loan amount, the annual interest rate, and the total number of payment periods. I usually add a fourth row for payment frequency so you can switch between monthly and biweekly calculations without rewriting formulas. Label each cell clearly. When you come back to this spreadsheet three months later and try to figure out what you built, clear labels save you from headaches. For the formula, the PMT function takes three core arguments: the rate per period, the total number of periods, and the present value or loan amount. The rate needs to be divided by however many payments occur per year. If you're working with a 6.5 percent annual rate on monthly payments, you enter 6.5%/12, not just 6.5 percent. That is the single most common mistake I see. People plug the annual rate straight in and get a payment number that is twelve times too large.
The structure of the spreadsheet matters more than the formula itself. Here is a practical setup that works reliably: Cell B1: Loan Amount, say 250000
Cell B2: Annual Interest Rate, say 6.5%
Cell B3: Loan Term in Years, say 30
Cell B4: Payments Per Year, 12
Cell B5: Payment Formula using PMT The actual formula in B5 looks like this: =PMT(B2/B4,B3*B4,-B1). The negative sign before B1 forces the result to display as a positive number. Without it, Excel returns a negative payment, which is technically correct because it represents cash outflow, but it confuses people who aren't familiar with how Excel handles cash flow direction.
Going Beyond the Basic PMT Formula
The PMT function gives you the base payment. It assumes a standard amortizing loan with no extra payments, no fees, and no prepayment penalties. That assumption breaks down fast once you try to model anything complicated. I built a client-facing calculator once for a small mortgage broker who wanted it to handle biweekly payments and show the interest savings compared to a monthly schedule. The first version I shipped was wrong because I didn't account for the fact that biweekly payments actually result in 26 half-payments per year, which equals 13 full monthly payments. The loan paid off roughly eleven months early on a 30-year term. My initial model didn't capture that acceleration at all. The fix was adding a separate payment calculation for the biweekly column: =PMT(B2/26,B3*52,-B1). Then I built an amortization table underneath that ran each payment against the remaining balance. The table showed the exact point where the loan cleared early and how much interest was saved. That table took about twenty minutes to set up but made the difference between a calculator that was merely decorative and one that was actually useful.
Get the Full Details

Building an Amortization Schedule
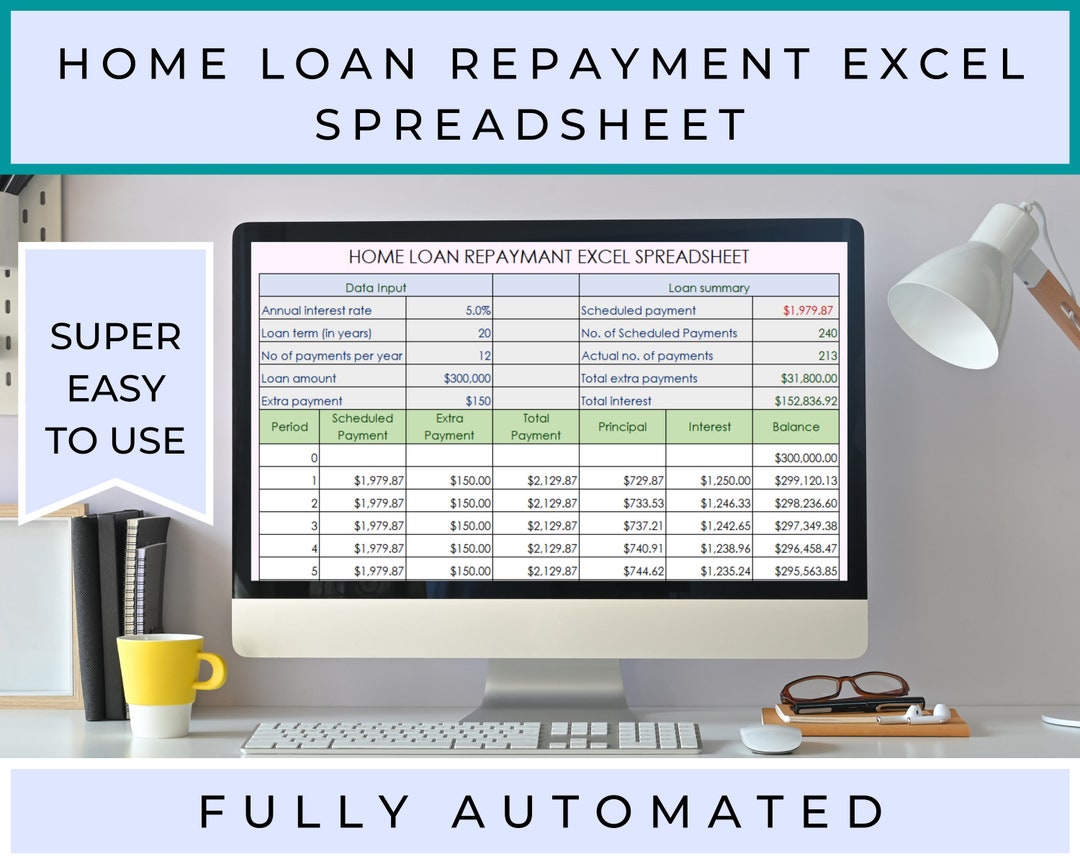
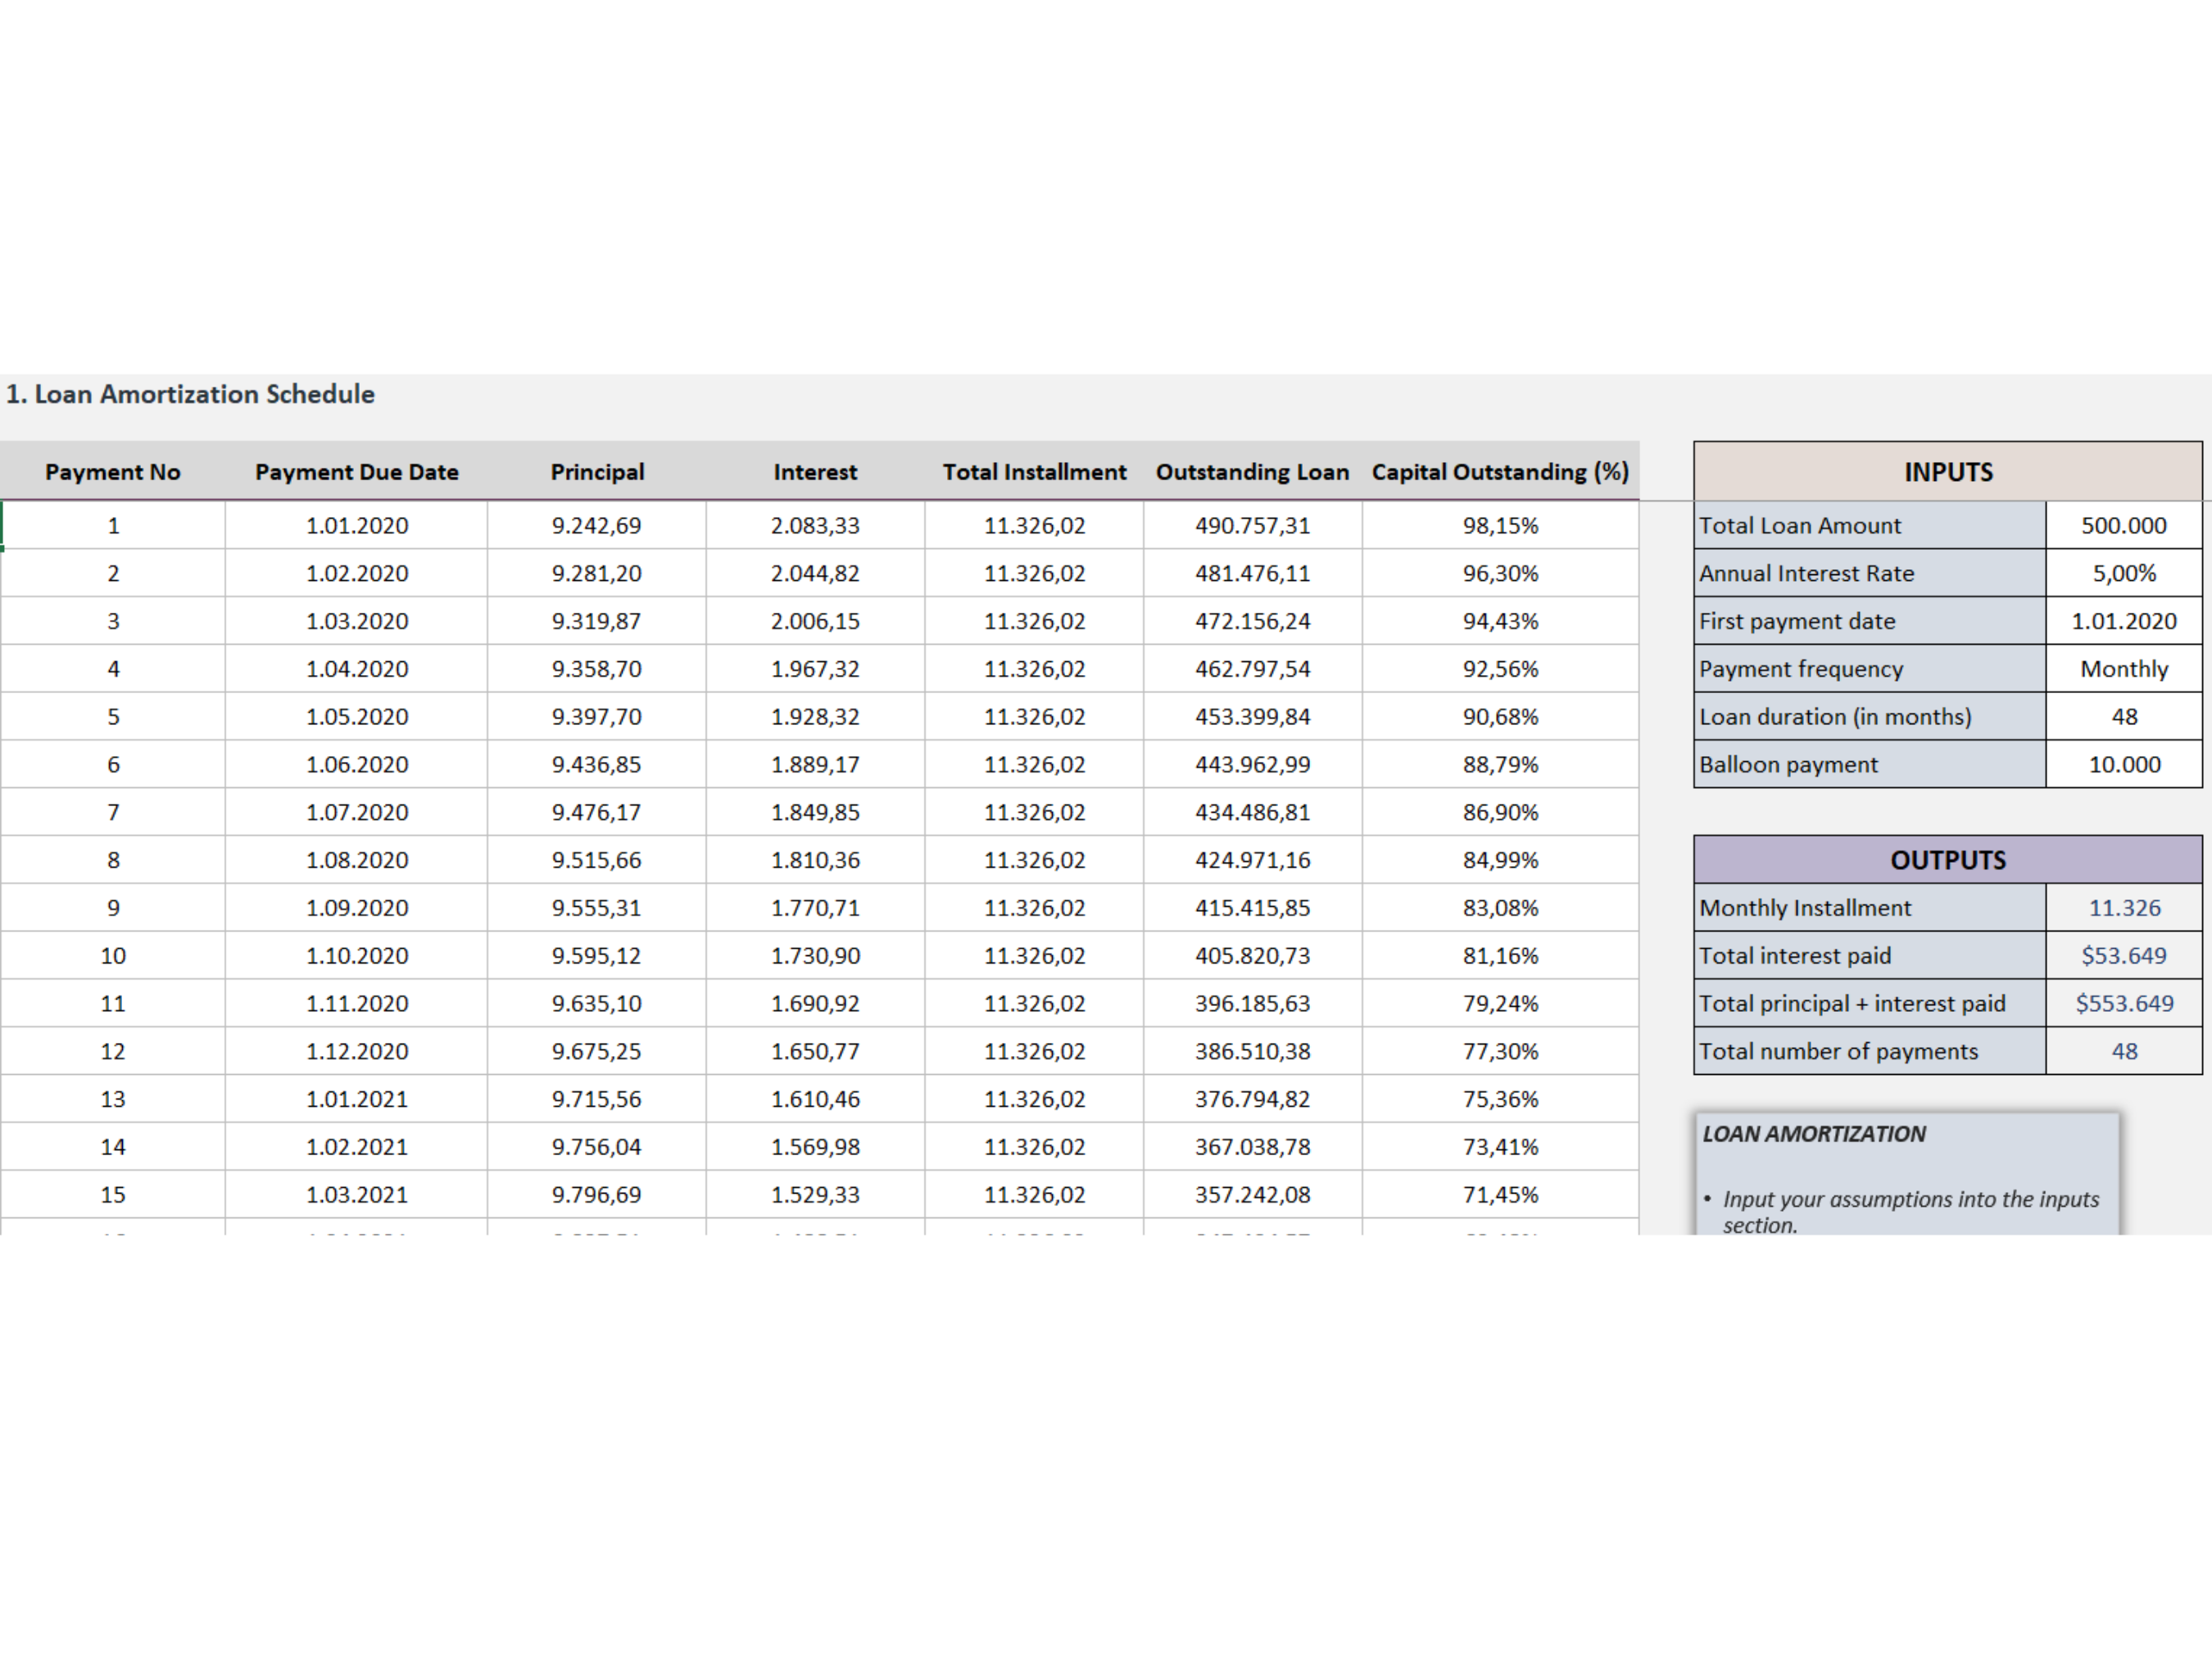
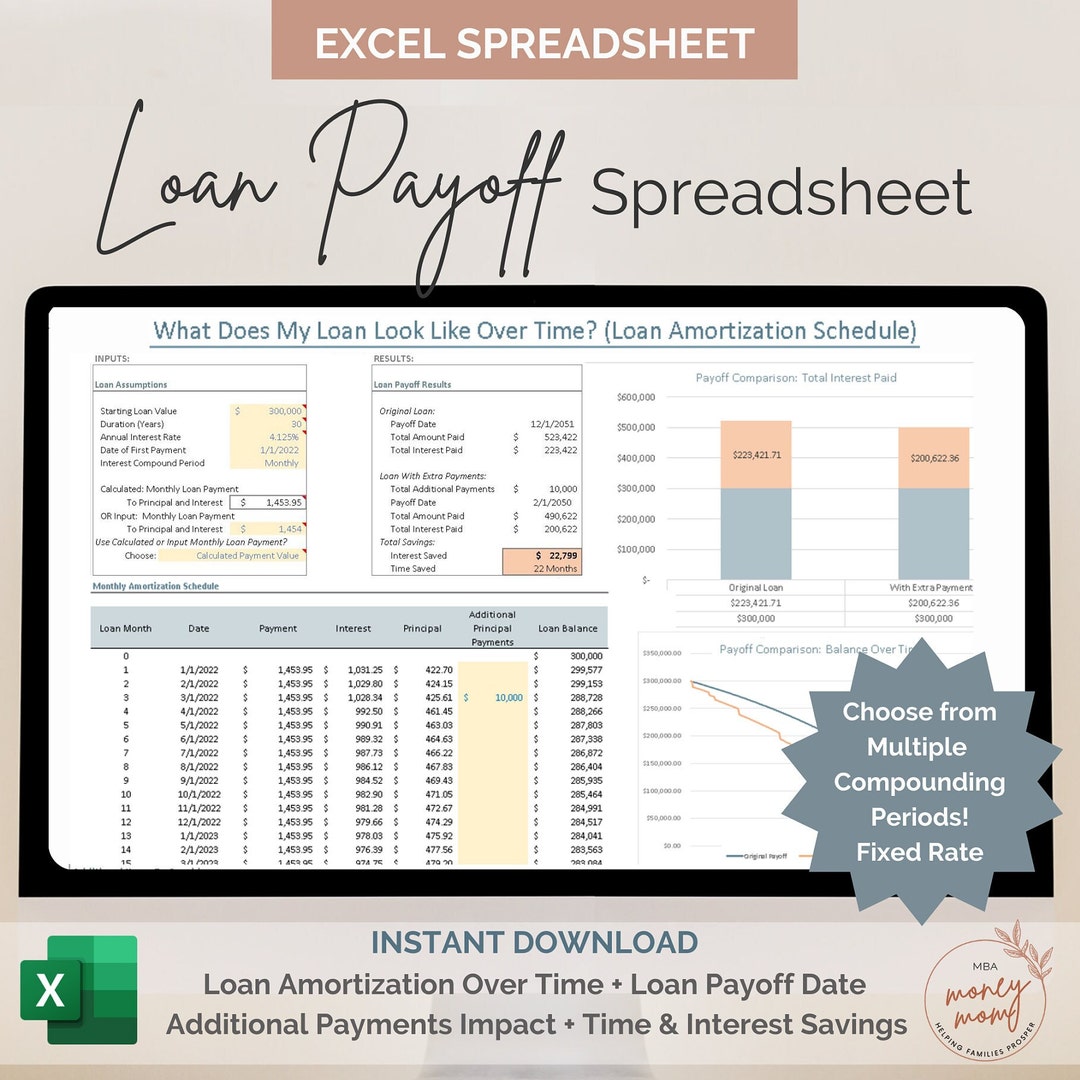
An amortization table is where the real value lives. The PMT formula tells you the payment. The table shows you what happens to each dollar over time. You need columns for payment number, beginning balance, payment amount, principal portion, interest portion, and ending balance. The interest portion for any given row is simply the beginning balance multiplied by the periodic rate. The principal portion is the total payment minus the interest portion. The ending balance is the beginning balance minus the principal portion. Here is how the key cells work in practice. If your periodic rate is in cell $B$2 divided by $B$4, you reference it absolutely so it doesn't shift as you drag the formula down. The interest calculation for row 2 of the table would be: =B10*$B$2/$B$4 where B10 holds the beginning balance. The principal calculation is: =B5-B11 where B5 holds the fixed payment amount. The ending balance is: =B10-B12. Drag those formulas down for the full term and you have a complete schedule. One thing that catches people off guard is that the principal and interest split changes every single period. Early in the loan, the interest portion dominates. By the middle of a 30-year mortgage, you are paying mostly principal. The schedule makes that visible. Most borrowers never see it unless someone builds a table for them.
Common Pitfalls and Edge Cases
There are several scenarios where a standard Loan Repayment Calculator Xls breaks down and you need to adjust your approach. Compound frequency is one. Some loans compound monthly, others daily. The PMT function assumes your payment frequency matches the compounding period. If they don't align, your calculated payment will be slightly off. I encountered this with a student loan calculator where the school reported daily compounding but payments were monthly. The difference wasn't huge, maybe four dollars over the life of the loan, but it was enough to make a precise calculator look unreliable. Another issue is loans with variable rates. PMT only works for fixed-rate loans. If the rate adjusts after a certain period, you need to split the amortization schedule into segments. Calculate payments for the initial fixed period, then recalculate the remaining balance at the new rate and build a second schedule. It is tedious but straightforward. I learned this the hard way when a client handed me a loan projection that looked perfectly normal for the first five years and then completely derailed. The underlying model had assumed the rate never changed. Down payments are another area where people make mistakes. The PMT function takes the loan amount, not the purchase price. If the purchase price is 300000 and the down payment is 60000, you enter 240000 into the formula. Some spreadsheets I've seen accidentally use the full purchase price and then try to subtract the down payment from the payment amount afterward, which produces nonsense results.
Advanced Adjustments
If you want the calculator to handle additional principal payments, you need to restructure the amortization table. Add a column for extra payments and adjust the ending balance calculation to subtract both the regular principal and the extra amount. Each subsequent row's beginning balance then reflects the accelerated payoff. This is how you model the real-world behavior of borrowers who throw extra money at their loans when they get bonuses or tax refunds. For prepayment penalties, there is no elegant Excel solution. You have to build conditional logic that checks whether a payment falls within the penalty window and adjusts the principal reduction accordingly. It is possible but messy. I usually tell people who need this level of accuracy to move to a dedicated loan management tool rather than trying to force it into a spreadsheet.
When a Spreadsheet Isn't Enough
A Loan Repayment Calculator Xls works well for simple, fixed-rate loans with straightforward terms. It struggles with adjustable-rate mortgages, loans with complex fee structures, or situations where you need to compare multiple scenarios side by side in real time. If you are evaluating dozens of loan options for a business decision, the spreadsheet becomes unwieldy quickly. You end up copying the same structure across multiple sheets and hoping you didn't introduce errors during the duplication. For those cases, I recommend using a dedicated financial modeling tool or even a properly configured Google Sheets template with data validation and scenario management built in. The underlying math is identical. The advantage is that the tool handles edge cases you might not have thought to include, like leap year adjustments in daily compounding calculations or tax implications on interest deductions. The core PMT approach remains the same regardless of platform. Understanding how the formula works and what each argument represents matters more than which tool you use to run it. A person who understands the mechanics can rebuild a broken calculator in fifteen minutes. A person who only knows how to fill in cells has no way to fix anything when the numbers don't match the statement in front of them.
Most online calculators found through search results share the same limitations. They are usually built on the same PMT function with minimal customization. The spreadsheet approach gives you visibility into each step of the calculation, which is why it stays useful even years after you first build it. You can audit it, adjust it, and explain it to someone else without guessing how the answer was derived.