Building a Loan Repayment Spreadsheet That Actually Works
A decent loan repayment spreadsheet needs four core pieces of input: the principal, the annual interest rate, the term length, and the payment frequency. Everything else derives from those. The moment you add things like extra payments, variable rates, or pre-payment penalties, it gets complicated fast. Here is how I structure mine. The most common mistake people make is using Excel's PMT function and then blindly building a schedule from it without verifying the output against a manual calculation. The PMT function returns a negative number by convention, and if you do not account for that sign flip, your columns will drift apart somewhere around payment twelve. I learned that one the hard way when a client sent me a spreadsheet where the balance never actually reached zero. It was off by about $47 because of a rounding discrepancy in the interest column that compounded over sixty months.
Loan Repayment Spreadsheet Setup
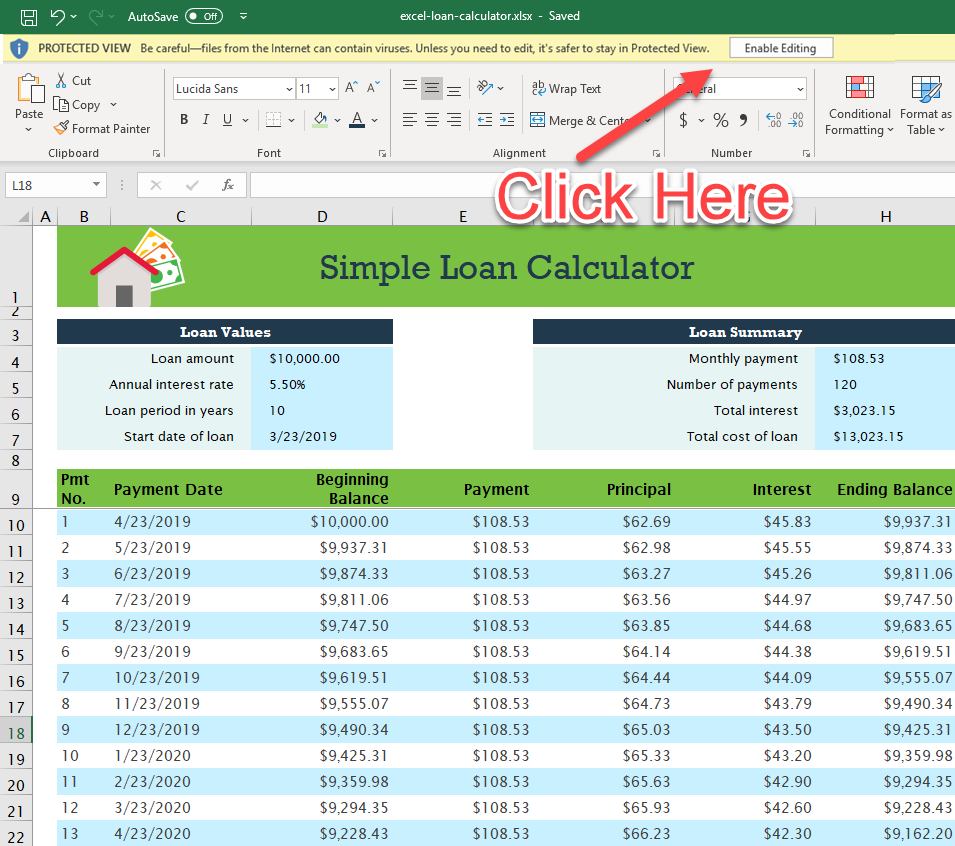
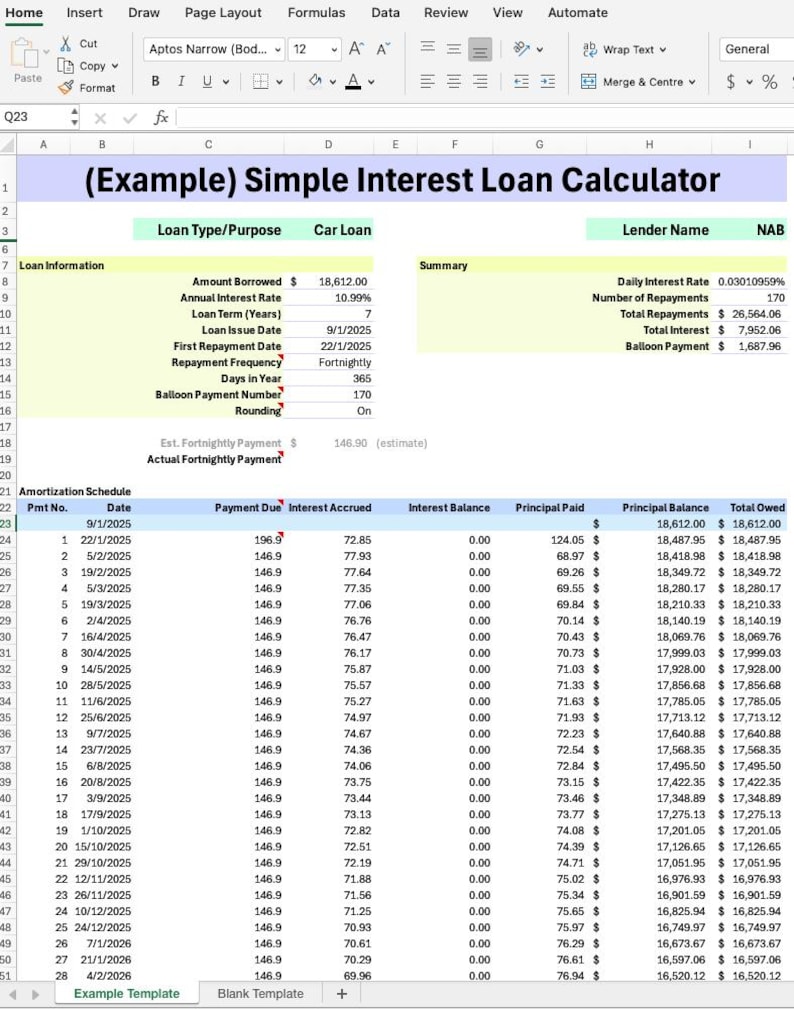
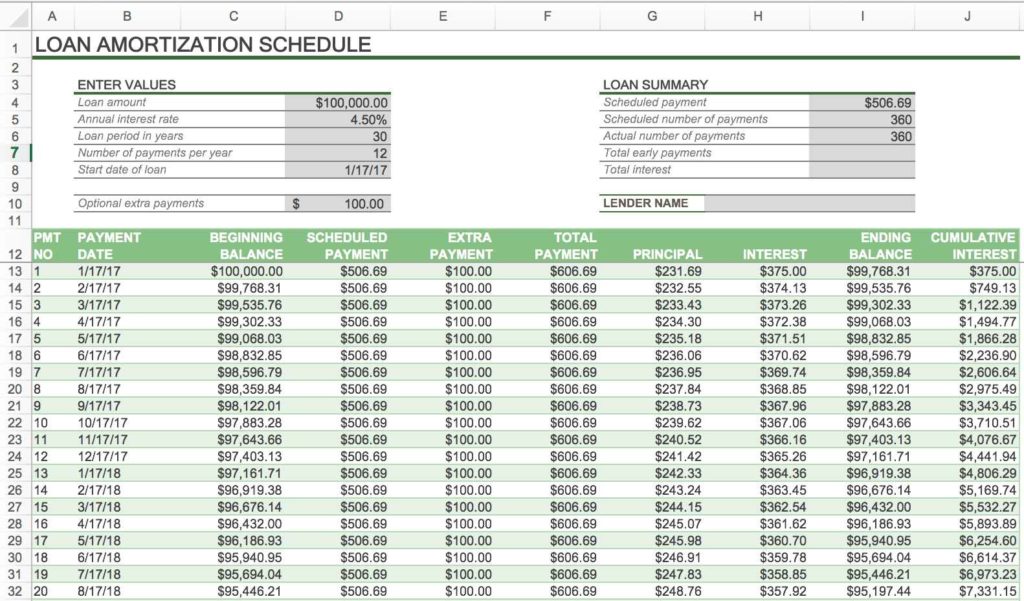
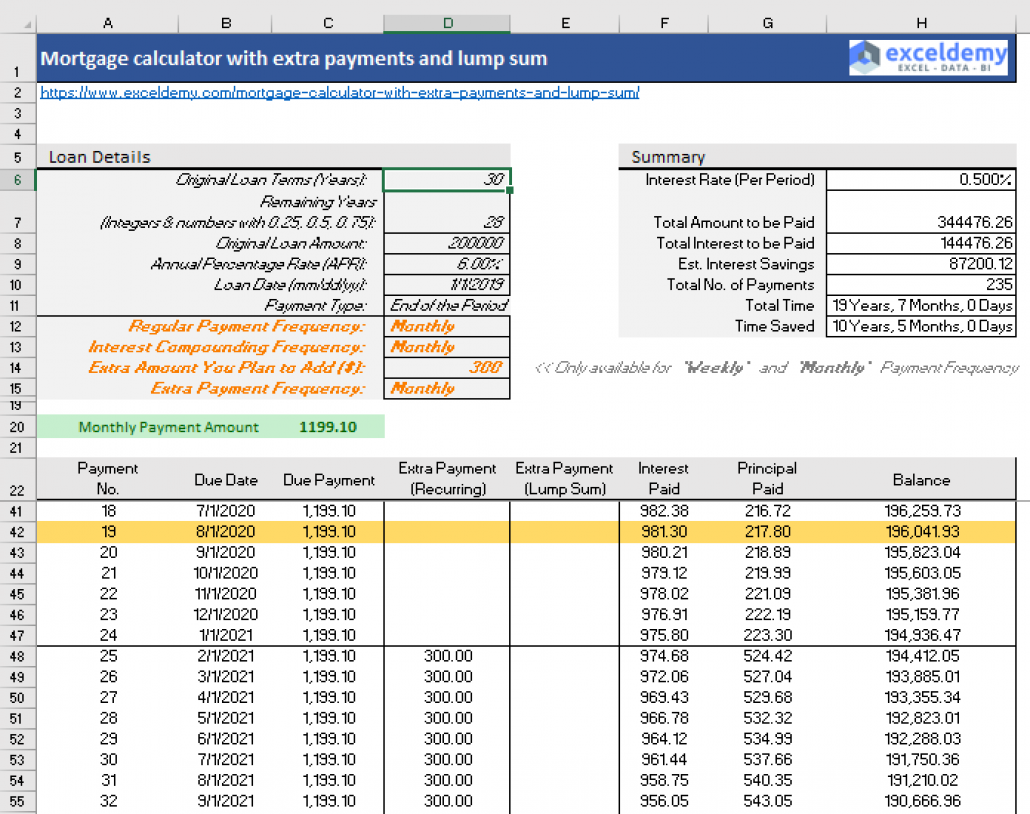
Set up your sheet with these columns in this order: Payment Number, Beginning Balance, Payment Amount, Principal Portion, Interest Portion, Ending Balance. That is it. Everything else is optional padding. Here is the exact formula structure I use. For the first payment row, your beginning balance is just the original principal. The payment amount uses the PMT function like this: =PMT(rate/periods_per_year, total_payments, -principal). The negative sign on the principal is what forces the payment to show as a positive number, which prevents confusion down the line. The interest portion for any given row is =beginning_balance*(rate/periods_per_year). The principal portion is simply =payment_amount-interest_portion. The ending balance is =beginning_balance-principal_portion. Then you drag those formulas down for however many payments the loan has. The row below the first one uses the ending balance from the row above as its beginning balance. That linking is where most spreadsheets break. People forget that the beginning balance for payment two is not the same as the principal minus one payment. It is the remaining balance after payment one has been applied. If you hardcode values instead of referencing the cell above, you will get misaligned rows and the final payment will be wrong.
Common Pitfalls and How I Fixed Them
One issue that comes up constantly is the treatment of leap years. If your loan has a February 29 and your spreadsheet assumes every month has exactly the same number of days, the amortization schedule will slowly drift. Over a thirty-year mortgage, that drift can add or subtract a full payment somewhere in year twenty. The workaround I use is to build a date column and let Excel's NETWORKDAYS or simple day-count logic handle the actual calendar. For most consumer loans with monthly payments, this does not matter much, but for commercial loans where the day-count convention is 30/360 or Actual/Actual, it absolutely does. Another thing that trips people up is partial-period payments. Say you close on a loan on the fifteenth of the month and your first payment is due thirty days later, not exactly one month out. Standard amortization formulas assume equal periods. When the first period is shorter or longer, the interest calculation changes. I built a separate section into my spreadsheets that calculates prorated interest for the first period separately, then shifts everything else by that offset. It adds about three rows and two extra formulas but it keeps the rest of the schedule clean.
Get the Full Details

When to Add Extra Payments
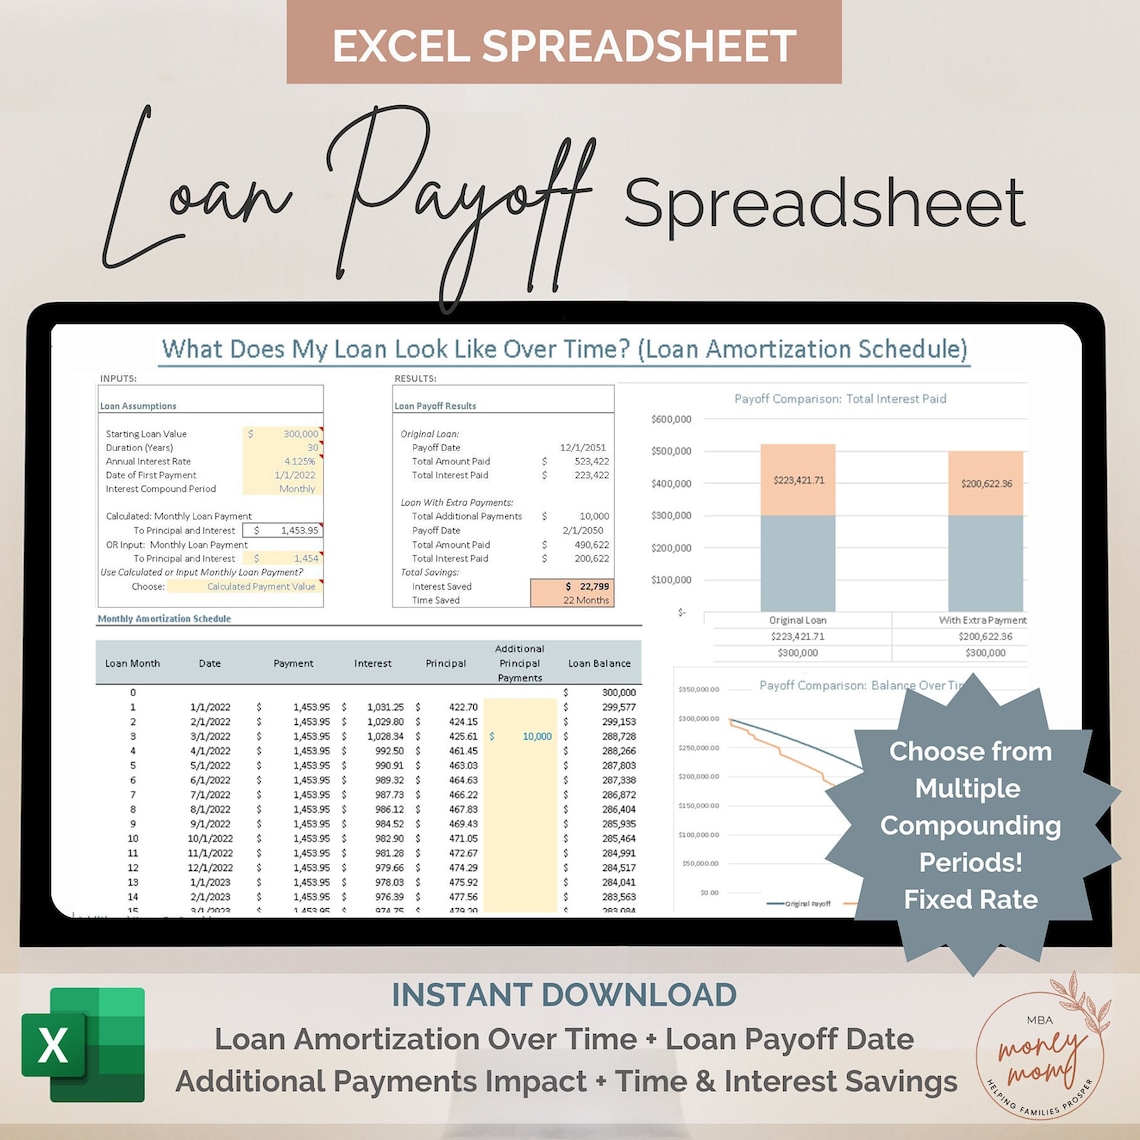
If you want to model extra payments, you have two approaches. You can create a static scenario where you add a fixed extra amount every month, or you can build a dynamic model where extra payments are entered in their own column and the schedule recalculates automatically. The static approach is simpler and faster to set up. The dynamic approach is more useful if you are modeling different paydown strategies or comparing scenarios side by side. Here is the counter-intuitive part that most people miss: paying extra toward principal does not always save you as much as you think if your loan has a pre-payment penalty or if the interest is calculated using a rebate method rather than a actuarial method. In some jurisdictions and with some loan types, additional principal payments do not reduce the interest charged in the way you would expect. I worked with a commercial borrower who was convinced that making biweekly payments would cut his payoff time significantly. It did not, because his loan agreement used a specific rebate formula that effectively neutralized the benefit of accelerated payments. Always read the loan terms before assuming the spreadsheet output matches the contract.
The Limits of a Spreadsheet Approach
A Loan Repayment Spreadsheet is useful for planning and visualization, but it has real limitations. It cannot account for changes in tax law that affect deductibility. It cannot model interest rate adjustments for ARMs without you manually updating every future period. It cannot capture hidden fees like late payment penalties or servicing charges unless you build them in explicitly. For simple fixed-rate consumer loans, a spreadsheet is usually sufficient. For commercial loans, construction loans, or any product with variable terms, you are better off using specialized software or working with a loan servicer's calculator. If you are dealing with multiple loans that interact with each other, like debt consolidation or refinancing scenarios, the spreadsheet approach becomes fragile. You end up with cross-sheet references that break easily and formulas that are impossible to debug when something goes wrong. In those cases, a dedicated financial modeling tool or even a basic database approach is more reliable than a spreadsheet.
Quick Reference for the Core Formulas
PMT formula: =PMT(rate/cycles_per_year, total_cycles, -principal) Interest portion: =beginning_balance*(rate/cycles_per_year) Principal portion: =payment- interest
Ending balance: =beginning_balance- principal_portion Next row beginning balance: =previous_row_ending_balance That last one is the single most important cell reference in the entire sheet. Get that wrong and everything downstream is garbage.
My Recommended Structure
I keep the inputs in a separate area from the amortization schedule. This way I can change the principal, rate, or term without rewriting formulas. A typical layout puts the inputs in cells B2 through B5, labeled clearly. The schedule starts at row 8 or so. Below the schedule, I add a summary section that pulls totals from the amortization table using SUMIF or simple column totals. This makes it easy to see total interest paid, total principal paid, and the payoff date at a glance without digging through fifty rows of data. The whole thing usually takes me about twenty minutes to set up from scratch once I have the template loaded. If I am doing a one-off analysis for a client, I spend another ten to fifteen minutes customizing the assumptions. That is significantly faster than trying to reverse-engineer someone else's broken spreadsheet, which is something I end up doing more often than I would like to admit.