Why Most People Use the Loan Signing Documents Cheat Sheet Wrong
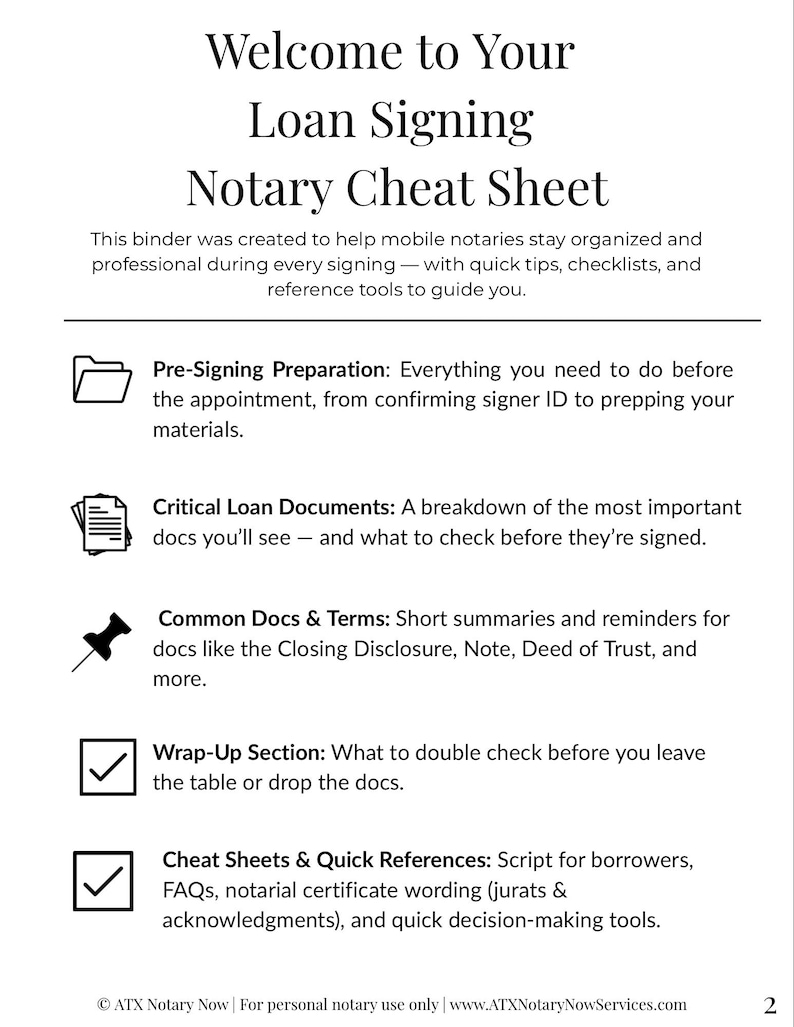
A Loan Signing Documents Cheat Sheet is essentially a quick-reference guide that lists the documents you'll encounter in a typical mortgage or refinance closing package, along with notes on who signs where, which pages need initials, and where the Notary Acknowledgment goes. Most people treat it like a checklist to memorize. That is backwards. The real value comes from using it to understand the flow of a package, not from reciting it like a script. I spent years hand-entering the document order for different states before I realized that no two states handle the same package the same way. The cheat sheet helps, but only if you use it to build mental models rather than to parrot information.
What Goes on a Loan Signing Documents Cheat Sheet
Here is what a useful version actually contains: The abbreviations matter more than most beginners realize. When a file comes in labeled "CR 7B Rider" and you have to flip through a sixty-page packet to figure out what that means, you have already lost three minutes. Learning the shorthand up front saves you from fumbling mid-signing. I do not carry the cheat sheet to every appointment. I keep it on my desk and pull it up on my second monitor while I am prepping. The workflow looks like this:
First, I scan the table of contents in the packet. Then I match each item to the cheat sheet and flag anything that looks unusual — a document I do not recognize, a signature line count that seems higher than normal, or a state-required form I do not see listed. This takes about four minutes for a standard refinance. If the package runs over eighty pages, it takes longer, but the upfront scan prevents surprise stoppages later. During the signing itself, I use the cheat sheet as a verification tool rather than a primary reference. When I reach the Notary Acknowledgment section, I confirm the wording matches the state requirement before I touch the notary seal. I check the signature block on the Promissory Note against the sheet to make sure I am not missing a co-borrower or a joint liability entry. This habit alone caught two errors in my first year that would have required me to return and re-sign three months later.
Get the Full Details

One Edge Case That Cost Me a Full Day
Early in my career I handled a cash-out refinance in North Carolina. The packet looked normal on the surface — about fifty-five pages, standard mortgage and note, everything the cheat sheet covered. I signed through it without issue and dropped it off. Two days later the title company called and said the borrower had refused to initial page forty-two because it was an arbitration addendum they had never seen before. The document was tucked in the middle of the Disclosure section, not flagged anywhere on the main checklist. The workaround I started using after that was simple but I did not think of it at the time. Before the signing appointment, I print out only the pages the borrower needs to see and place them face-up in the order they will sign. Any page not included in that visible stack gets a sticky note right on the binder. The arbitration addendum would have been impossible to miss if I had done that. Now I do it for every refinance over forty pages and for every purchase transaction regardless of size.
What the Cheat Sheet Cannot Tell You
A Loan Signing Documents Cheat Sheet does not account for lender overrides. Fannie Mae and Freddi Mac have standard documents, but individual lenders routinely add their own riders, side agreements, and modified disclosure language. When I pull a package from a regional credit union, roughly one in five packets contains at least one form that does not appear on the standard cheat sheet at all. There is no way around this except to open the file before you leave your desk and verify every page. Another limitation is the pace at which these sheets become outdated. Federal disclosure requirements change, and state laws shift every legislative session. A cheat sheet you downloaded last year may have the wrong rescission language for Texas or an incorrect homestead declaration requirement for Florida. I check mine against the latest forms every January and update whenever a new loan program I do not recognize starts appearing in my inbox. The biggest gap is that a cheat sheet cannot teach you judgment. Knowing where the borrower signs on a Deed of Trust is one thing. Knowing whether a signature block has been pre-filled with the wrong name and requiring correction before you proceed is another. I once signed a package where the first page of the Closing Disclosure had an interest rate that did not match the second page. The cheat sheet said nothing about cross-checking rates across documents. The error was caught three weeks later, and I had to fly back to the original location to re-notarize twelve pages at my own expense.
Counter-Intuitive Detail Most People Miss
Most signing agents focus heavily on the notary sections. They spend time memorizing acknowledgment wording and jurat requirements. What gets less attention is the initialing workflow. A typical refinance package requires forty to sixty separate sets of initials across borrower and co-borrower signatures. Missing one set is the most common reason documents get returned unsigned, and it happens more often than any other single error. The workaround is to use a pen to mark an "I" in the margin next to each initialing page as you complete it. Do not rely on your memory. When you reach the forty-third initialing page in a dense file, your brain will skip one. The pen mark eliminates that risk and takes approximately two seconds per page. I clocked my total time on initialing across a full package using this method, and it reduced rework from an average of eight minutes per file to zero.
When to Build Your Own Rather Than Download One
If you are new, a downloaded Loan Signing Documents Cheat Sheet is fine as a starting point. It gives you vocabulary and a basic map of the territory. Once you have completed twenty-five to thirty signings, you should start building your own version. The generic sheets include documents you will almost never see and omit the quirks that actually matter in your market. My current cheat sheet is about twelve pages and covers only the variations I encounter in the Southeast region. It took me nine months to compile, but it has saved me several hours every single week since. If you want to share it with someone else, include a note about which state forms apply and which are irrelevant. A cheat sheet that covers forty states is not useful. A cheat sheet tailored to your actual transactions is.