How to actually use a Loan To Value Calculator Heloc without getting burned
The Loan To Value Calculator Heloc is a tool that tells you how much a lender will let you borrow against your home's equity, but most people treat it like gospel and then get confused when the bank's offer doesn't match what the calculator spat out. I've been running these numbers for over a decade across conventional refinances, HELOCs, and cash-out refinancing deals, and the gap between theoretical LTV and what actually gets approved is where people get stuck. Here's the basic mechanic. You take your home's current appraised value, divide it by the outstanding mortgage balance, and multiply by 100 to get your LTV ratio. A HELOC lender typically wants to see you come in at 80% to 85% LTV for the best terms, sometimes pushing to 90% if your credit is strong. The calculator handles that division for you, but the output is only as useful as the inputs you feed it.
Loan To Value Calculator Heloc: the practical workflow
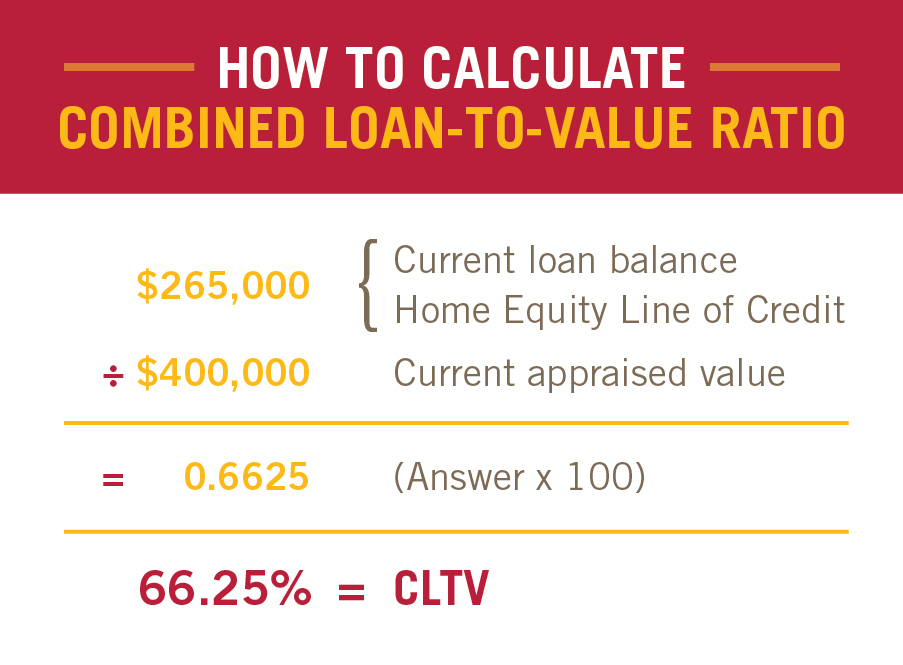
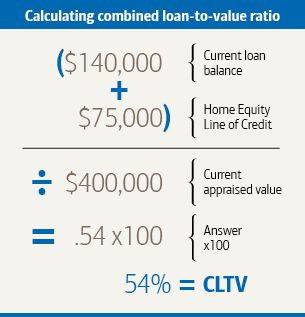
First, get a realistic current value for your property. Don't use the zestimate thing. Call a local appraiser or check recent comparable sales in your neighborhood from the last 60 days. I had a client last year who plugged in a Zillow estimate that was $40,000 over what the actual appraisal came in at. His calculated HELOC limit looked generous until the formal appraisal hit, and suddenly his borrowing capacity dropped by roughly $20,000. The calculator didn't lie, but the input was wrong. Next, factor in your existing mortgage balance including any second liens. If you have a first mortgage and a previous home equity line already on the property, the combined LTV matters more than the individual numbers. Most lenders cap combined LTV at 85% to 90% for HELOCs. Run the combined figure through a Loan To Value Calculator Heloc tool before you apply so you know what you're working with. Then there's the lender-specific overlay. Two banks can give you completely different HELOC amounts on the same property with the same credit score. One might use a 90% combined LTV cutoff while the other stops at 80%. This is where the calculator becomes a starting point rather than a destination.
The trick most people miss is the draw period pricing structure. A HELOC isn't just about how much you can pull out. It's about the interest-only period, the variable rate tied to the prime index, and whether the lender uses a rolling or fixed draw period. I've seen borrowers who maxed out their calculated HELOC amount only to find the rate was 2.75 points above prime with a 5-year draw period instead of the standard 10. The LTV number looked fine on paper, but the product terms made the deal expensive fast. Another edge case that bites people regularly is the lender's valuation methodology. Some use automated valuation models that can lag the market by several months, especially in areas with rapid price shifts. During the 2022 to 2023 correction in certain markets, I watched AVM-based HELOC offers come in 10 to 15% below what manual appraisals supported because the algorithm hadn't caught up yet. If your calculated LTV looks suspiciously high compared to what the lender is offering, request a manual appraisal rather than accepting the AVM number. When you're actually filling out the calculator, make sure you're using the full market value, not the assessable value your tax bill shows. Those two numbers diverge significantly in almost every jurisdiction. In my experience, using the tax assessed value instead of market value skews the LTV downward by 15 to 25%, making your borrowing capacity look much better than it actually is.
Get the Full Details
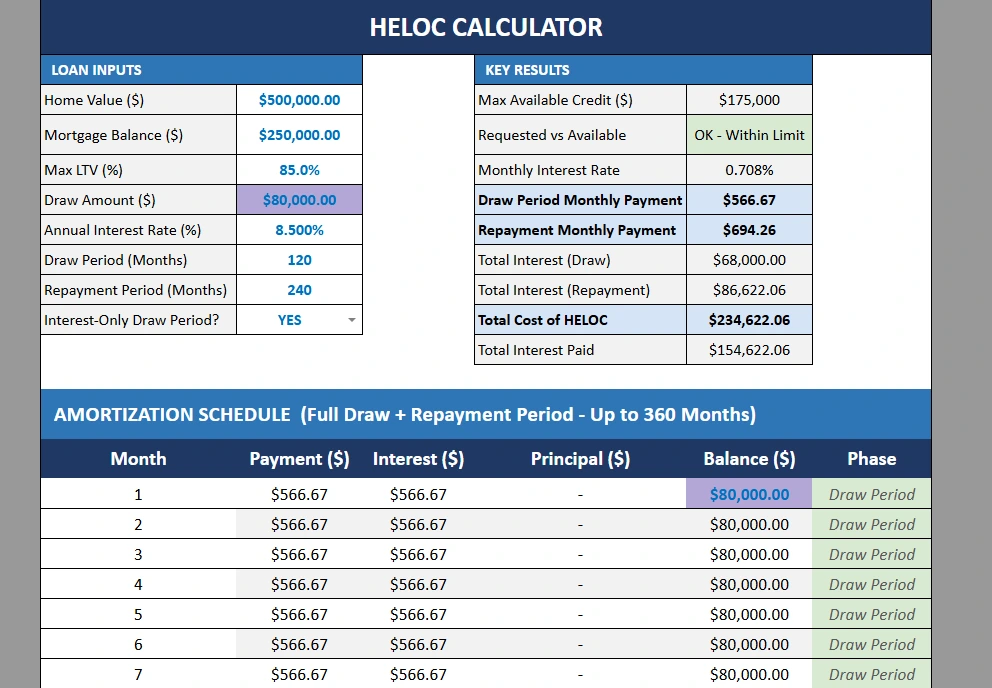
The calculator also doesn't account for debt-to-income constraints on the backend. A lender might approve a $150,000 HELOC based on LTV alone, but if your monthly obligations are already near the 43% DTI threshold, they'll cut the amount or deny it entirely. Run the LTV calculation first, then immediately run a separate DTI check with the projected HELOC payment factored in as a minimum of 5% of the line or the actual minimum payment, whichever is higher. For the actual tool, I recommend using a dedicated LTV calculator rather than a generic one. The difference is that purpose-built calculators often include fields for first lien balance, second lien balance, and combined LTV output. Generic calculators usually just handle a single mortgage balance and miss the second lien entirely. A quick search for a dedicated Loan To Value Calculator Heloc will surface options built specifically for home equity products. Here's what the calculation looks like in practice. Your home appraises at $400,000. Your first mortgage balance is $250,000. You have no second lien. That's a 62.5% LTV, which puts you well within most HELOC thresholds. At 85% combined LTV, your maximum total lending would be $340,000. Subtract the $250,000 first mortgage, and you have roughly $90,000 in available HELOC capacity before any lender overlays or credit adjustments.
If you add a $30,000 second mortgage, the math changes quickly. Your combined debt becomes $280,000 against the $400,000 value, which is 70% LTV. You now have $60,000 of headroom before hitting the 85% ceiling instead of $90,000. That's a $30,000 difference from a single second lien, and it's exactly the kind of detail that trips people up when they're planning renovation budgets or debt consolidation strategies. The main limitation of any LTV calculator for HELOC purposes is that it only shows you the top-line number. It doesn't capture credit score impacts, employment verification requirements, reserve account mandates, or the fact that some lenders will reduce your approved amount by 10 to 20% just to maintain a buffer during rate resets. I always tell clients to treat the calculator output as a pre-qualification estimate, not a commitment letter. The actual approval can differ substantially depending on underwriting standards at the time of application. If your situation involves non-traditional income, self-employment, or a property type that some lenders flag as higher risk like a condo in a mixed-use building, the calculator becomes even less reliable. Those scenarios require manual underwriting discretion that no automated tool can simulate. In those cases, skip the calculator exercise and go straight to a loan officer who can run a full credit and income review with the specific lenders you're targeting.
For most standard Situations with a conventional owner-occupied single-family home and a clean credit profile, the Loan To Value Calculator Heloc process takes about 10 to 15 minutes and gives you a reasonable ball park before you start shopping lenders. Just make sure your inputs are accurate, account for all existing liens, and understand that the final number on the page is the floor, not the ceiling, of what you might actually get approved for.