How to Actually Draw and Read the Loanable Fund Market Graph
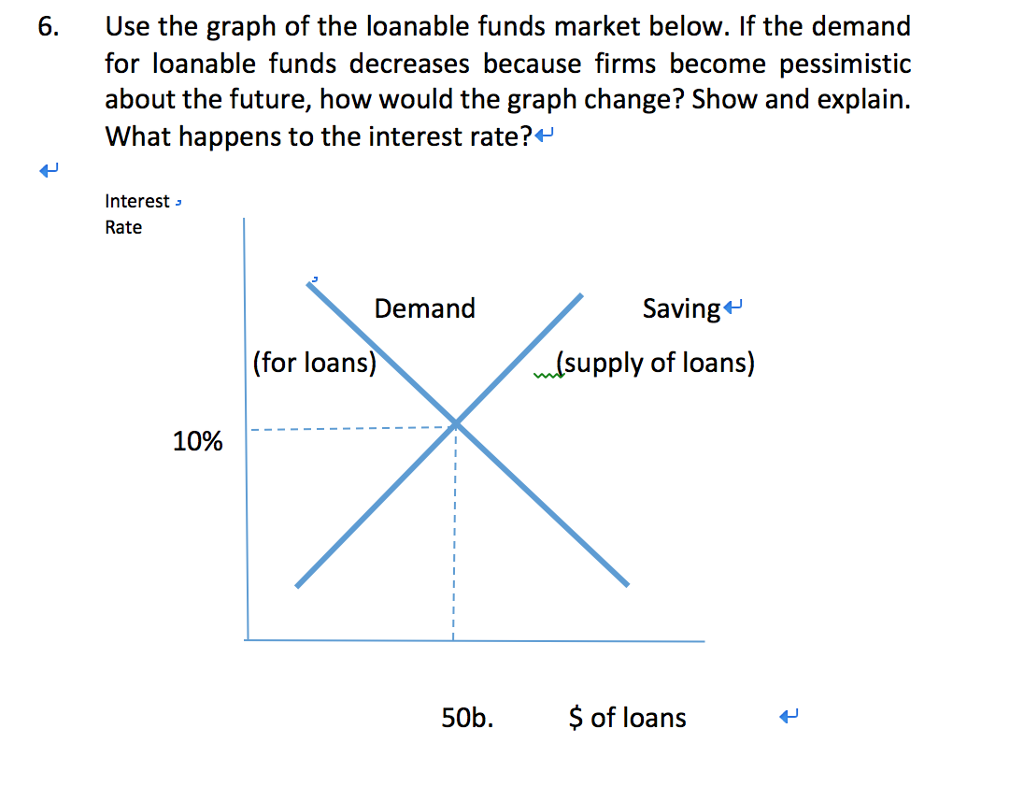
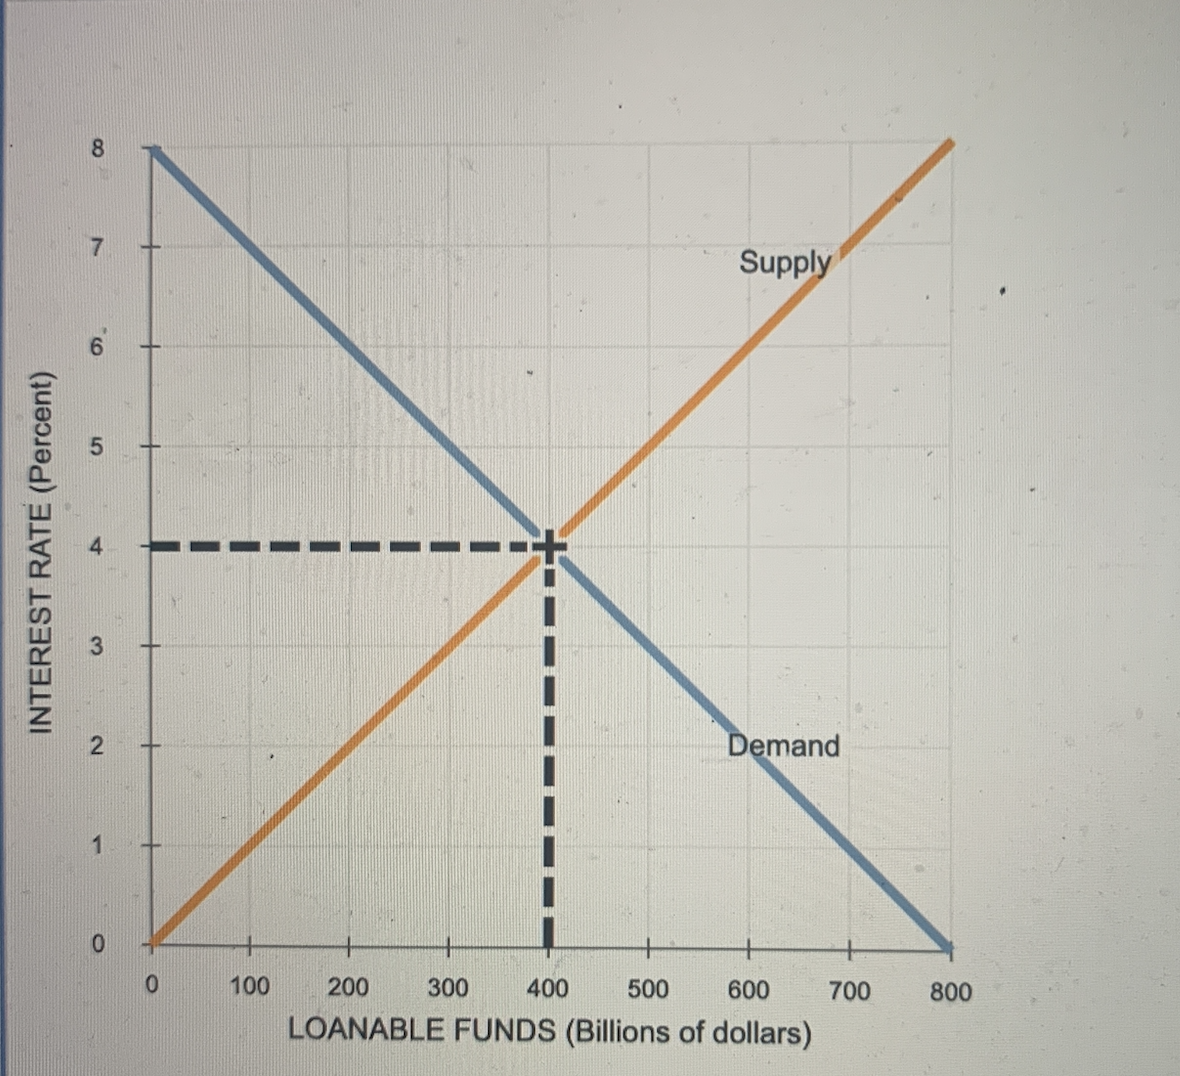
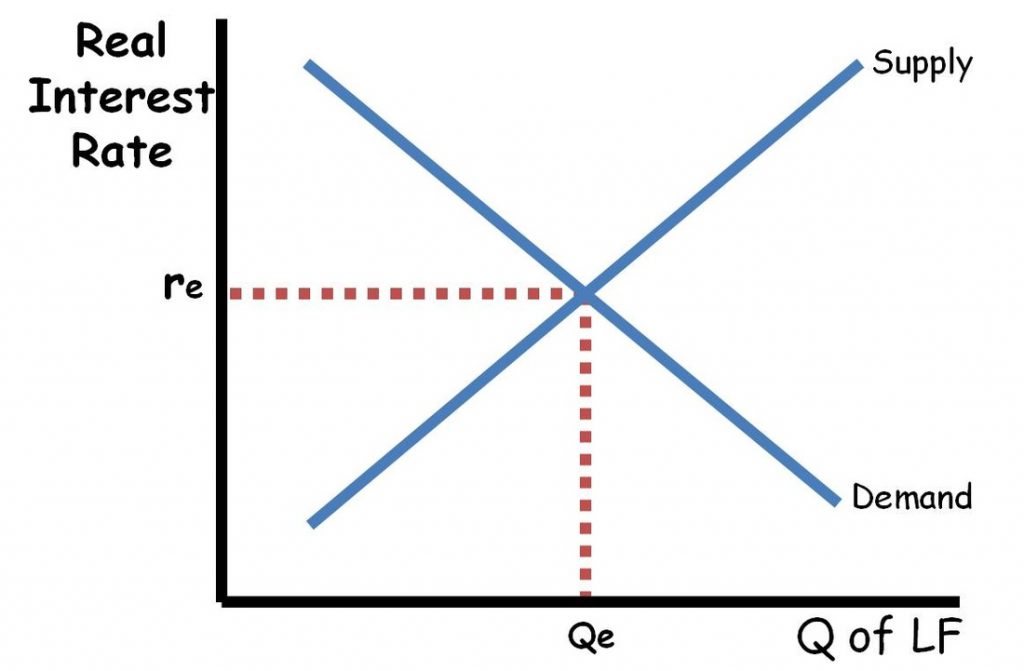
Most people mess this up on their first try because they treat it like any other supply-and-demand diagram. It isn't. The axes are different, the shifts are backwards from what your intuition says, and if you don't understand what's actually moving, you'll draw it wrong every time. The Loanable Fund Market Graph plots the real interest rate on the vertical axis and the quantity of loanable funds on the horizontal axis. The demand curve slopes downward because when real rates are lower, more borrowers want to take out money for investment. The supply curve slopes upward because lenders are willing to put more funds into the market when they can earn a higher real return. That part is standard. The confusing bit is everything else.
What the Loanable Fund Market Graph Actually Shows You
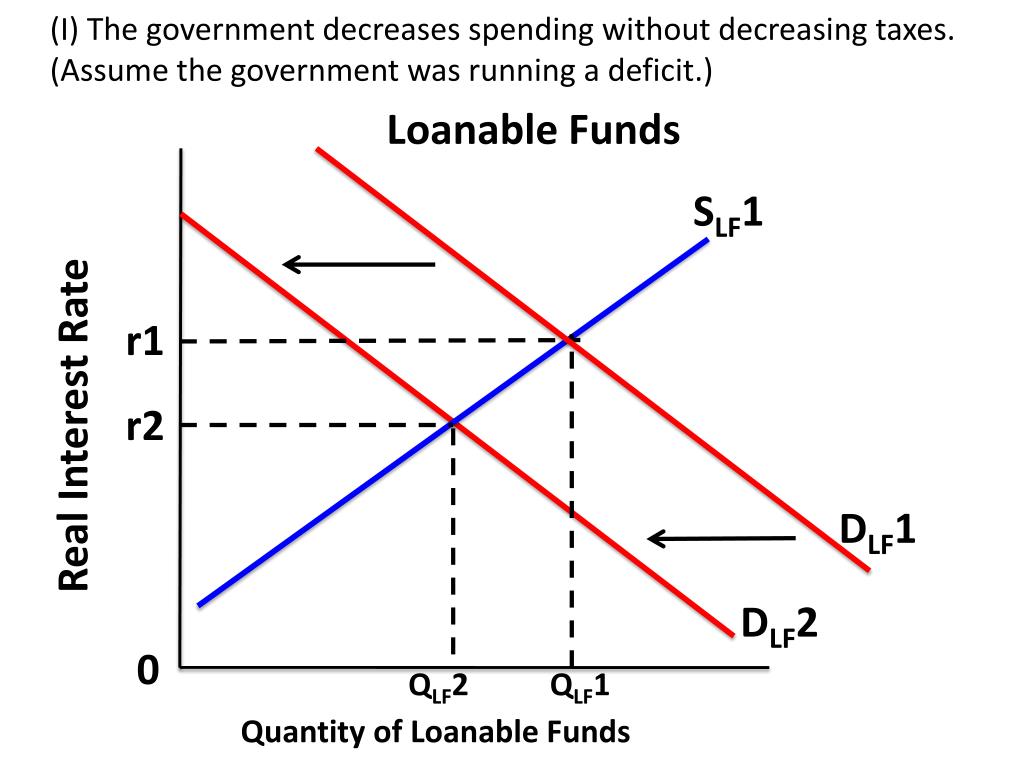
I keep running into students and junior analysts who conflate the loanable funds market with the money market. They're related but not identical. The money market deals with the nominal money supply and central bank policy. The loanable funds market deals with real savings and real borrowing across the whole economy. When the Fed changes the money supply, it affects the loanable fund graph indirectly through expectations and actual saving behavior. But those are separate mechanisms. Drawing them as if one directly shifts the other will get you the wrong equilibrium. Here's a practical rule I use: the demand for loanable funds comes from three sources. Private investment by firms and households. Government borrowing when there's a deficit. Net foreign borrowing when capital is flowing in. The supply side is national saving, which is private saving plus public saving. Public saving is basically tax revenue minus government spending. When the government runs a larger deficit, public saving goes down. That shifts the supply curve to the left. Higher real interest rates. Less total investment. This is the classic crowding-out effect, and it's not controversial but it's routinely misdrawn.
How to Draw It Without Making Basic Mistakes
Start by labeling the axes correctly. Real interest rate, not nominal. Quantity of loanable funds, not just money. Then draw the initial supply and demand curves intersecting at an equilibrium point. Label it E1 with the corresponding real rate r1 and quantity Q1. Don't skip labels. People skip labels and then spend twenty minutes later trying to remember which curve was which. Now apply a shift. Let's say there's a broad tax incentive for private investment, like an accelerated depreciation rule. That increases the demand for loanable funds because firms want to borrow more to buy capital. The demand curve shifts right. The new equilibrium E2 has a higher real rate r2 and a higher quantity Q2. But here's the thing most people miss: the higher interest rate partially crowds out some private investment that wasn't shielded by the tax incentive. The quantity of funds demanded does rise overall, but not as much as the initial demand shift would suggest if you ignored the movement along the supply curve. Another common shift involves national saving. If households decide to save more because they're worried about a recession, the supply curve shifts right. The real interest rate falls. Investment increases. This is the paradox of thrift playing out in the loanable funds framework. The paradox is that individual rationality leads to a collective outcome that's actually beneficial for investment, though aggregate demand may fall for other reasons. That nuance matters when you're interpreting what the graph is telling you.
Get the Full Details
The Edge Case I Keep Encountering
Last year I was working with a dataset that had simultaneous government deficit expansion and a surge in household saving. The textbook prediction is ambiguous for the equilibrium quantity of loanable funds. The deficit shifts supply left, pushing rates up. The saving surge shifts supply right, pushing rates down. The net effect on quantity depends on which shift is larger. On paper this is straightforward. In practice the data was messy and the shifts overlapped across multiple quarters. My workaround was to separate the two effects by time period. I used quarterly data and flagged the months where the deficit change occurred without a significant change in the personal saving rate, and vice versa. That let me isolate the supply-side shifts and estimate their relative magnitudes. The deficit effect dominated in that specific case, so the equilibrium real rate ended up higher than the starting point despite the increase in household saving. Without the temporal separation, the graph would have been impossible to interpret cleanly. You can do the same thing with any overlapping shift scenario by identifying which variable moved first and holding others constant in your analysis.
Where the Graph Fails Completely
The Loanable Fund Market Graph breaks down in open economies with highly mobile capital. When a country can borrow freely from abroad, the domestic supply of loanable funds isn't constrained by national saving alone. Foreign capital inflows effectively add to the supply. The standard graph doesn't capture that without modification. You'd need to treat the supply curve as more elastic or add a separate component for net capital inflows. Ignoring this leads to wildly incorrect predictions about what happens when a small open economy runs a fiscal deficit. Another limitation: the graph assumes a single real interest rate for all borrowers. In reality, different borrowers face different rates based on credit risk. Firms with low credit ratings pay significantly more than AAA-rated entities. The graph abstracts this away, which is fine for macro-level analysis but misleading if you're trying to predict how a policy change affects specific sectors. The graph also assumes that saving and investment decisions respond to the real rate in a relatively stable way. During liquidity traps or periods of extreme uncertainty, that relationship weakens considerably. Saving might not increase much when rates fall because people are deleveraging. Investment might not increase much either because firms aren't confident about future demand. The graph becomes almost useless in those situations. If you need to model those conditions, you're better off using a IS-LM framework or a dynamic stochastic general equilibrium model. Those are more complex but they handle the behavioral anomalies that the loanable funds diagram smooths over. I usually recommend the loanable fund graph for introductory and intermediate analysis, then switch frameworks once the student or analyst is comfortable with the basics.
Practical Tips for Working With the Graph
Always specify whether you're analyzing a closed or open economy before drawing anything. The difference changes which curves shift and by how much. Closed economy assumes no capital flows. Open economy introduces the world real interest rate as a potential anchor. If the domestic rate tries to move above the world rate, capital flows in and the supply curve becomes effectively horizontal at that world rate up to a point. When interpreting shifts, distinguish between a movement along a curve and an actual shift of the curve. A change in the real interest rate causes movement along the curve. A change in underlying factors like taxes, consumer confidence, or government spending shifts the curve. People mix these up constantly. Writing down what factor caused the change before you draw the shift will prevent most errors. Check your equilibrium against what you know about the real economy. If your graph shows a massive increase in investment following a modest policy change, something is likely wrong. The typical elasticity of investment with respect to the real interest rate is somewhere between negative 0.3 and negative 0.8 in most empirical estimates. If your drawn shift implies a much larger response, recalibrate. The graph is a qualitative tool first and a quantitative one second. Don't pretend it gives precise numerical predictions unless you've calibrated it with actual data.