The Weekly Finance Logbook That Actually Sticks
Most people abandon their finance tracking within three weeks because they set the bar too high. They try to track every coffee purchase and categorize it to the nearest cent while also rebalancing their portfolio and doing tax planning, all on Sunday night. That is not a system. That is a recipe for burnout. I ended up building my own Logbook For Finance Weekly after spending about eight months bouncing between spreadsheets, bullet journals, and every budgeting app on the market. The problem with the apps is they automate the wrong things. They sync your transactions, sure, but they don't help you see what is actually happening with your money across accounts in a way that surfaces decisions you need to make. A spreadsheet gives you control but demands constant maintenance. A physical notebook is fast but impossible to analyze later.
What a Weekly Finance Logbook Actually Is
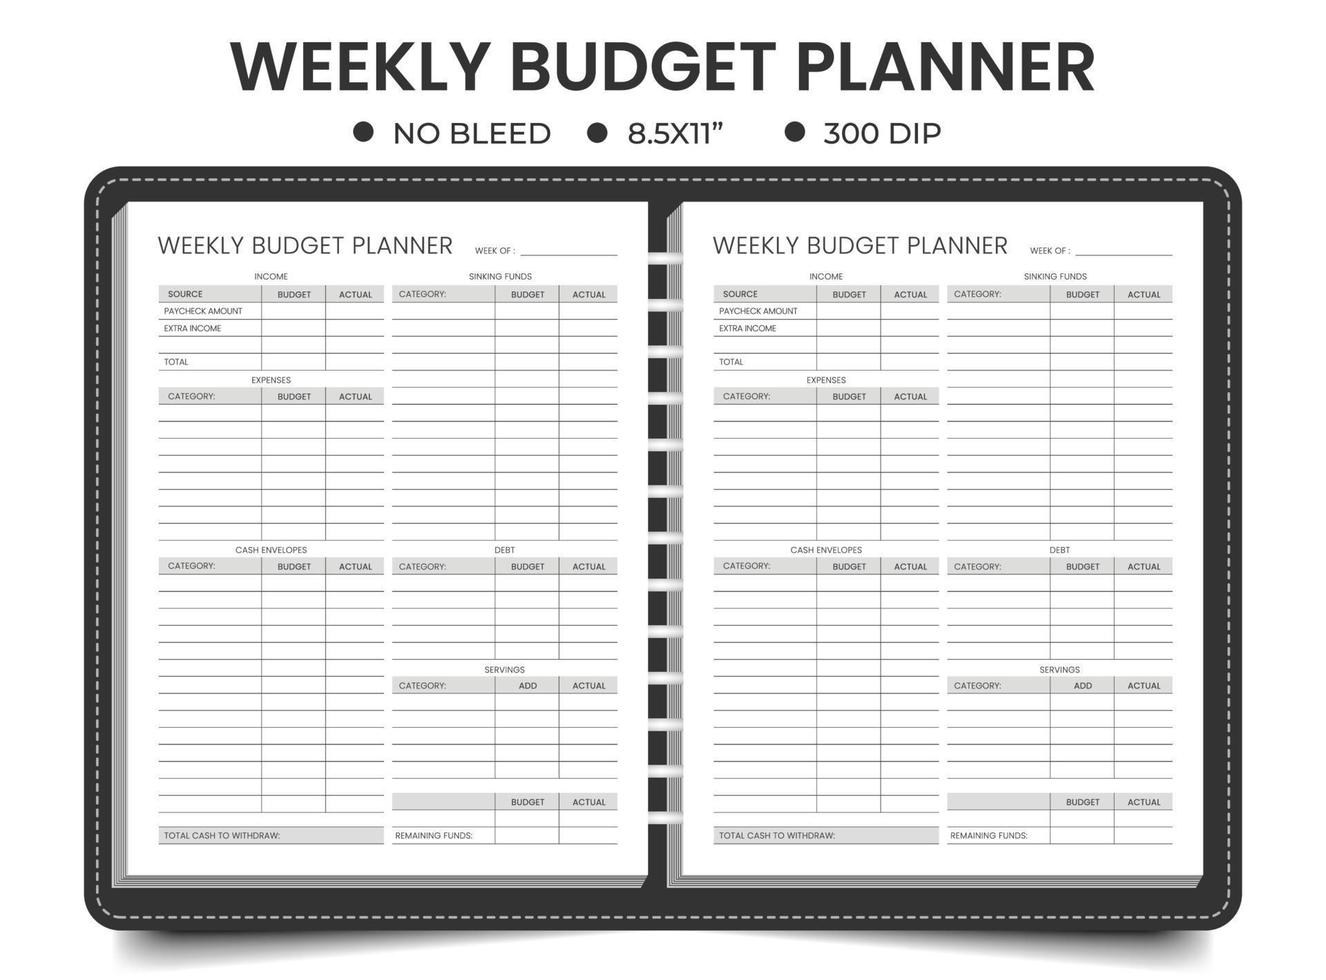
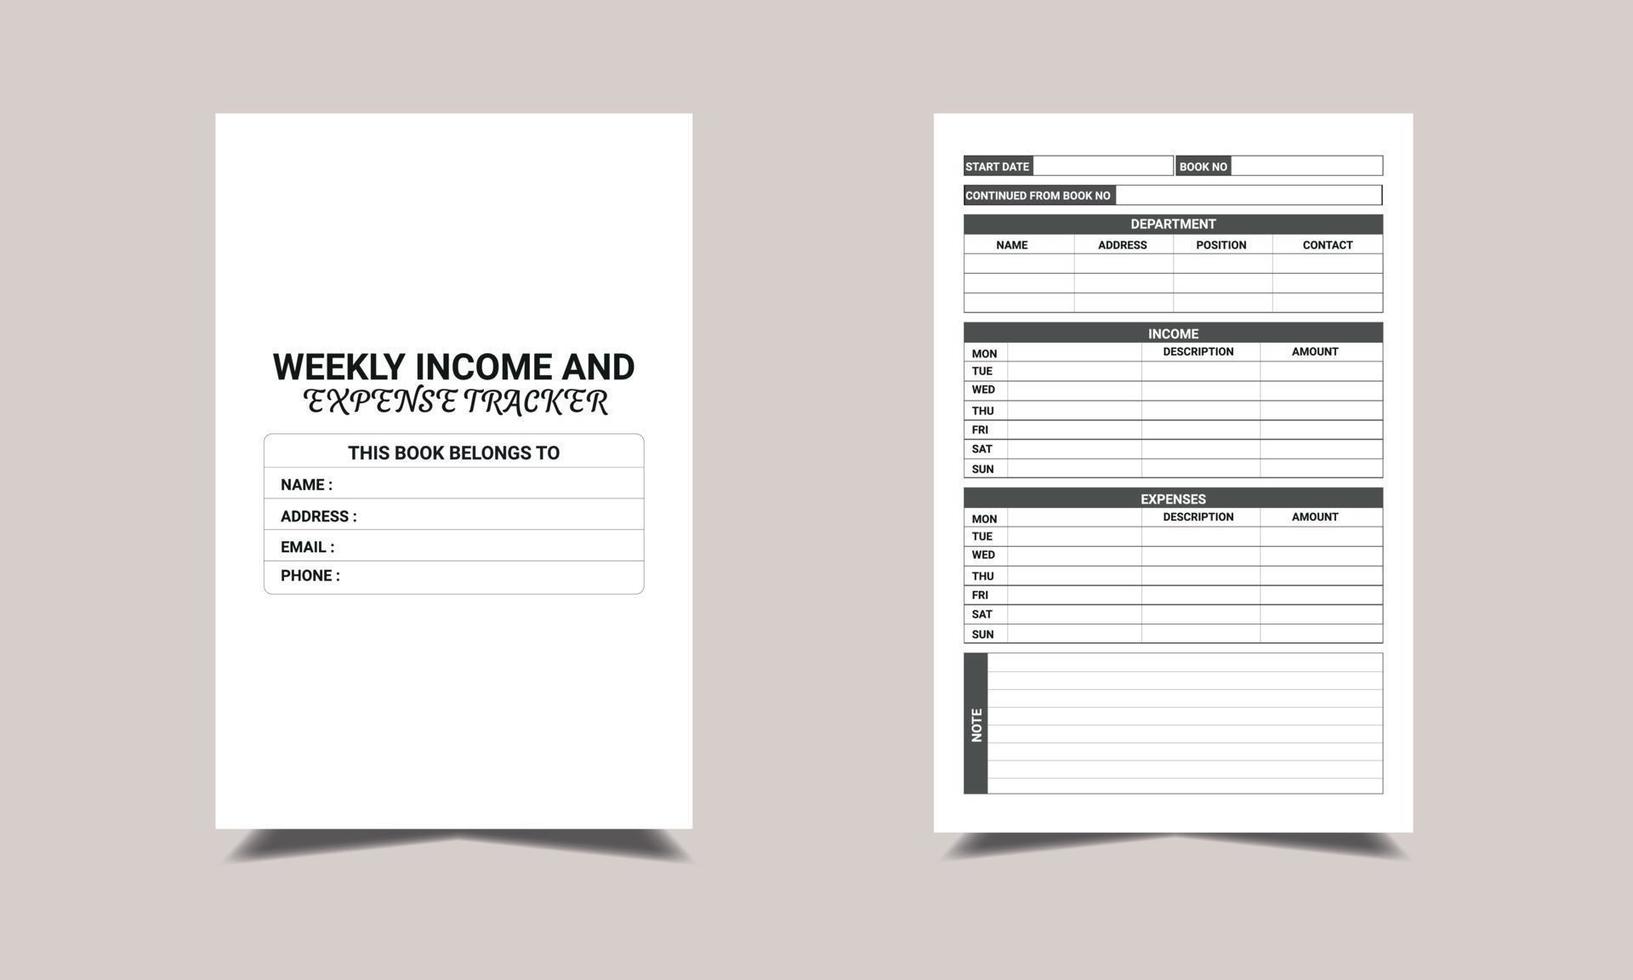
A weekly finance logbook is a structured record you update once per week that captures your financial position, cash flow, and key movements in about 20 to 40 minutes. That is the target window. If you are spending longer than that, you have built in unnecessary complexity. The core components are straightforward. You record your starting balances across checking, savings, and investment accounts. You log incoming income. You log outgoing expenses, grouped into broad categories rather than granular ones. You note any debt payments. You check your investment allocations against your target. And you write down the one or two financial decisions you need to make before the following week. The last part is the piece everyone skips. The decision capture line. Without it, your logbook becomes just a pretty archive of data you will never look at again.
How I Build My Weekly Logbook
My setup is a simple Google Sheet, but the logic applies to any medium. I have a single tab for the current week and reference tabs for each account. Every Sunday evening, I open my banking apps and investment platforms and fill in the numbers. I do not try to reconstruct every transaction from memory. I pull screenshots or export mini-statements if needed, then move on. The category system is deliberately thin. I use maybe six to eight categories max for expenses. Essentials, Discretionary, Debt Payments, Investments, Health, Transport, Entertainment, Other. That is it. When I first started, I was using something like forty categories because I thought precision meant accuracy. It does not. Precision is about having enough signal to make decisions. Forty categories just makes the weekly review take an hour and a half. I keep a running net worth column on the side. Week over week, it shows whether I am moving in the right direction. Not by much. A few hundred dollars month to month is normal. But seeing the trend line matters more than any single week.
Get the Full Details

The Counter-Intuitive Part Most People Miss
Here is something nobody tells you about weekly finance logbooks. The entries you skip matter more than the entries you make. If your system requires you to track every small expense, you will eventually stop. So leave out the predictable stuff. Your Netflix subscription, your gym membership, your recurring transit pass. Log those as flat amounts once and move on. Track the stuff that varies. Groceries. Utilities. Gas. Discretionary spending. That is where the actual behavior lives. Another thing. Do not try to reconcile every transaction in the logbook itself. Let your bank statement handle reconciliation. The logbook is for trend tracking and decision making, not audit work. Trying to make the logbook balance to the penny every week will kill the habit before it starts.
A Specific Problem I Ran Into
Last year I hit a wall with a shared account situation. My partner and I both had access to a joint checking account, and every time I logged an expense, I had no way to know if they had already recorded it or if I was double counting. I was manually checking transaction histories against my log entries, which added twenty minutes to each weekly session. I almost quit over that. The fix was simpler than I expected. I stopped trying to log from the joint account entirely. Each of us logs from our own individual accounts and contributions only. The joint account gets a single weekly entry for its current balance, treated like any other asset. I add our individual net worth figures together afterward if I want a combined number. The weekly logbook stayed under thirty minutes again.
Download Option
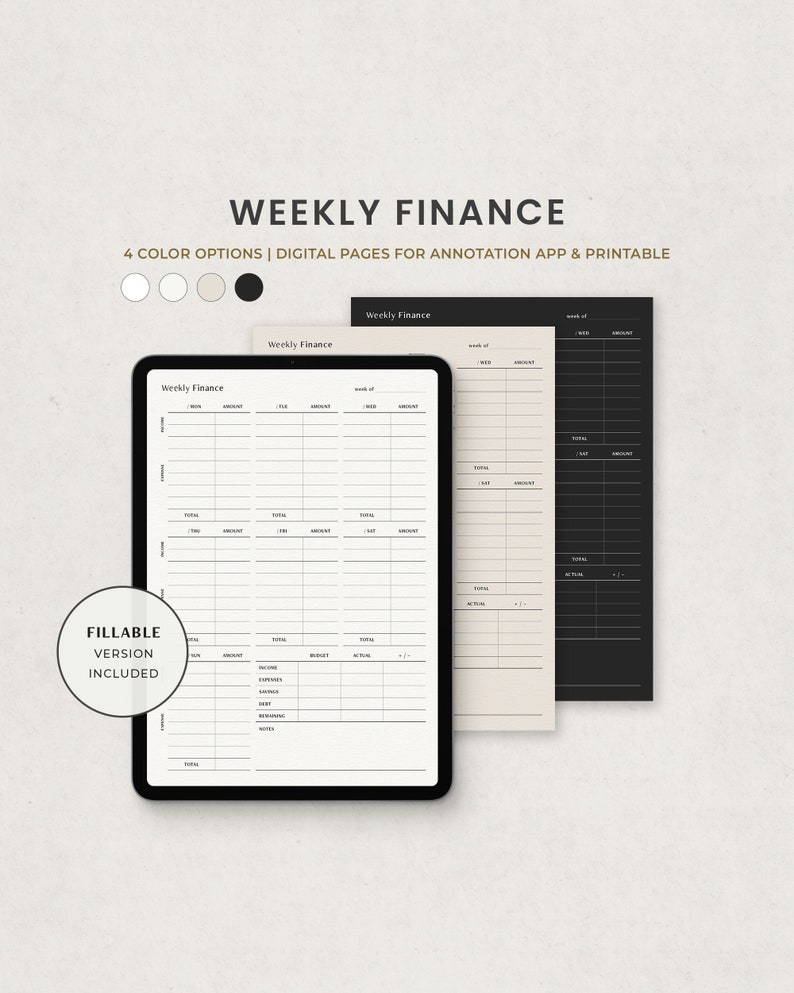
If you want a starting point instead of building from scratch, there is a free Logbook For Finance Weekly template available that follows this same lightweight structure. It covers the account balance section, the income and expense log, the decision line, and a rolling net worth column. You can find it linked in the resource section below. Import it into Google Sheets or Excel and adjust the account names to match your own setup. Be honest about when a weekly logbook is the wrong tool. If you carry high-interest debt and need aggressive payoff tracking, a weekly cadence is too slow. You should be looking at biweekly or even daily tracking until that debt is under control. If you are a freelancer with variable income and irregular expense timing, a weekly framework will blur the picture. Monthly or even project-based tracking tends to work better there. And if you simply cannot commit twenty minutes a week, no template in the world will fix that. Consider switching to a monthly logbook instead. One comprehensive session per month is legitimate and often more sustainable for people who already manage money for a living during the week.
The point is not to build the most detailed system possible. It is to build the simplest system that still gives you enough information to feel in control and actually stick with it past the first month. That is what I keep coming back to after trying everything else.