Getting the LRAS curve right in a macro model
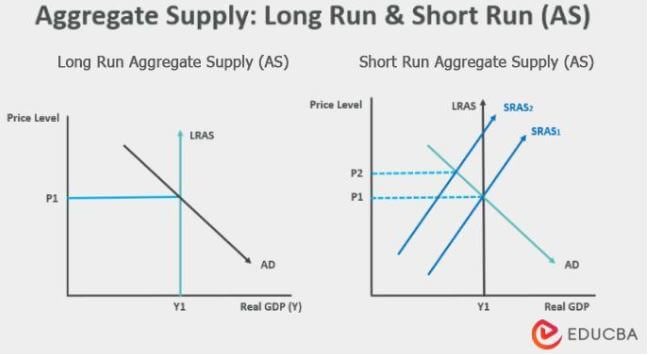
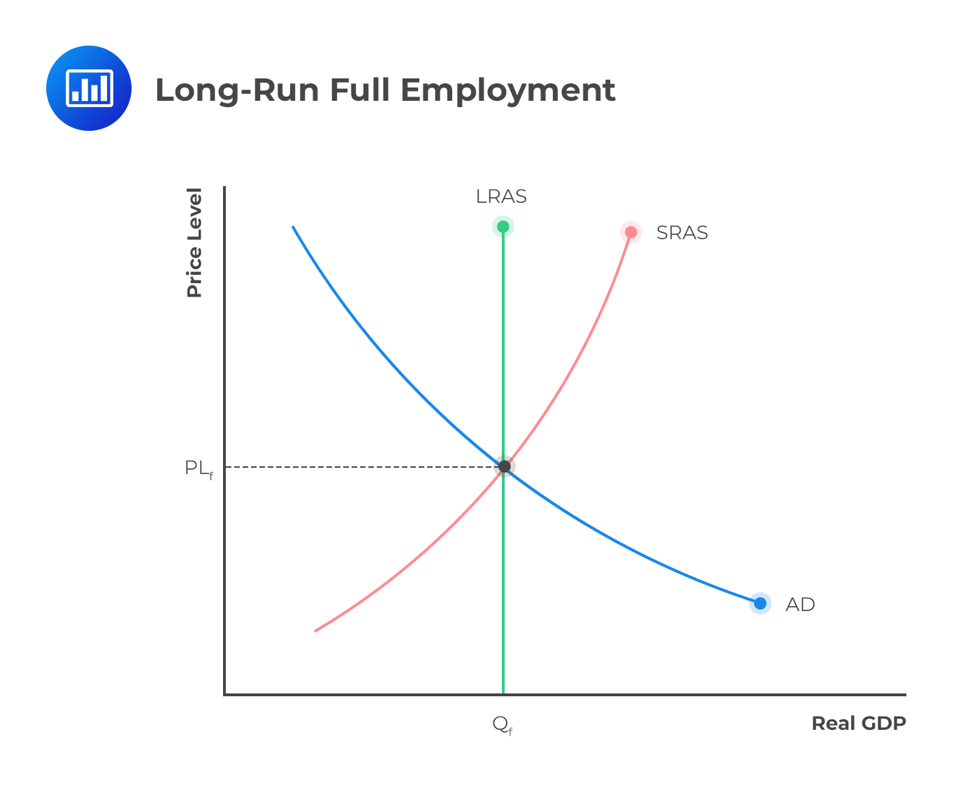
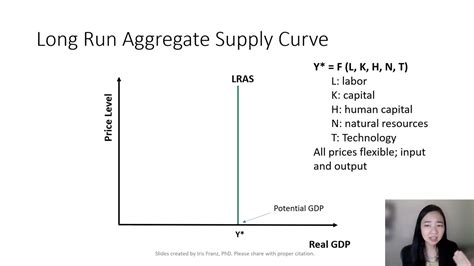
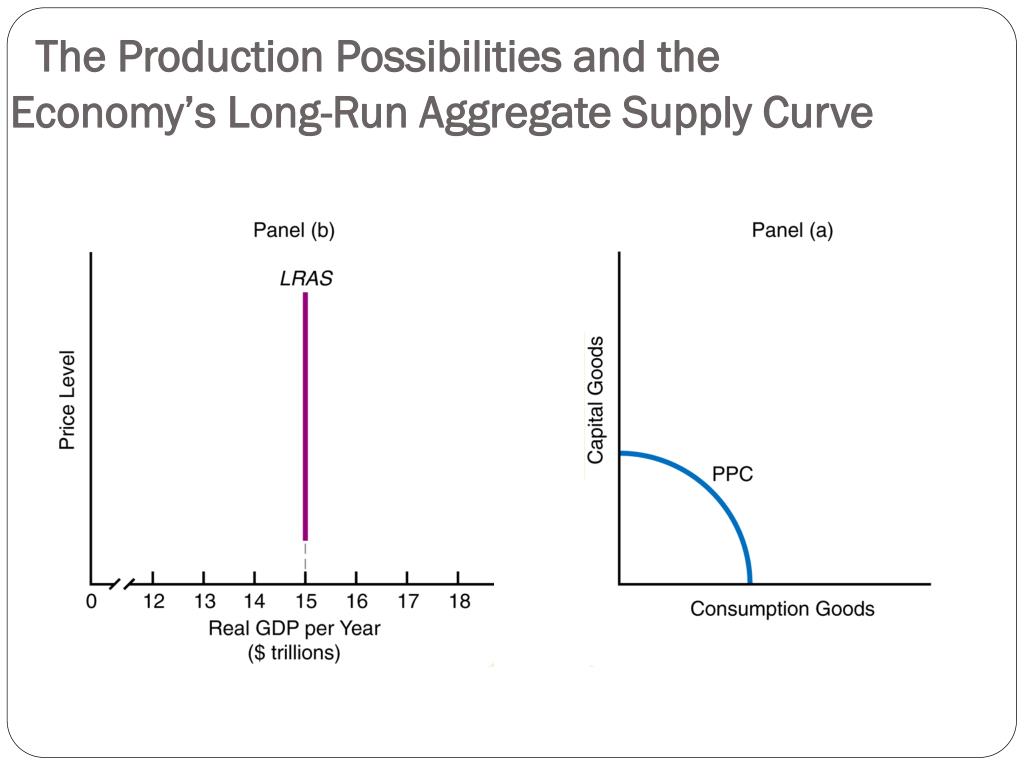
The long run aggregate supply curve is vertical at potential output. That part everyone knows from the textbook. The thing nobody tells you is that "potential output" is not a fixed number you can just look up. It's an estimate you calculate, and when it's wrong your entire equilibrium analysis goes sideways. I build this curve by starting with the production function: Y = A × F(K, L). You need current capital stock, total factor productivity, and the natural rate of employment. The vertical line sits at whatever Y comes out to. Price level changes don't move it because in the long run, wages and prices adjust fully. Here's where it gets messy. I was modeling a small open economy once and kept getting weird results. AD shifts looked like they were moving along the LRAS with no short-run effect at all. Turns out I had plugged in an outdated capital stock figure from three years prior. The economy had expanded its capital base significantly but my potential output estimate was stale. It made the LRAS sit far too far to the left. When actual GDP caught up to the outdated estimate, the short-run curve disappeared entirely. I recalculated K using the perpetual inventory method with actual investment data and the model behaved normally again. Takes about 20 minutes if your data is clean, longer if you're scraping it from annual reports.
The shortcut most people use is just taking last year's GDP and calling it potential. Don't do that. Use the output gap from your central bank or IMF estimates if available. If you're working with a country that doesn't publish those, run a HP filter on trend GDP. It's approximate but usually within three to five percent of the true value.
What actually determines the position
Three things shift the LRAS: technology, capital stock, and the natural rate of unemployment. Any change in these moves the vertical line left or right. Money supply changes do not. Wage adjustments do not. Only real factors matter here. That's the whole point of the distinction from the short-run curve. I've seen people try to incorporate exchange rate movements directly into LRAS calculations. That's incorrect for closed-economy models, and even in open economies you'd handle that through net exports in the AD component, not by shifting the supply curve. You'll get cleaner models if you keep the channels separate. One counter-intuitive thing that trips people up: an increase in the saving rate shifts LRAS to the right, but only after the capital accumulation period. In the transition, output might actually dip before rising. If your model runs on a steady-state framework you can skip that, but if you're doing transitional dynamics the timing matters and you should show it explicitly.
Get the Full Details

Pitfalls I see constantly
Students and junior analysts routinely confuse the movement along the SRAS with a shift of the LRAS. A change in input prices shifts the short-run curve. A change in productive capacity shifts the long-run curve. They are not the same mechanism. I've corrected this exact mistake in review sessions probably two dozen times. Another thing: the LRAS assumes full price flexibility. In reality, nominal rigidities persist for years in some economies. This means the vertical curve is more of a long-term anchor than a description of any specific period. When you're modeling a recession that lasts four years, treating the LRAS as if the economy snaps back to it immediately gives you misleading predictions. Add a hysteresis component if the episode is prolonged. Lost human capital and degraded capital stock can permanently lower potential output, and your model should reflect that. The biggest limitation of this framework is that it tells you nothing about the path to equilibrium. It gives you the destination but not the journey. If you need to understand adjustment dynamics, you have to layer on the short-run aggregate supply curve, expectational errors, and wage-setting behavior. The LRAS by itself is a static snapshot.
When I need a quick working estimate for a model, I pull trend GDP from the World Bank's dataset or calculate it from national accounts using a simple growth-trend approach. Files are usually in Excel or CSV format. Takes less than ten minutes to import into whatever modeling environment you're using.
When the LRAS breaks down
Supply-side shocks that permanently alter the production function shift the curve. Think oil price crises that restructure the entire economy, or major technological disruptions. The curve doesn't just move; the shape and slope assumptions underlying the model may no longer hold. I've seen models fail because someone applied the same LRAS position after a structural regime change without recalibrating. If you're working with an economy undergoing rapid demographic transition, the natural rate of employment is moving. The LRAS shifts continuously, not at discrete intervals. Setting it as a single vertical line and expecting it to be stable across a twenty-year forecast window is a mistake. Rebuild the curve each period using updated labor force projections. The real value of the LRAS is knowing where the economy tends to return, not predicting where it will be next quarter. Treat it as a gravitational center. Everything else orbits around it, sometimes for a long time before gravity reasserts itself.