Understanding What You're Actually Being Charged For
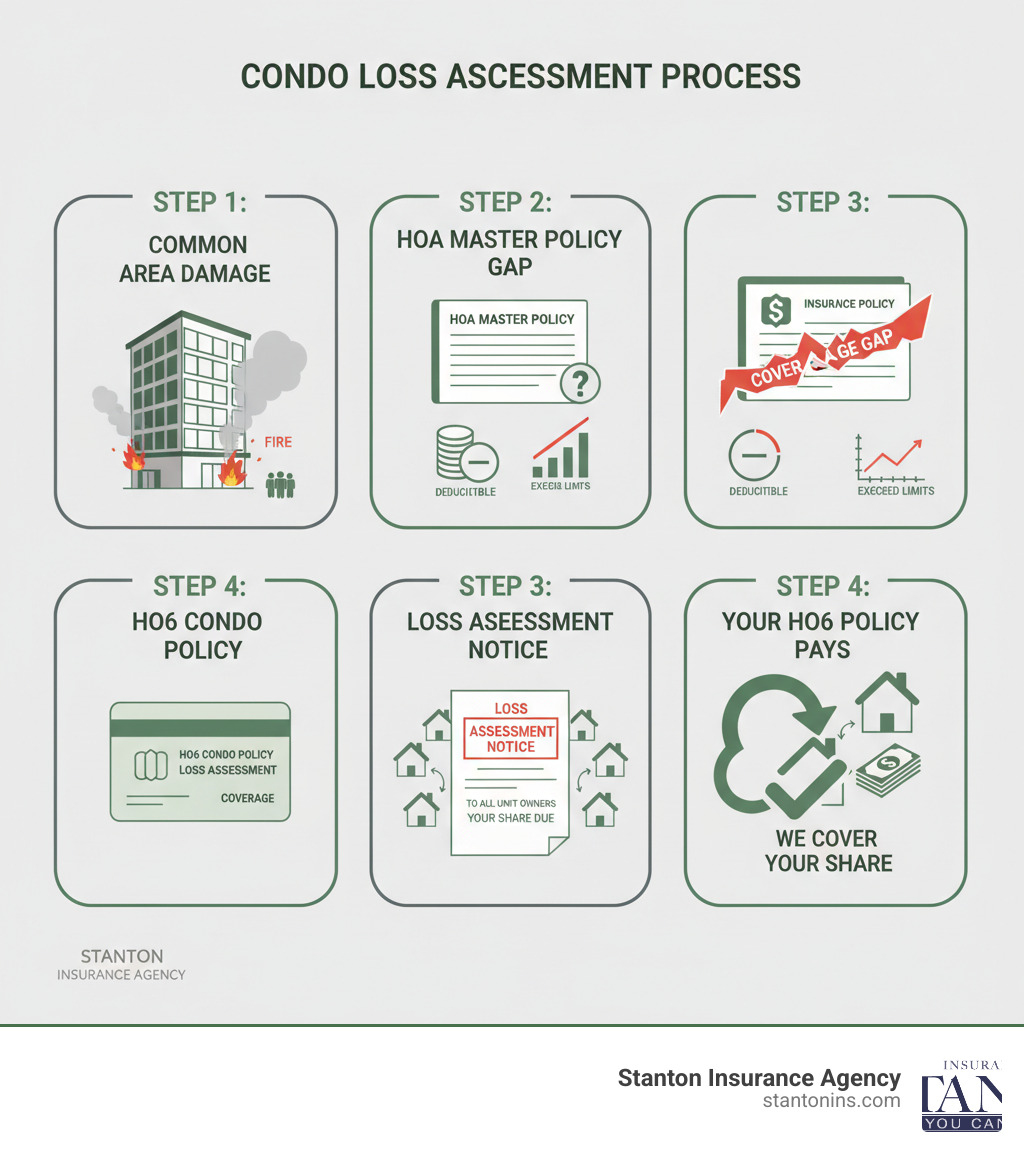
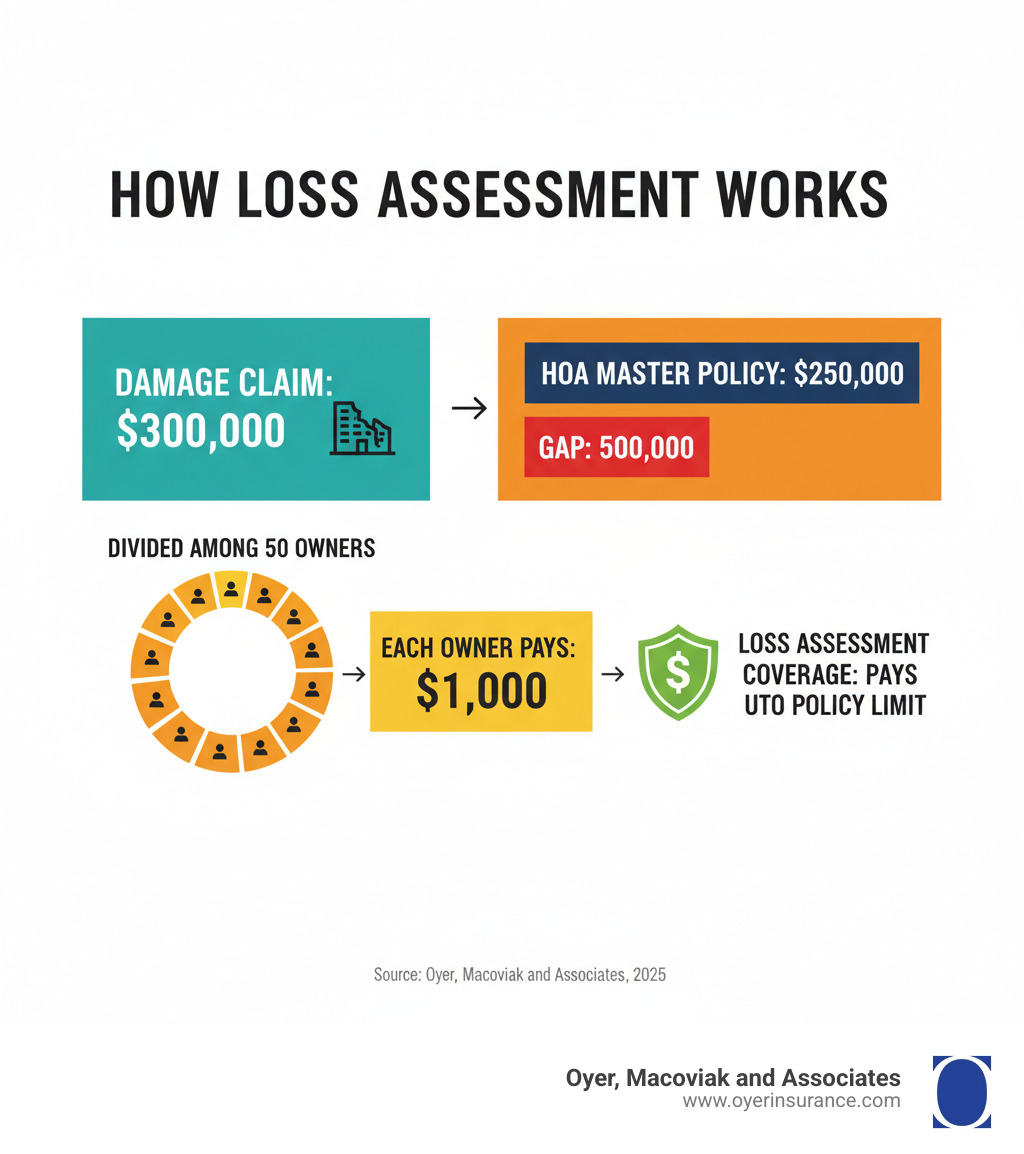
You move into a condo or join a homeowners association, and somewhere between the closing documents and the monthly fee spreadsheet, you see the line item for loss assessment coverage. It looks like insurance. It's not exactly insurance. That distinction matters when the bill comes due. Here's how it actually plays out in the real world, not the textbook version. When a master insurance policy on your building gets exhausted—say, a pipe bursts and floods twenty units, or a storm takes off the roof—the HOA or condo corporation can levy a special assessment on each unit owner to cover the gap between what the master policy pays and what it actually costs to rebuild. Loss assessment coverage is the piece of your individual policy that steps in to pay some or all of that charge. Without it, you're writing a check from your personal bank account, and those checks can range from a few thousand dollars to well over a hundred thousand depending on the severity of the event and how the master policy is structured.
Loss Assessment Coverage Meaning Explained
The basic meaning is straightforward: it's a protection mechanism that covers your share of costs the association's master policy doesn't fully cover. But the specifics where people get burned are in the details. Most standard HO-6 policies include a basic amount, often $1,000 to $2,000 by default. That sounds fine until the assessment comes in at $15,000 and you're eating the $13,000 difference because you never adjusted the coverage limit. I ran into this exact scenario last year with a client in Florida. Hurricane damage hit a coastal condo complex, and the master policy had a $50,000 deductible that the association hadn't properly disclosed during the resale certificate process. The total repair cost came to $420,000. After the insurance payout, the board levied an assessment of $28,000 per unit. My client's HO-6 policy had the standard $1,000 loss assessment limit and no endorsements. She was on the hook for $27,000 out of pocket. The workaround was aggressive: she filed a complaint with the state insurance department arguing the association violated disclosure statutes by not providing the actual deductible amount in the governing documents, which forced a renegotiation of the assessment down to $12,000. Combined with a supplemental coverage rider she managed to get added retroactively through her agent's good-faith adjustment, she ended up paying about $3,500 instead of $27,000. It took four months and three phone calls to the AG's office, but it was the only realistic path. What most people miss is that there are two fundamentally different types of loss assessments, and your policy may cover one but explicitly exclude the other. The first type is a direct assessment for property damage or liability claims against the association. This is what standard HO-6 coverage addresses. The second type is a special assessment levied for non-insurance purposes—funding areserve account deficit, paying for mandatory building code upgrades, or covering operational shortfalls. Standard loss assessment coverage does not touch this second category. I've seen homeowners assume their policy covers everything after an assessment notice arrives, then discover their policy specifically excludes assessments for reserve funding or code compliance. That exclusion is usually buried in the policy conditions section, not highlighted anywhere on the declarations page.
Another counter-intuitive point that deserves attention: the assessment doesn't have to come from a single catastrophic event. Some policies only trigger when the loss assessment arises from a covered peril on the association's property. If the board decides to raise dues because construction costs went up 40% on a routine renovation project, that's not a covered assessment under most standard forms. You'd need a specific endorsement or a separate policy provision to capture that exposure. The International Council of Association Managers reported that between 2019 and 2024, the frequency of non-property-damage assessments increased by approximately 67% due to supply chain inflation and labor shortages, yet awareness of what policies actually cover among unit owners remained stubbornly low at around 23% based on their consumer survey data.
Get the Full Details
How to Make Sure Your Coverage Is Actually Adequate
First step that nobody does: pull your HO-6 declarations page and look for the loss assessment line. If it says $1,000 and your association's master policy deductible is above that amount, you have a coverage gap before anything has even happened. Check the master policy too if you can get a copy—many HOAs make this available through their management company or at the annual meeting. The deductible amount on the master policy is the single most important number for calculating your exposure. If your master policy deductible is $25,000 or more, which is increasingly common in high-risk coastal and seismic zones, you should be looking at a loss assessment endorsement that raises your limit to at least $10,000, preferably $25,000 to match the deductible. The premium increase for bumping from $1,000 to $10,000 of loss assessment coverage typically runs $15 to $40 per year. That's not a lot of money relative to the risk. Going from $10,000 to $25,000 usually adds another $10 to $25 annually. These numbers vary by market, but the cost-to-benefit ratio is almost always favorable. There are practical limitations you need to accept upfront. Loss assessment coverage has a sub-limit within your overall policy. If your HO-6 has a $100,000 dwelling coverage limit and $10,000 in loss assessment coverage, the $10,000 is part of that total, not stacked on top of it. Some carriers offer scheduled coverage where the loss assessment amount is separate, but that's the exception, not the rule. Also, if the assessment exceeds your coverage limit, you're responsible for the remainder. There's no automatic escalation.
The coverage also typically requires that the underlying loss be a covered peril under the master policy. If the master policy excludes certain perils—flood being the most common exclusion—then losses from that peril won't generate a covered assessment even if the association levies one. You'd need separate flood insurance through NFIP or a private carrier to close that gap, and even then, flood assessment coverage within your HO-6 is extremely rare and usually requires a custom endorsement. When you're shopping for a policy or reviewing an existing one, ask specifically about whether the loss assessment coverage applies to special assessments for reserve funding and code upgrades. Get the answer in writing if you can. The standard ISO HO-6 form limits coverage to assessments arising from losses to common areas, but carriers can and do modify this. Some have started offering broader forms that include certain types of special assessments, particularly in states like Colorado and Texas where large assessments for building envelope failures have become common. The bottom line is that loss assessment coverage meaning extends beyond the dictionary definition into the practical question of whether your limit is high enough and whether the scope is broad enough for the actual risks your association faces. Most people buy the default and never revisit it. That's a gamble with real financial consequences.