What You Actually Need to Know About Loss History Insurance Definition
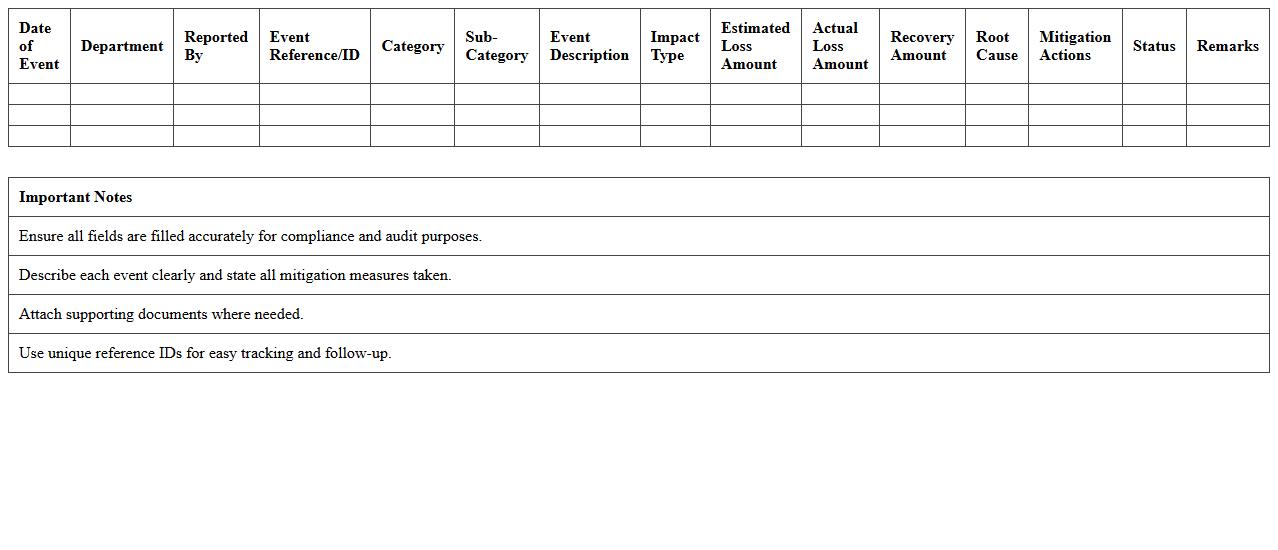
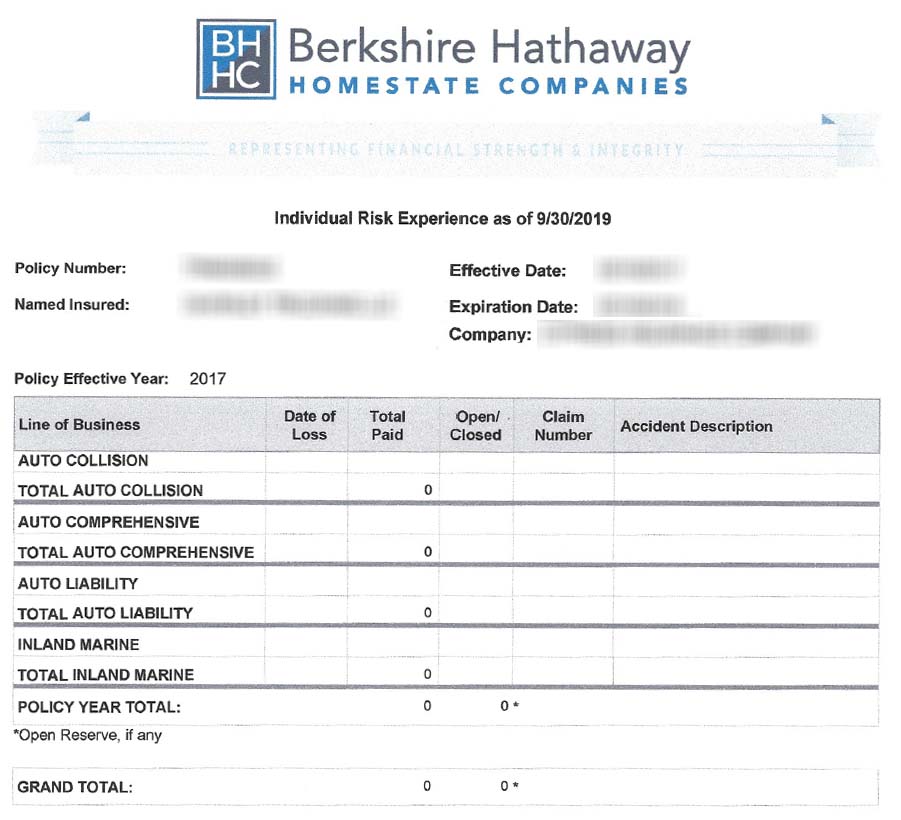
When brokers and underwriters talk about loss history, they are usually referring to something very specific and nothing more than that. The Loss History Insurance Definition centers on the documented record of past claims filed against a property or business over a set window of time, typically five years. That window matters more than most people realize because carriers will pull your CLUE report or request full loss runs from previous insurers to see what happened before they decide whether to bind coverage at all. I spent years watching people get stuck on this exact point during commercial policies renewals. The problem is rarely the definition itself. It is how the data gets presented and who interprets it. Underwriters do not just look at the total dollar amounts paid. They look at frequency, severity, recurrence patterns, and whether the losses were one-time events versus systemic issues that keep coming back. A single large claim often looks better than three small ones because it suggests an isolated incident rather than negligence.
How Loss History Insurance Definition Works in Practice
The process starts when you request your own loss runs from your current or prior insurer. Most carriers will provide these through CRM systems like Applied Systems or Vertafore. If you are working with a broker, have them pull a CLUE report for both the property and the business entity. The report covers the last seven years for personal lines and five to seven years for commercial depending on the state and carrier. The data shows every claim filed above the reporting threshold, which is usually $400 to $1,000 depending on the bureau and policy type. Here is where people make mistakes. They assume that if a claim was below the deductible, it will not appear on the loss runs. That is not true. Claims are reported to the industry databases based on filing, not payment outcome. If you filed a $6,000 water damage claim and your deductible was $2,500, the full claim amount shows up on the report even though you only paid $2,500 out of pocket. The underwriter sees $6,000 and adjusts their risk model accordingly. I ran into a situation last year with a manufacturing client who had a strong overall record but one recurring fire alarm false trigger event that showed up twice in three years. The carrier initially wanted to surcharge 25 percent. I pulled the maintenance logs and showed that both incidents were traced back to a known sensor issue from a contractor renovation, not actual fire risk. The carrier reduced the surcharge to 8 percent after reviewing the documentation. The workaround was getting the right evidence in front of the right person before the binding team made their final decision.
Counter-Intuitive Things Nobody Tells You
First, having zero claims on your loss history is not always the strongest position. Some underwriters view a clean record with skepticism, especially for higher-risk industries, because it may indicate the insured is not reporting smaller claims to avoid premium increases. This is called suppressed reporting and it is actually a known underwriting red flag. A modest history with properly documented claims that were resolved shows transparency. It also demonstrates that your risk management program is working as intended when claims happen. Second, the timeframe matters more than the raw number of claims. Two claims from eight years ago carry significantly less weight than two claims from the last two years. Carriers weight recent losses more heavily because they are better predictors of future behavior. If you had three claims in year one and zero claims since, you can often negotiate much better terms than someone with two claims spread across the last twenty-four months. The recency bias in underwriting models is real and it favors people who have maintained clean periods after past losses. Third, not all loss types affect pricing equally. A slip-and-fall claim on your premises might move the needle far more than a theft claim because premises liability directly correlates with ongoing safety practices. Carriers will scrutinize your security measures, training records, and maintenance schedules after certain loss types appear. They want to see that you are doing something different after a claim, not just paying the deductible and continuing the same operations.
Get the Full Details
Where This Falls Short
The loss history approach has real limitations. It is backward-looking by definition, which means it cannot account for improvements you have made since the last claim. An underwriter may reject a renewal based on a claim from three years ago even though you installed new fire suppression equipment six months later. The system does not automatically incorporate those changes unless you proactively submit documentation during the application process. Another bottleneck is that some carriers use proprietary algorithms that weight certain loss types differently than others in the same tier. One insurer might treat a vehicle accident claim the same as a general liability claim, while another applies a much steeper multiplier to auto-related losses. This inconsistency means shopping multiple carriers is essential because the same loss history can produce dramatically different premium quotes depending on which underwriting model the carrier applies. If you have a complicated loss history with multiple claims across different categories, the standard market may not serve you well. In those cases, considering a surplus lines carrier or a captive insurance arrangement can provide more pricing stability. Surplus lines carriers evaluate risk on a case-by-case basis and are not bound by the same standardized rating guidelines. You will pay higher premiums relative to the coverage, but you avoid the surprise non-renewal that comes from an automated underwriting system flagging your loss pattern.
The bottom line is that loss history is one of the most influential factors in insurance pricing and placement. It is also one of the most misunderstood. Understanding how the data gets reported, how it gets weighted, and where the gaps in the system exist gives you actual leverage. Most people never learn this because they do not have access to the underwriting side of the equation. Having that perspective changes how you prepare for renewals and how you present your risk profile to carriers.