
How to Actually Use a Loss Template Comprehensive Without Losing Your Mind
I got handed a loss template at my first claims adjuster job and spent three days trying to make it fit things that didn't fit. The template was built for standard property damage — roof replacement, foundation cracks, the usual. Then came the case where a warehouse fire involved inventory that had been partially replaced and partially sold before the inspection happened. My template had exactly one checkbox for "partial inventory loss" and it was wrong. That's the thing nobody tells you about a Loss Template Comprehensive. It's comprehensive in name, not in actual coverage. The template gives you a framework — and that framework is genuinely useful — but you will encounter edge cases where checking boxes makes more sense than actually documenting anything. I'm going to walk through how to use it properly, where it breaks down, and what I do when it does.
What a Loss Template Comprehensive Actually Is
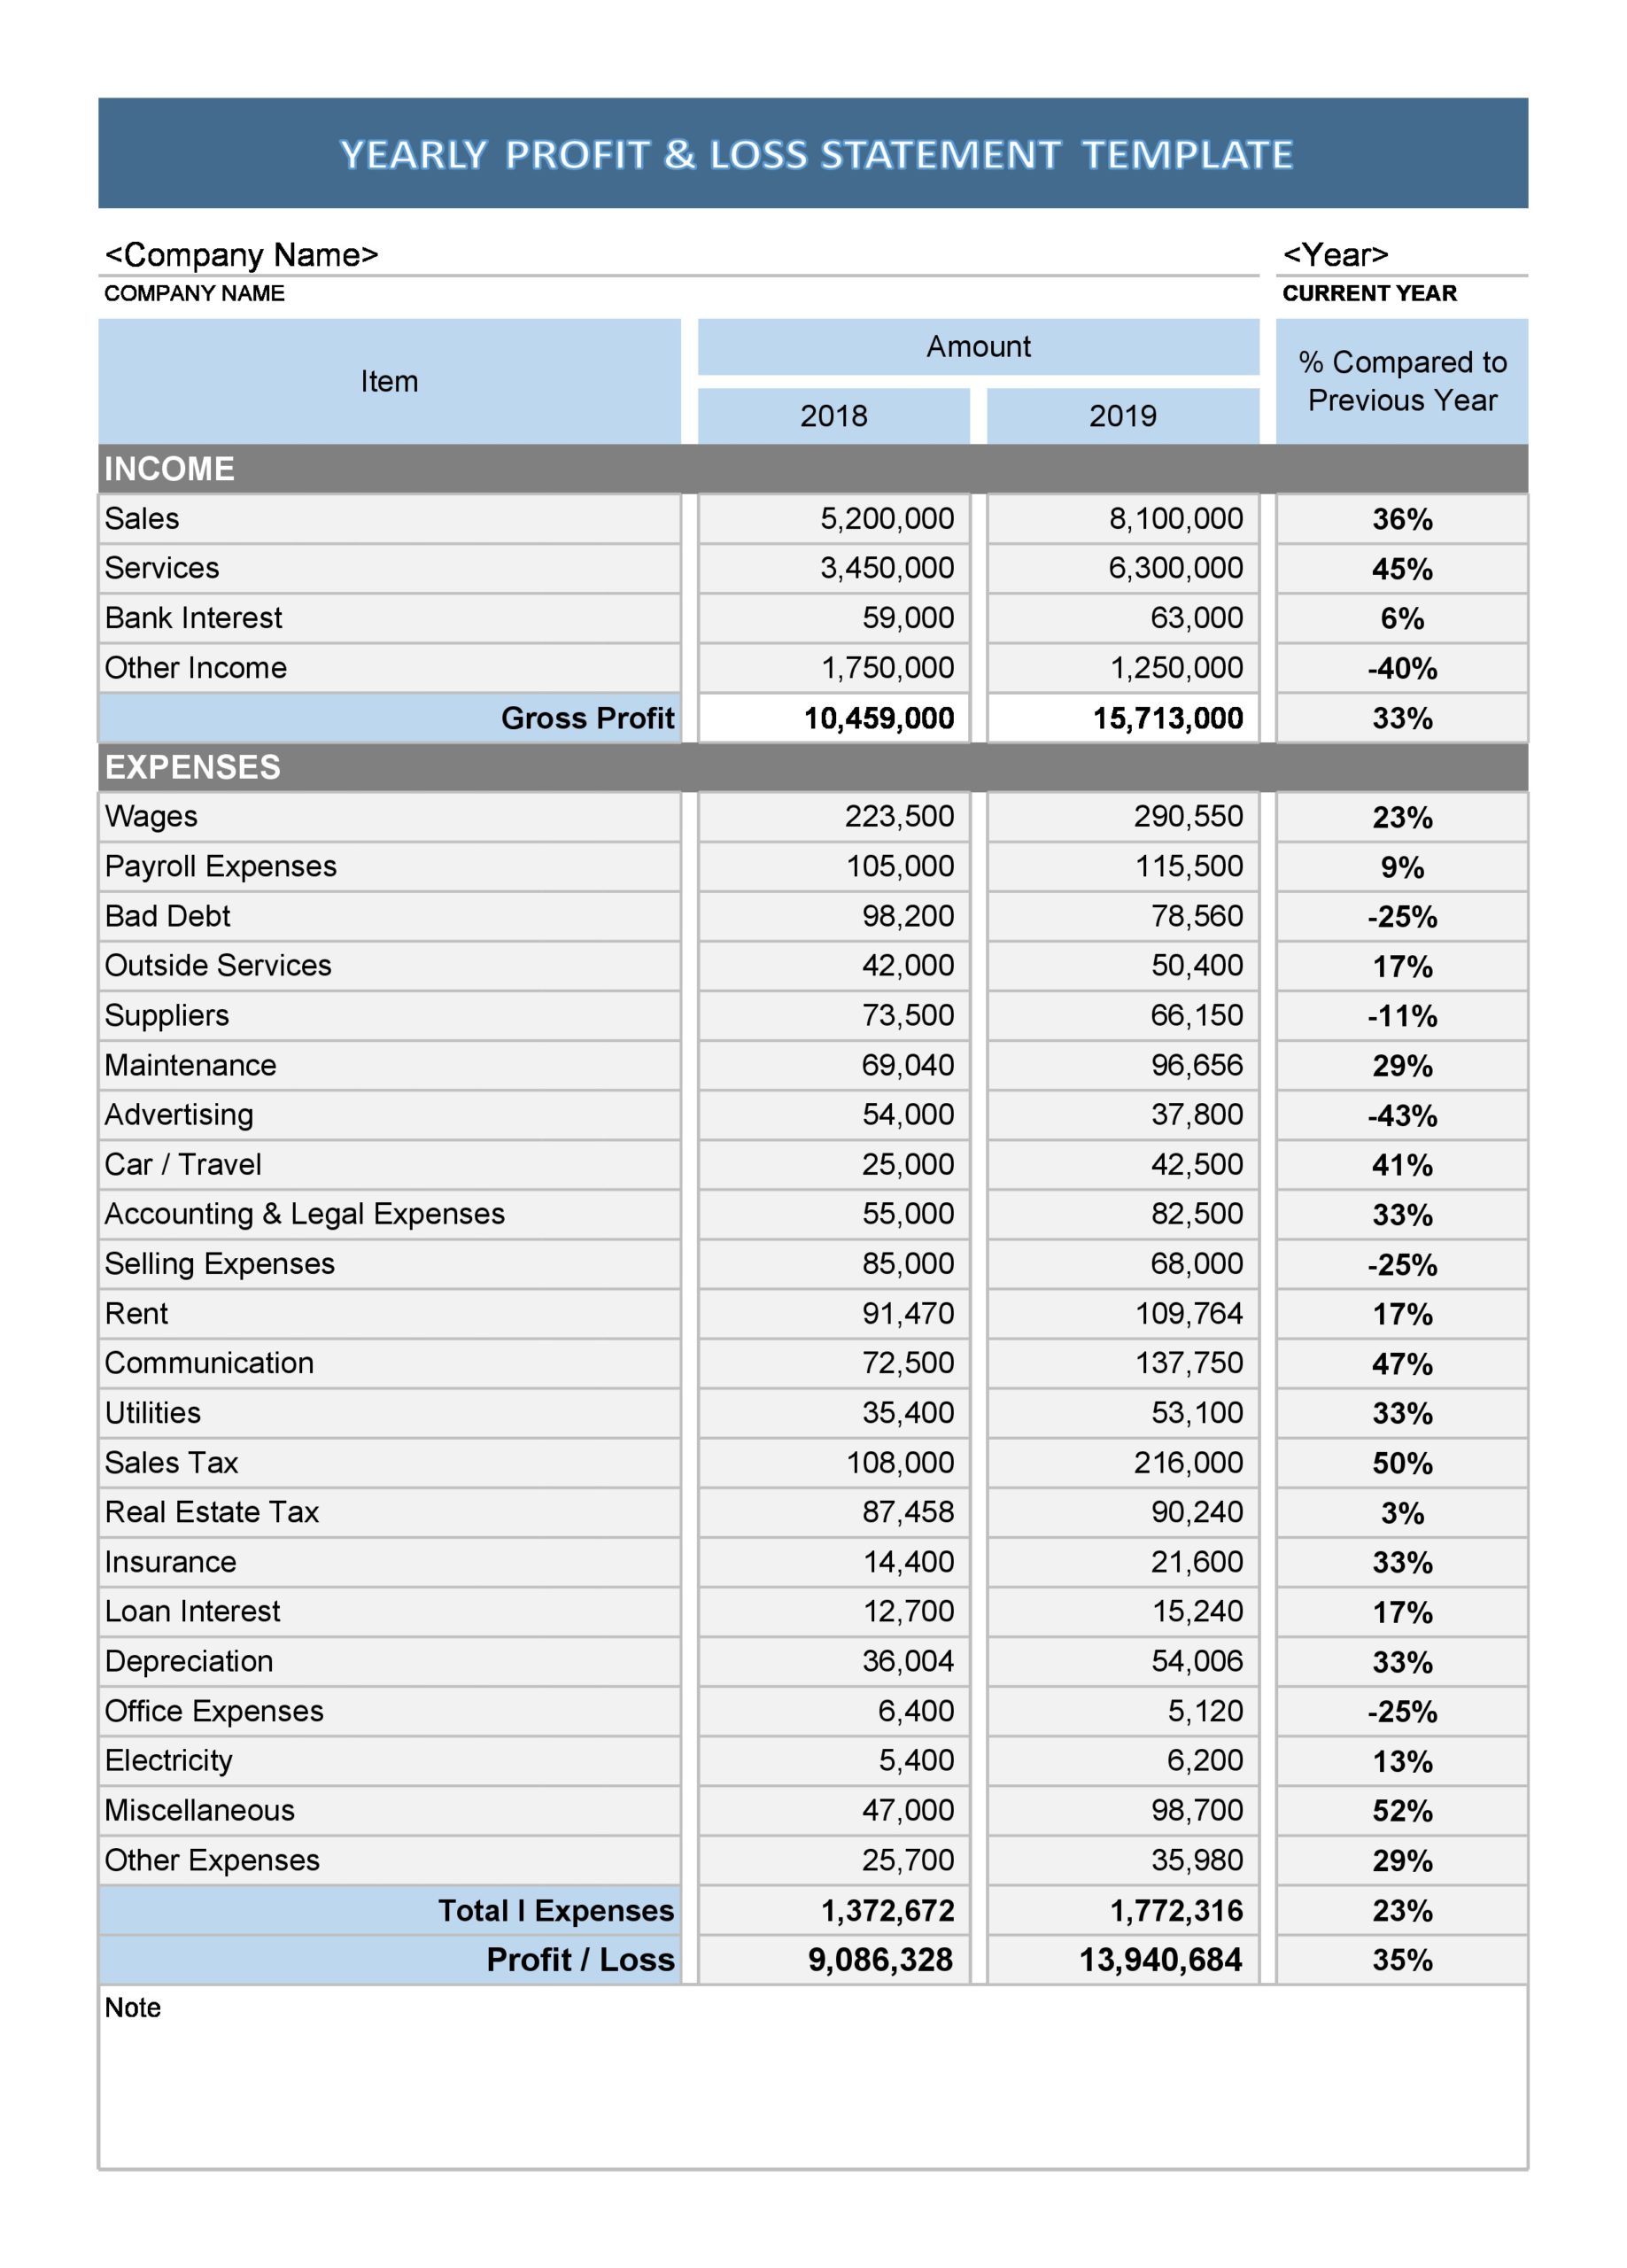
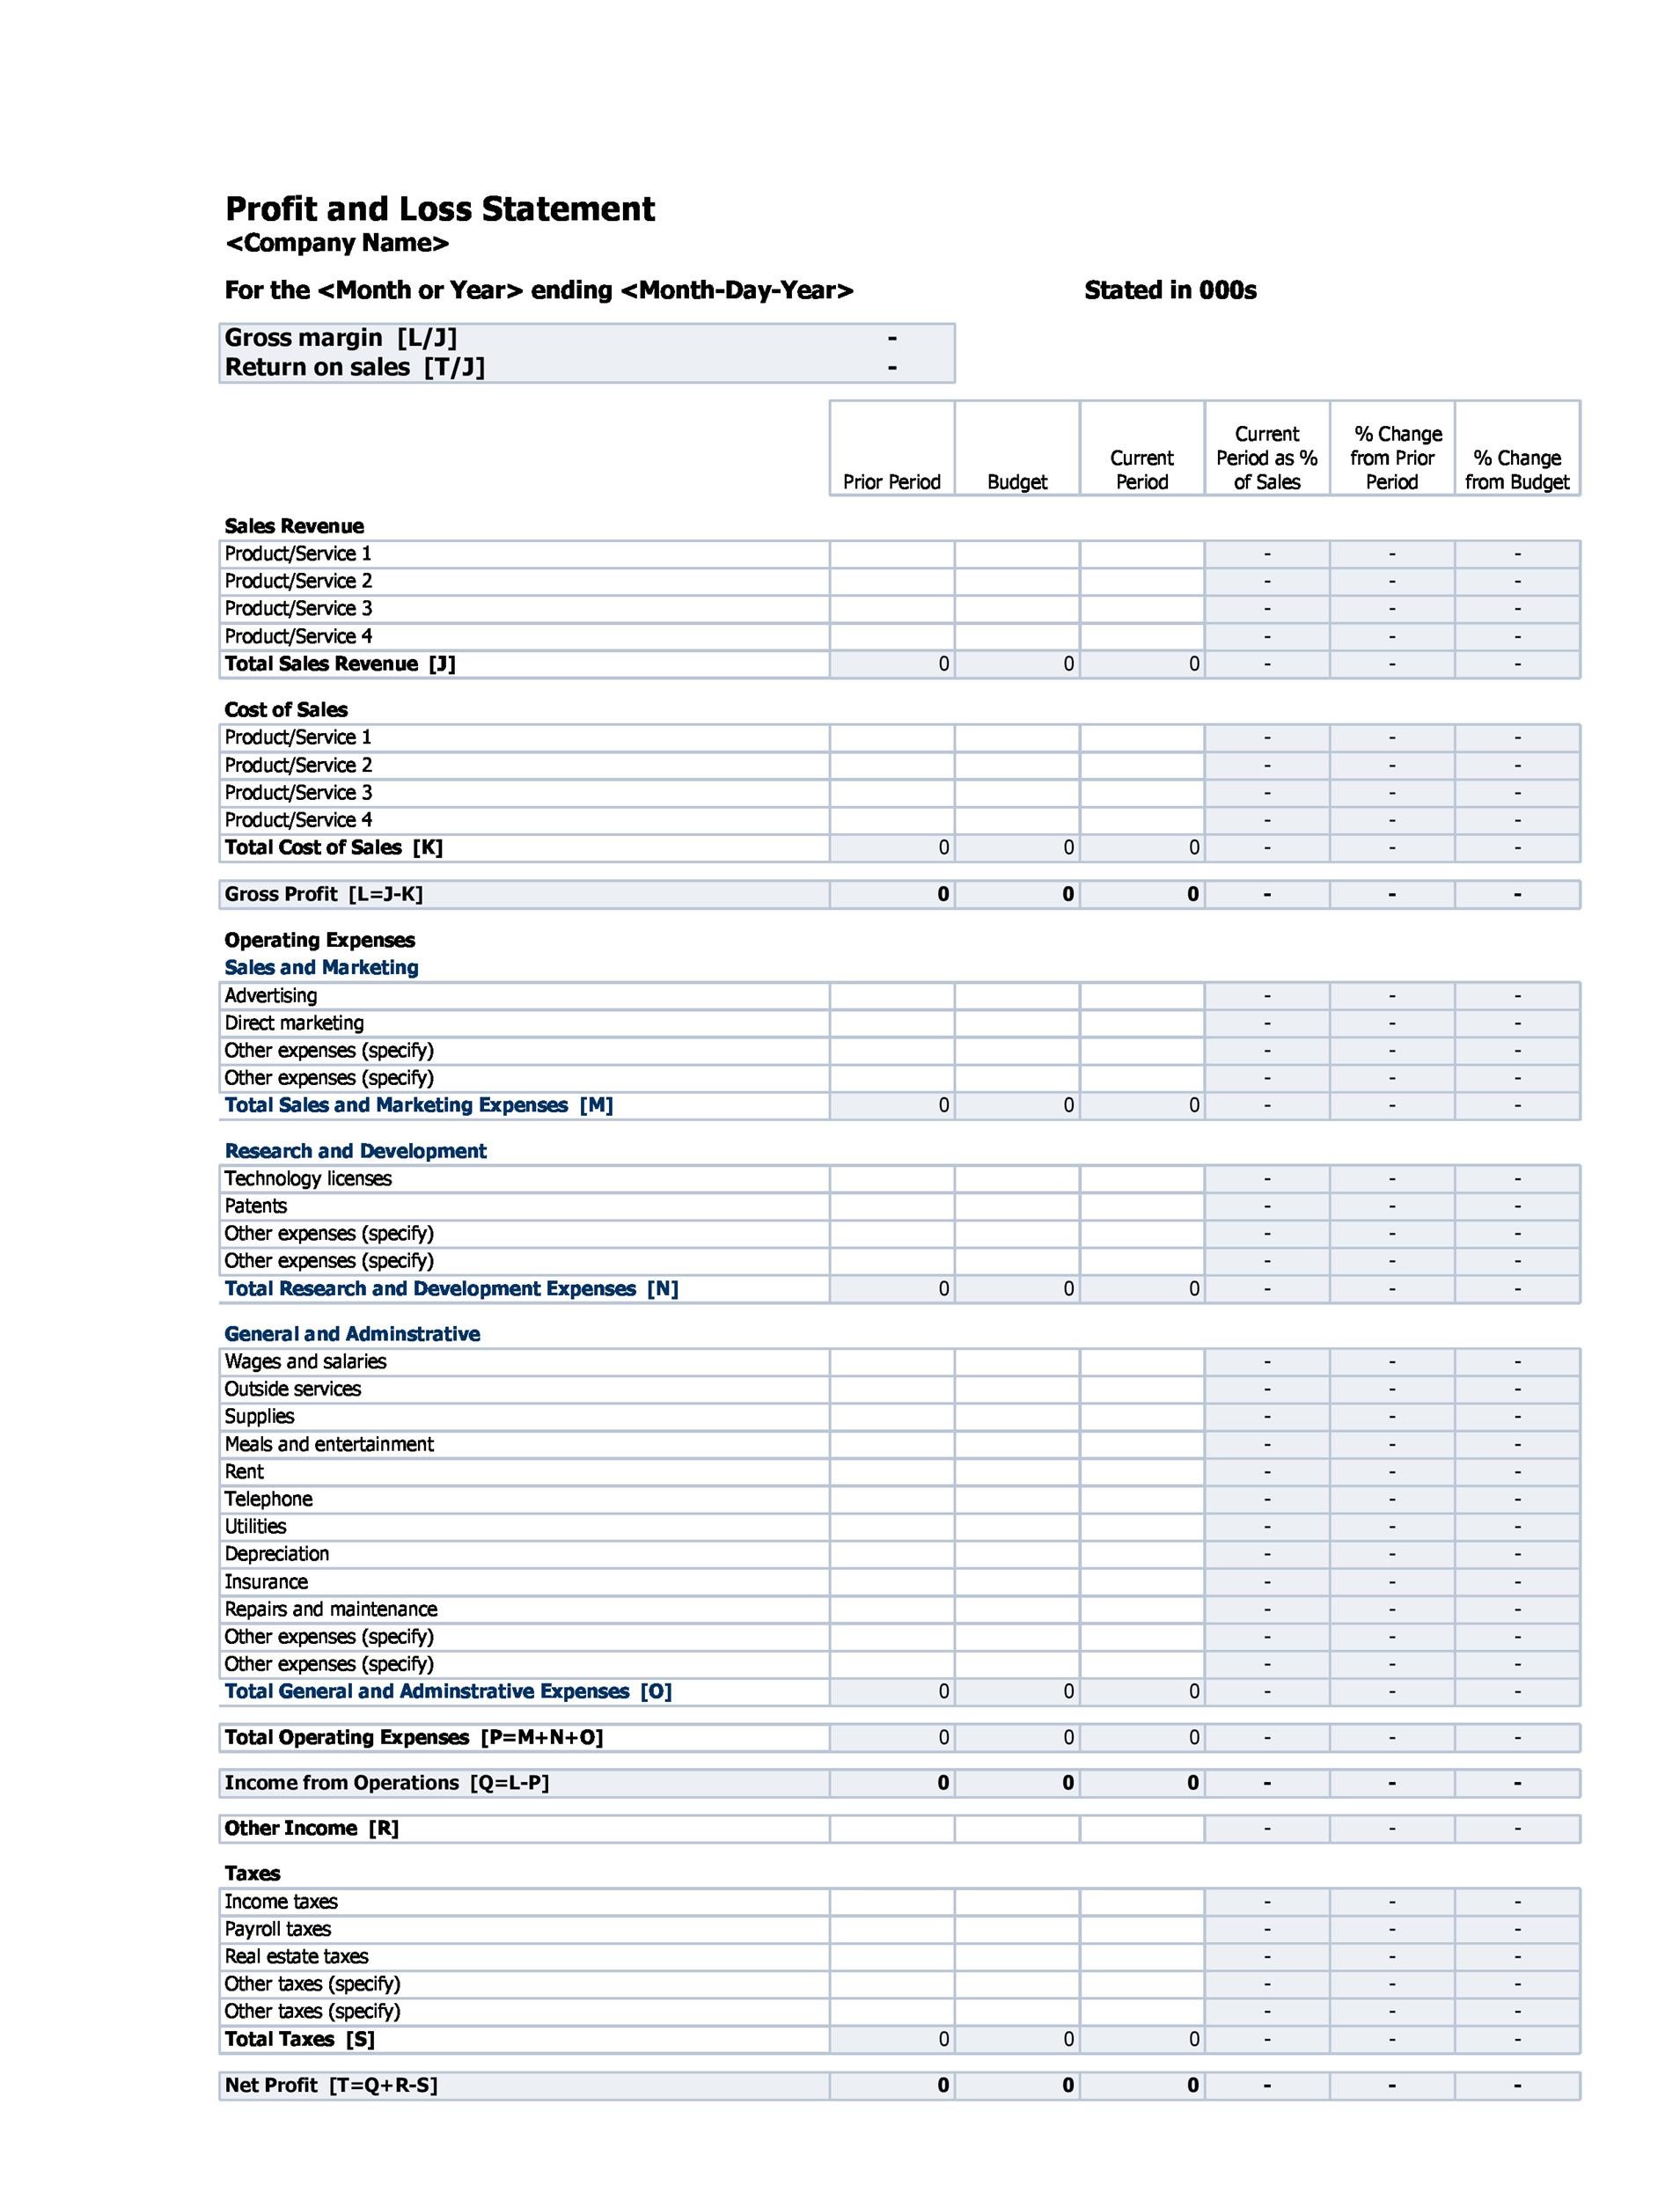
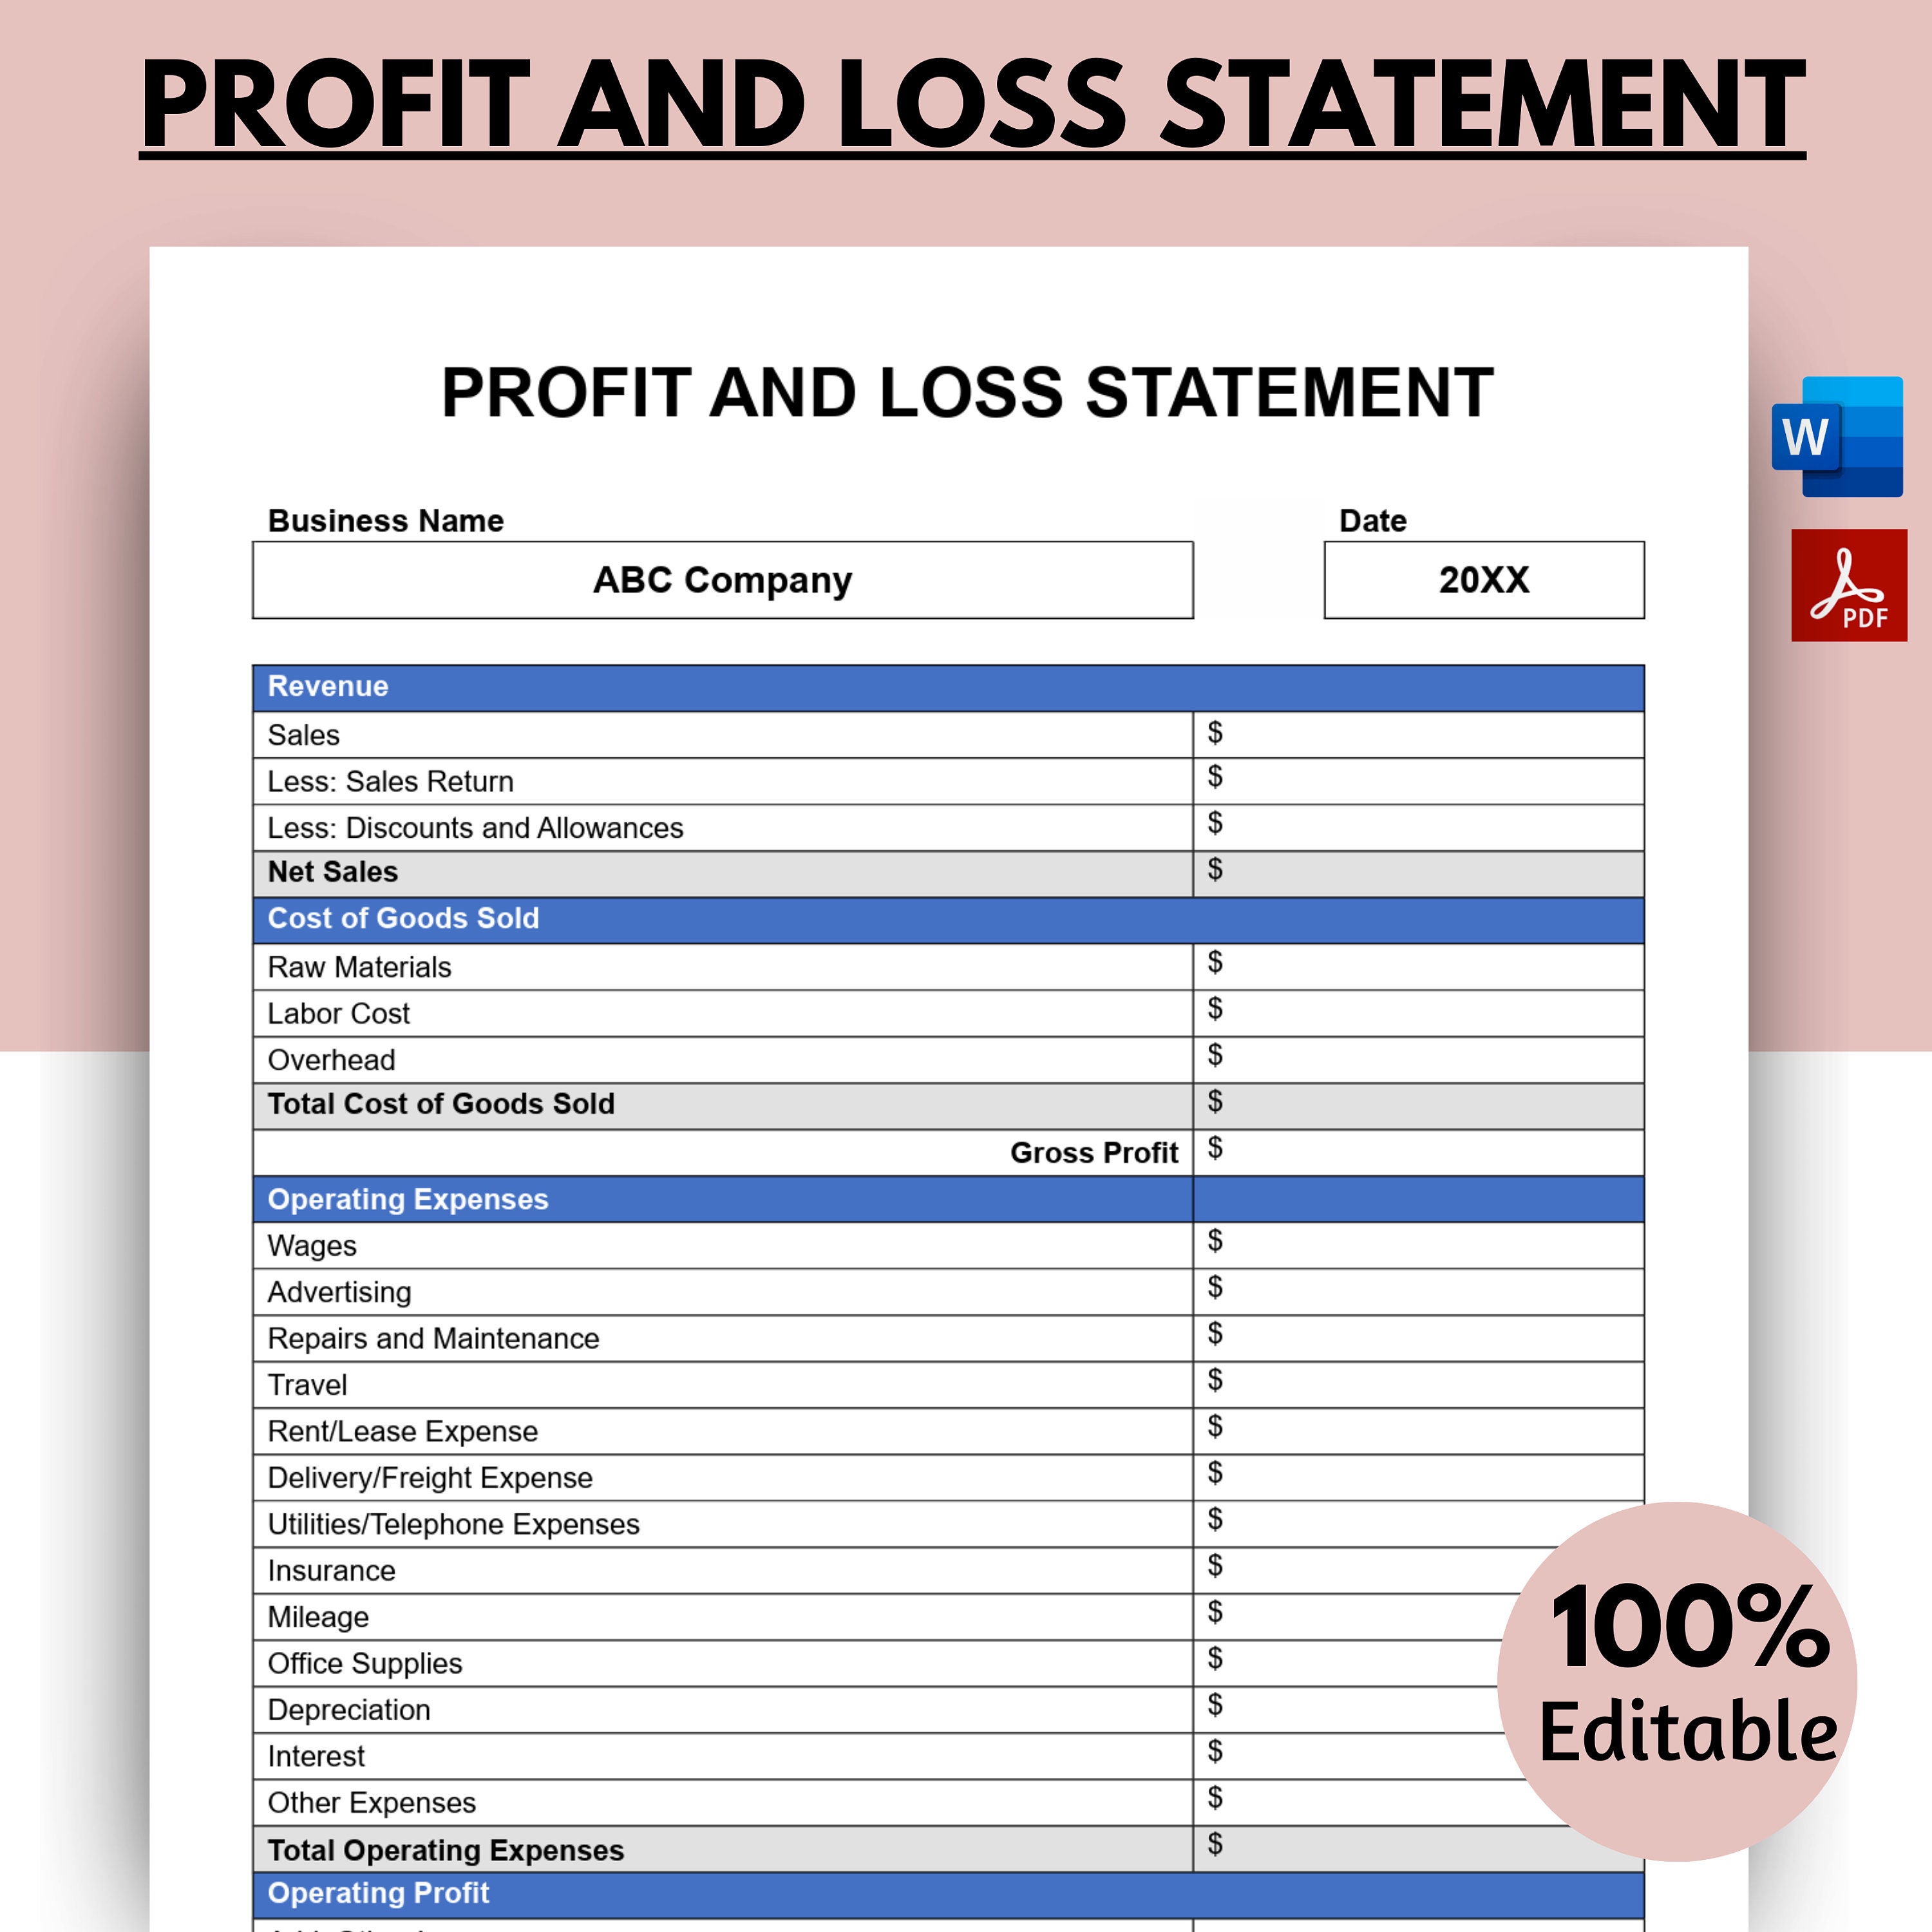
A Loss Template Comprehensive is a structured documentation form used primarily in insurance claims, risk assessment, and claims adjusting to record the details of a loss event. It captures the what, when, where, and how much of a claim in a standardized format that can be submitted to underwriters, actuaries, or legal teams. The comprehensive part means it covers multiple loss types — property, liability, business interruption, and sometimes even cyber incidents depending on your organization's setup. In practice, you'll see these used during initial claim intake, mid-claim status updates, and final settlement documentation. The form typically includes sections for policy details, loss date and description, involved parties, damage assessment, repair estimates, depreciation calculations, reserve amounts, and payment history. Here's a link to a standard version you can adapt: Loss Template Comprehensive download. It's a basic starting point. Don't use it as-is for complex claims.
How to Fill It Out Without Creating Future Problems
Start with the policy section. Get the policy number, coverage type, limit, deductible, and effective dates exactly right. I once saw a claim get delayed for six weeks because the adjuster wrote the wrong coverage type — they put HO-3 instead of HO-5, which is a different form with different replacement cost provisions. The policyholder ended up getting shortchanged by about twelve thousand dollars because the template made it look like a standard replacement cost claim when it should have been an extended replacement cost claim. For the loss description, write complete sentences. Not bullet points. Not abbreviated notes. Full sentences that someone who wasn't there could understand. When the adjuster before me wrote "water intrusion via failed supply line" I didn't know what supply line, what failed means, or where the water went. The corrected version reads: "Cold water supply line to kitchen refrigerator failed at braided connection, releasing approximately forty gallons of water over eight hours before tenant noticed dampness. Water migrated through cabinetry and into adjacent living room laminate flooring." That extra specificity matters when you're defending a settlement five years later. The damage assessment section is where most people rush. Don't. Take photographs from multiple angles. Include scale references — a ruler or tape measure in the frame. Note conditions that aren't visible in photos, like the musty smell behind a wall or the soft spots in subflooring that only show when you apply pressure. A photo shows surface damage. Your written notes show the full picture.
Get the Full Details
Common Pitfalls That Wreck Your Claims
Pitfall one: conflating cause with proximate cause. Just because water entered the building doesn't mean the water damage is covered. You need to document the cause of the water entry and determine whether that cause is a covered peril under the policy. A pipe bursting is typically covered. Flood water entering from outside is not, unless you have separate flood coverage. The template doesn't make this distinction for you — you have to. Pitfall two: not recording depreciation separately from actual cash value. Replacement cost and actual cash value are different numbers, and the template has separate fields for each. Fill both. If you only fill the replacement cost field and the policy pays actual cash value, the policyholder will complain that the estimate was wrong when the check arrives for significantly less. I've seen two claims where the adjuster forgot to enter the depreciation amount, and the policyholder assumed the higher replacement cost figure was the expected payout. It wasn't. It caused unnecessary disputes that took months to resolve. Pitfall three: using vendor estimates without verifying scope. I had a contractor submit an estimate that included replacing drywall in an entire second floor after a roof leak that clearly only affected one bedroom and the hallway. The template let me input the estimate number without questioning it. I should have walked the property myself before accepting the figure. The corrected scope came in at forty percent of the original estimate. I wasted a week reprocessing that claim.
My Workaround for the Inventory Problem
The warehouse fire case I mentioned earlier forced me to create a supplemental attachment for my Loss Template Comprehensive. The standard form had no way to handle mixed inventory scenarios where some items were replaced, some were sold, and some were destroyed. I built a spreadsheet that cross-referenced inventory records, sales data, and physical inspection results, then attached it to the claim file with a summary page pulled into the main template. The summary page included three tables: inventory on hand at time of loss, inventory destroyed, and inventory that was either replaced or sold prior to loss. Each table had quantity, unit cost, total value, and supporting documentation references. It took me about an hour to set up, and it saved me from making assumptions about the damaged inventory. The underwriter accepted it without questions. If you're dealing with complex inventory or partial-loss scenarios, I'd recommend building your own attachment system rather than forcing it into the template fields. The template isn't designed for that level of granularity.
What the Template Doesn't Cover (And Should)
The biggest gap I've found is that Loss Template Comprehensive doesn't handle concurrent causation well. When a loss is caused by both a covered and a non-covered peril — say, wind-driven rain entering through a storm-damaged roof — the template gives you no structured way to allocate the damage between the two causes. You write it as narrative, but there's no field for apportionment, and different adjusters will document the same situation differently. Another gap: moral hazard indicators. The template asks for loss history and claimed amount but doesn't have fields for behavioral red flags — the policyholder who seems unusually knowledgeable about coverage, the sudden increase in claimed value right before a policy renewal, the repeated claims in a short period. These matter. They just don't have a home on the form. For those situations, I keep a separate incident notes document attached to every claim file. It's not part of the Loss Template Comprehensive, but it's part of the record. The template is for the facts. The notes are for everything else.

Practical Tips That Actually Help
Use the reserve field as a living number, not a one-time entry. Reserves should be updated whenever new information changes the estimated cost. I've seen templates locked after the first entry, which means the reserve stays stale while the actual loss grows. If your system allows it, add a reserve revision log with dates and reasons for each change. When filling out the payment history section, record every transaction including adjustments, recoveries, and subrogation payments. A claim isn't closed until the template shows zero balance remaining and zero future obligation. I've seen "closed" claims reopened because someone forgot to record a subrogation recovery that reduced the payout. Always attach supporting documentation references to every major section. "See Exhibit A — photograph 3 of 47" is better than "see attached photos." When you come back to this claim six months later, you'll know exactly what you're looking at without digging through a folder.
When to Abandon the Template Entirely
There are claims where a Loss Template Comprehensive simply doesn't work. Large commercial losses with multiple policies, multiple locations, and complex business interruption calculations often require a custom documentation approach. I've handled claims where the template covered maybe thirty percent of what actually needed to be documented. The rest required spreadsheets, legal affidavits, engineering reports, and forensic accounting documents. If your loss exceeds fifty thousand dollars or involves more than one coverage type, I'd recommend building a supplemental documentation package alongside the template rather than trying to force everything into it. The template is still useful for the basics — policy info, initial loss description, contact details — but it shouldn't be the only thing in the file. Another scenario where it fails completely: claims involving disputed causation or litigation. Once a claim enters the legal process, the template format is too rigid for the kind of detailed narrative and evidence tracking you need. Switch to a structured claim chronology with date-stamped entries and exhibit cross-references. The template becomes background documentation at that point, not the primary record.
The Loss Template Comprehensive is a solid tool for standard claims. It gives you structure and consistency, which matters when you're processing dozens of claims in a month. But it's not a substitute for thinking about the claim. It won't catch the edge cases, and it won't document the things that aren't on the form. Know its limits, supplement where needed, and don't let the template create a false sense of completeness.
 (1).png "Profit and loss statement template | Free download")
