Understanding Loss Tracking Without the Fluff
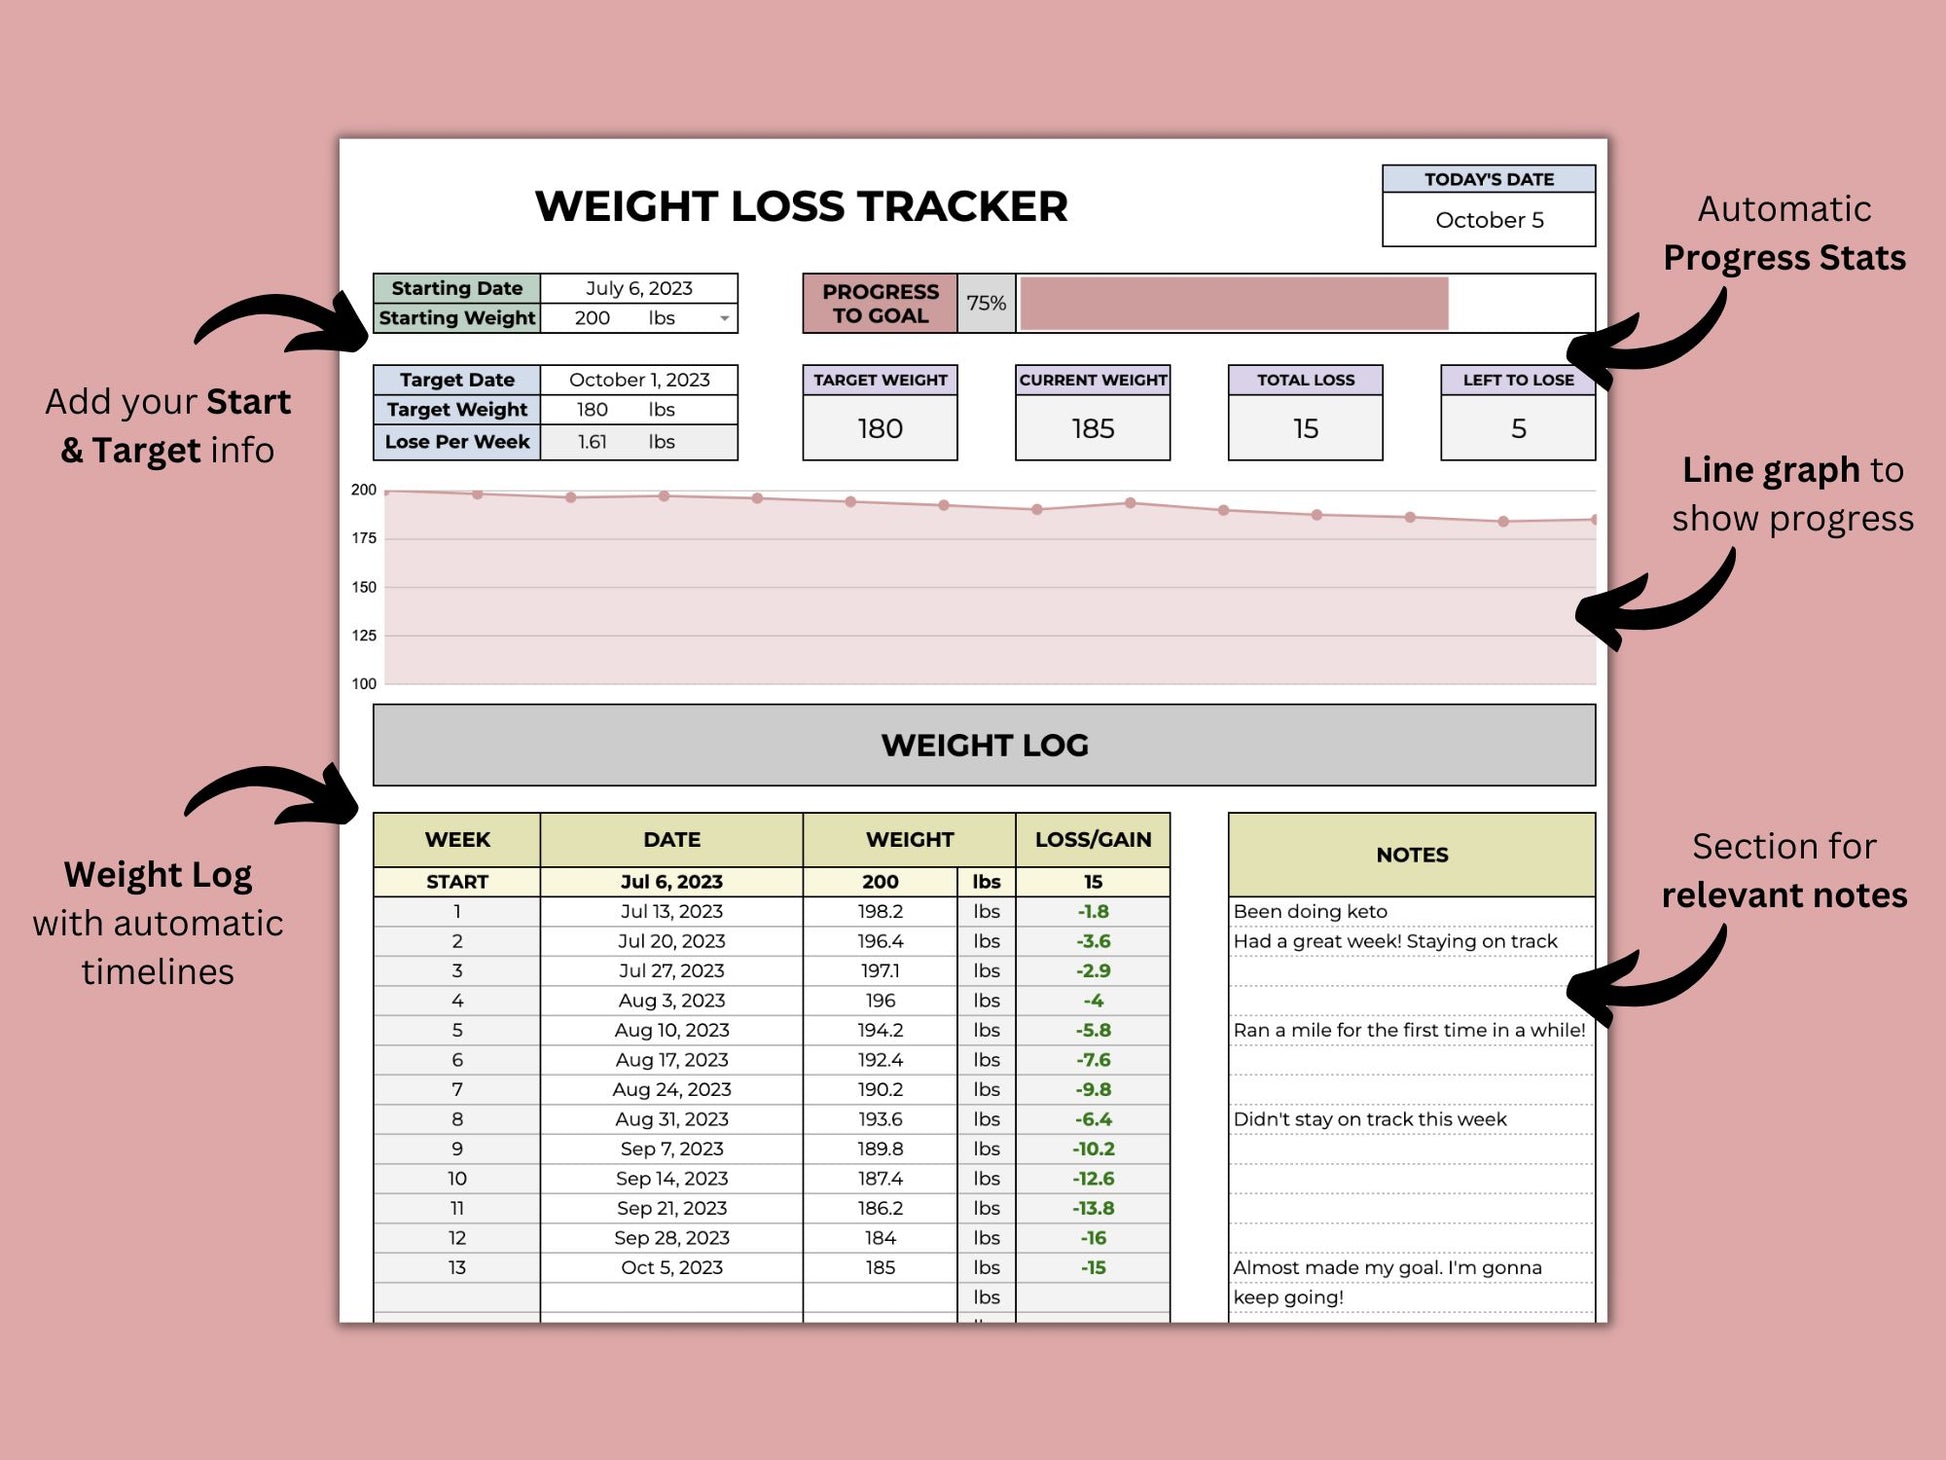
Loss tracking is just writing down when you lose money and why. The best approach isn't a fancy app or some subscription software that syncs to your bank every six seconds. It's a well-structured spreadsheet or a dedicated notebook system with consistent categorization. I've seen people spend more time setting up automated loss trackers than they actually save tracking losses manually. The problem is that most tools focus on recording the number and ignore the context. That context is what actually matters when you're trying to improve. I spent three years building and testing different loss tracking systems across trading, sports betting, and small business expenses. The system I end up recommending to everyone, including myself, is simpler than anything you'll find on Gumroad or Etsy for $47. A spreadsheet with five columns: date, category, amount, reason, and outcome follow-up. That's it. Most people skip the reason column and wonder why their tracking never leads to behavioral change.
How to Build a Loss Tracker Best Setup
Start by deciding what kind of losses you're tracking. The method changes depending on whether it's gambling losses, trading losses, business expenses that didn't pay off, or personal spending regrets. I used to try to track everything in one place and it became useless within two weeks. The categories got too broad and the data lost all meaning. My workaround was to build separate sheets for each domain and link them only through a master summary tab. The category system is where most people fail. Don't use generic labels like "food" or "entertainment." Use labels that tell you something actionable. Instead of "dining out," use "celebration dinner" or "work client meal." Instead of "trading loss," use "FOMO buy reversal" or "overnight gap loss." When you review your data three months later, the second set of labels gives you something to actually change. The first set just makes you feel productive while tracking. Record losses within twenty-four hours of them happening. I learned this the hard way after losing a entire quarter of tracking data because I was too lazy to log entries the same day. The details blur fast. You forget whether that bet was a bad beat or just a poor decision. You forget the context around the expense. Set a daily reminder or tie logging to an existing habit like your morning coffee. Twenty seconds per entry is all it takes.
What People Miss About Loss Tracking
The biggest counter-intuitive truth is that logging losses frequently doesn't necessarily reduce them. In fact, some traders and bettors report the opposite effect. The act of recording can create a false sense of control and lead to taking more risks. I saw this happen to a friend who tracked every sports bet for six months, felt like he had mastered the process, and then blew through three months of profits in two weeks. The tracker gave him confidence without giving him insight. The fix was adding a mandatory reflection field where he had to write one sentence about whether the risk was justified before hitting submit. Another thing nobody tells you is that loss tracking has a severe blind spot around small frequent losses. A $5 mistake logged every day looks harmless in aggregate until you hit a thousand dollars in twelve months. The human brain discounts repeated small losses more than a single large one. My solution was to add a weekly aggregate view that auto-calculated seven-day totals. Seeing $35 disappear in a single line item from a bunch of $5 entries was a much stronger behavioral signal than the individual logs ever provided.
Get the Full Details
Pitfalls and Where This Approach Breaks Down
Spreadsheet-based loss tracking breaks when your income sources multiply. If you're tracking losses across five different trading accounts, three betting sites, and a side business, maintaining one master file becomes a part-time job. I hit this wall at around month eight and switched to a simple database approach using Airtable. The transition took one afternoon and eliminated about forty percent of my logging time going forward. The downside is that Airtable's free tier has row limits and you start paying once you go past a few hundred entries per month. There's also the emotional fatigue factor. Logging every loss honestly for more than six months is draining. I've had periods where I stopped tracking entirely because the exercise felt like keeping a scoreboard for everything going wrong. The workaround was implementing a semi-automated version. I exported transaction history from my broker and betting sites directly into the spreadsheet using CSV imports and set up conditional formatting that color-coded entries by category. This reduced manual entry to maybe ten minutes a week instead of an hour and kept the system sustainable long-term. If you're looking for a pre-built Loss Tracker Best template rather than building your own, there are decent options on Google Sheets marketplace and some independent creators on personal finance forums. I don't have a specific download link to share since those templates change hands frequently and most of the paid ones are overpriced for what they offer. The free community versions on r/personalfinance and r/betting typically get updated regularly and tend to be more practical than the polished paid products. Whatever you use, the structure matters far more than the visual design. A ugly spreadsheet that you actually maintain beats a beautiful one that collects digital dust.
One final note on the numbers side. Make sure your tracking includes both gross and net figures. Gross loss tells you how much you put at risk. Net loss after wins or refunds tells you what actually left your account. The gap between those two numbers is where real pattern recognition happens. I found that my betting losses looked terrible on a gross basis but were actually quite manageable once I factored in bonus cashback and voided bets. Conversely, some trading losses looked small in gross terms but became catastrophic once commissions and slippage were included. Both perspectives are necessary. Neither is sufficient on its own.