Understanding Lot Financing Calculators in Practice
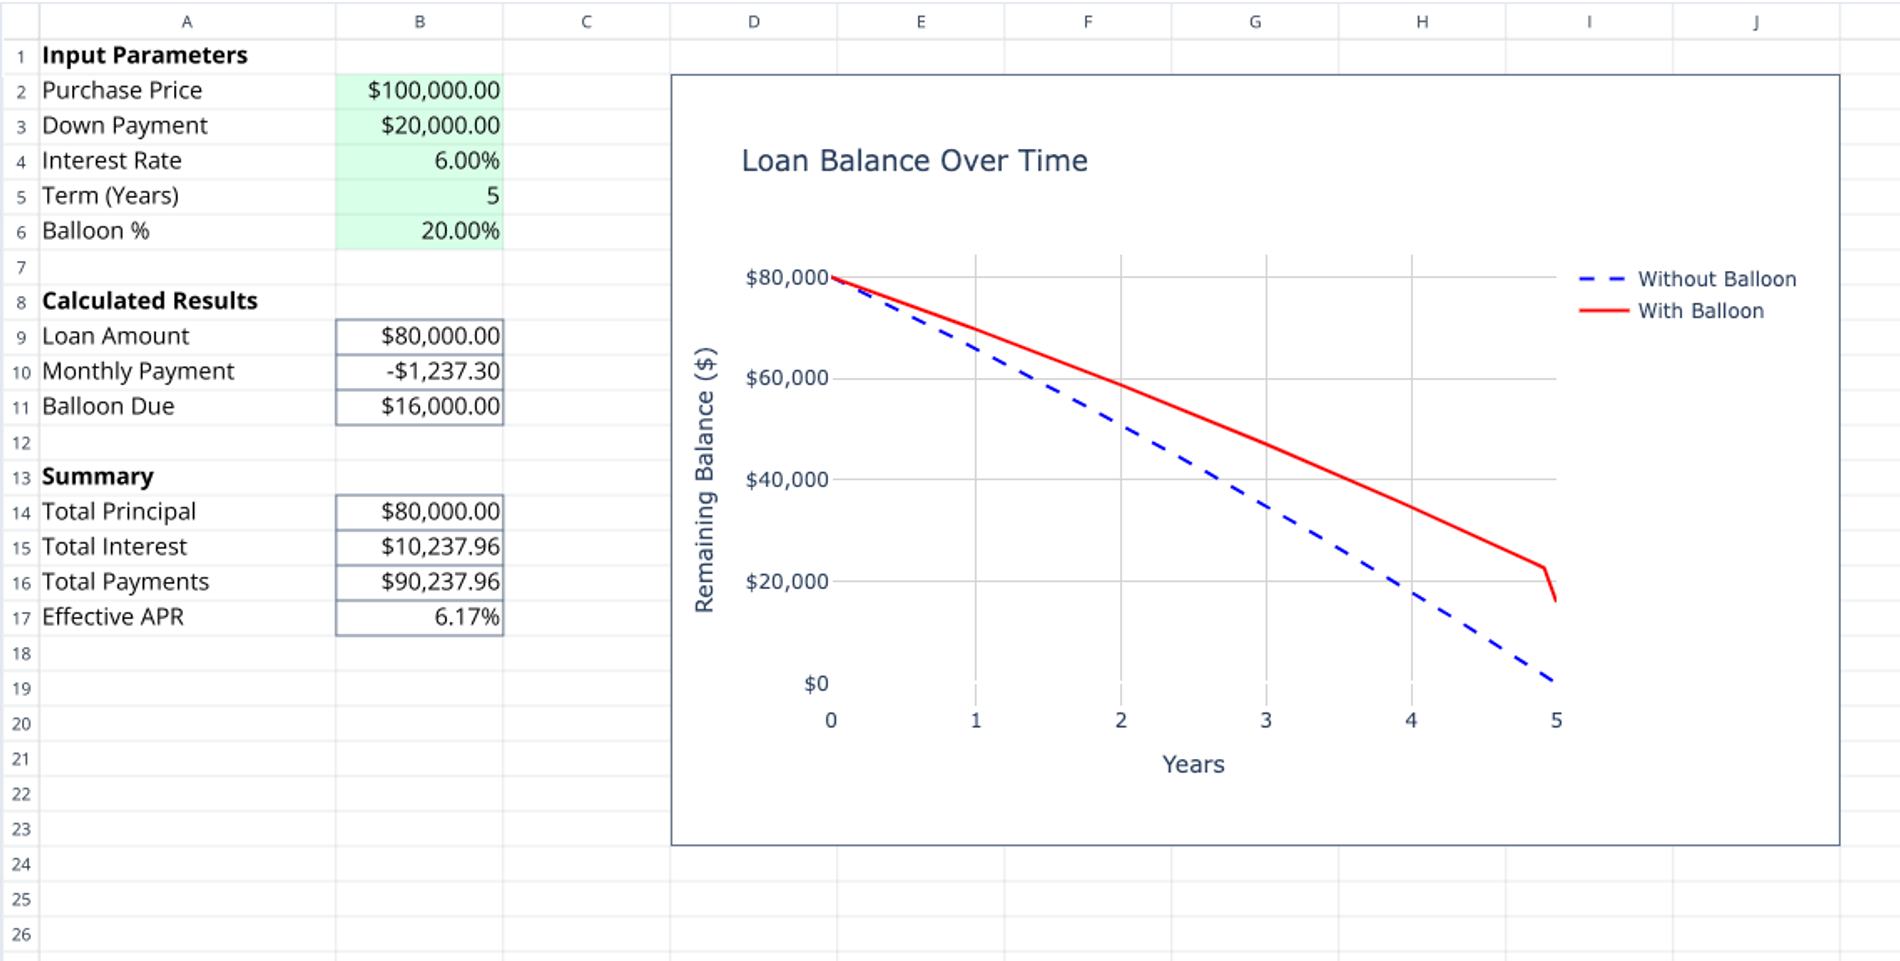
A lot financing calculator is a specialized tool that computes monthly payments, total interest, and payoff amounts for loans used to purchase vacant land or development plots. Unlike standard mortgage calculators, it accounts for differences that matter when you're funding undeveloped property rather than an existing home. Land loans carry higher interest rates, shorter terms, and larger down payments because the collateral is harder to liquidate if things go wrong. The calculator needs to reflect all of that. The core formula is the same amortization equation you'd see in any loan calculation, but the input parameters are what separate a land loan from a conventional mortgage. You start with the loan amount after your down payment, the annual interest rate, and the loan term in months. The monthly payment formula divides the principal by the present value of an annuity factor, which accounts for compounding interest over the life of the loan. What most online calculators get wrong is that they treat the interest rate as if it's fixed at a residential level. In practice, land loan rates can run 2 to 4 percentage points above conventional rates. A $50,000 lot financed at 6% over 15 years gives a very different number than the same lot financed at 9.5% over 10 years. The second scenario pays $1,387 per month versus $416, and the total interest paid jumps from roughly $24,800 to $31,500. That gap is where deals go sideways.
The down payment requirement is another variable most calculators either ignore or handle poorly. Banks typically require 20% to 50% down on raw land. Some lenders demand 60% for unimproved lots with no utilities or road access. When a calculator assumes a standard 10% or 20% down payment, the resulting monthly payment looks attractive but is completely unrealistic for the actual loan amount you'll qualify for.
Setting Up a Practical Calculation Step by Step
First, determine the lot price and any closing costs or development fees that might roll into the loan. Some lenders allow you to finance a portion of those costs, others don't. Second, establish your down payment percentage based on the lender's actual requirements, not the most favorable scenario you can find online. Third, get the real interest rate and loan term from at least two lenders. Land loan products vary wildly between institutions. Enter those figures into a calculator that allows you to adjust each parameter independently. I recommend using one where you can toggle whether the rate is fixed or adjustable, whether there are prepayment penalties, and whether impound or escrow amounts apply. Most standard mortgage calculators assume these are included. They almost never are for land loans. After running the numbers, verify the output manually with a simple spreadsheet. Calculate the monthly interest component by dividing the annual rate by twelve and multiplying it by the remaining principal balance for that period. Subtract that from the stated monthly payment to get the principal reduction. Repeat for several periods to confirm the amortization schedule matches what the calculator is showing. You'd be surprised how often they don't, especially on cheaper online tools.
Get the Full Details
Common Pitfalls That Cost People Money
The biggest mistake I've seen is borrowers who use a generic mortgage calculator and then assume the result applies to their lot financing. It doesn't. The payment will be significantly higher once you plug in the actual land loan terms. This creates a budgeting shortfall that surprises people during underwriting, sometimes losing a deal at the last minute because the monthly obligation exceeds what their debt-to-income ratio allows. Another frequent issue is ignoring the shorter loan terms. Conventional mortgages offer 30-year terms. Land loans typically max out at 15 to 20 years, with many lenders capping them at 10 years for raw land. The shorter term means substantially higher monthly payments even at a lower total interest cost. When evaluating affordability, focus on the monthly number, not the total interest over the life of the loan. Tax and insurance obligations on vacant land are also easier to overlook. Unlike a residential mortgage where those might be escrowed into the payment, land loan payments rarely include them. Property taxes on zoned or lots can be significant depending on jurisdiction. Factor those into your actual monthly out-of-pocket cost separately from the loan payment itself.
Edge Case: The Split-Lot Scenario
There was a situation I worked through where a borrower wanted to purchase a single large parcel that could be subdivided into three smaller lots, and they needed financing for the full tract with the intention of splitting it later. Standard calculators don't account for this because the loan structure itself changes mid-term. The original loan covered the entire parcel, but after subdivision, each new lot could potentially be financed separately at better terms, or the original loan might need to be restructured. The workaround I used was to run two separate calculations: one for the original loan on the full parcel, and another modeled scenario for paying off the original loan and financing each sub-lot individually after subdivision. The comparison showed that even with closing costs on both transactions, splitting the financing after subdivision saved approximately 18% in total interest over the life of the loans. That only became visible because I calculated both paths rather than relying on a single scenario.
When to Use an Alternative Approach
A Lot Financing Calculator works well for quick estimates and comparing basic scenarios, but it has real limitations for complex situations. If your lot purchase involves seller financing, assumable loans, land contracts with balloon payments, or any non-standard arrangement, the calculator's assumptions break down. These instruments have payment structures that don't follow standard amortization schedules. For developer-grade projects involving multiple lots, phased financing, or construction-to-permanent conversions, spreadsheet modeling or professional financial software gives you much more control. You can model variable interest periods, partial prepayments, draw schedules, and cash flow timing that a standard calculator simply can't handle. The upfront time investment pays off quickly once your scenario gets more than five or six moving parts. Download a simple template if you're going this route. A well-structured spreadsheet with separate tabs for the base case, best case, and worst case scenarios will give you more useful information than any standalone calculator tool. Include columns for loan balance, interest paid, principal paid, remaining term, and cumulative cash outflow at each period. Update the model whenever terms change during negotiation rather than assuming the initial numbers are final.

What the Numbers Don't Tell You
Calculated payment amounts don't reflect opportunity cost, which matters significantly for land investments. Money tied up in a lot loan earning no return while you wait to develop or resell is money working against you. Shorter loan terms and higher monthly payments reduce this drag but increase monthly cash flow pressure. There's a tradeoff that no calculator will highlight for you. Location-specific risks also fall outside any calculator's scope. Zoning changes, environmental remediation requirements, utility extension costs, and access restrictions can all add tens of thousands in unexpected expenses after closing. A calculator showing a clean $800 monthly payment doesn't capture whether you'll also need to spend $45,000 to bring power and water to the site. Those costs should be evaluated independently and factored into your overall acquisition budget before you commit to financing terms. The useful outcome from any lot financing calculation is a range, not a single number. Run the calculation at three interest rate points: the quoted rate, the quoted rate plus 1%, and the quoted rate plus 2%. This gives you a realistic band for monthly obligations that accounts for rate variability between lenders and potential adjustments during the underwriting process. Land loan rates are less standardized than residential mortgage rates, so the spread between your best and worst case might be wider than you expect.