Getting Your Louisiana Insurance License: What Actually Happens
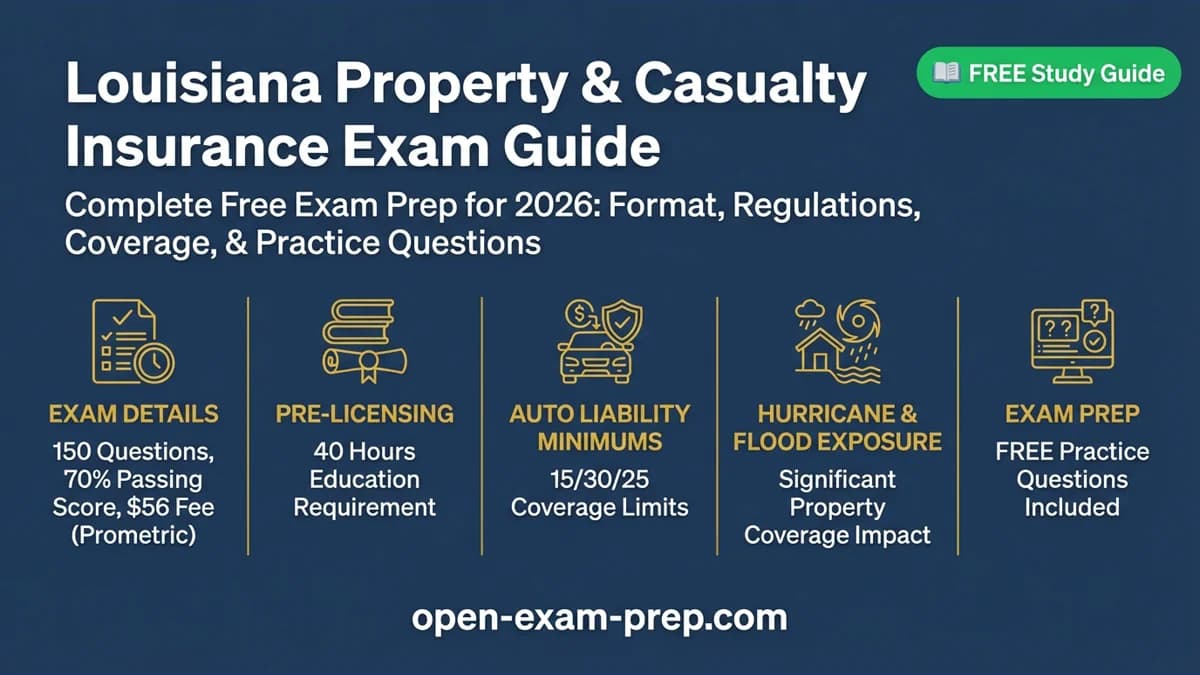
The Louisiana Insurance License Exam isn't particularly difficult if you approach it correctly, but the process itself has more moving parts than most people expect. I spent years watching agents fail at different stages, and the pattern is always the same. They focus entirely on memorizing flashcards and completely ignore the administrative side of things. Before you even think about studying, you need to complete the pre-licensing education requirement. Louisiana requires a minimum of 24 hours of approved coursework for lines of authority like property and casualty. For life insurance, it's also 24 hours. If you're pursuing both, you'll need separate courses unless you find a bundled program that the Louisiana Department of Insurance recognizes. Here's where things get messy. The state doesn't approve just any course provider. I had a client who finished a 40-hour online program from a company that looked legitimate, only to find out after the fact that the Louisiana DOI didn't have them on the approved list. That burned six weeks and another couple hundred dollars. Always verify with the department directly before purchasing anything.
Once your coursework clears, you register with Pearson VUE to take the licensing exam. You'll pay an exam fee, which runs around $50 to $70 depending on the line of authority. The exam itself is computer-based and usually takes about two hours. You'll get 90 to 120 questions depending on which exam you're writing. A score of 75 is the passing threshold, though you should be aiming higher since you only get two attempts before having to restart the entire application process.
What Actually Shows Up on the Test
The questions are more applied than you'd expect from a standard multiple-choice exam. Instead of asking you to define a term in isolation, they'll present a scenario and ask what you'd do as a licensed agent. For example, they might describe a situation where a policyholder's claim is partially covered under their HO-3 policy after a windstorm, and you have to determine the correct procedure for handling the adjuster assignment and communication with the insured. The part that catches people off guard is the ethics and state law section. Louisiana has specific regulations that don't appear on exams in other states. The unfair claims practices section alone can account for roughly 15 to 20 percent of the exam. I remember working with someone who bombed her first attempt because she'd been studying Florida materials and had no idea Louisiana requires a 10-day written acknowledgment of claims and a 40-day response window for most routine claim inquiries. Another area people underprepare for is the anti-rebate and anti-twisting provisions. Louisiana is aggressive about enforcement here. The exam will test whether you understand that offering to refund part of the premium as an inducement is illegal, and the distinction between that and a legitimate policyholder discount. Getting these wrong is easy because the language in the answer choices is deliberately close to real-world practice.
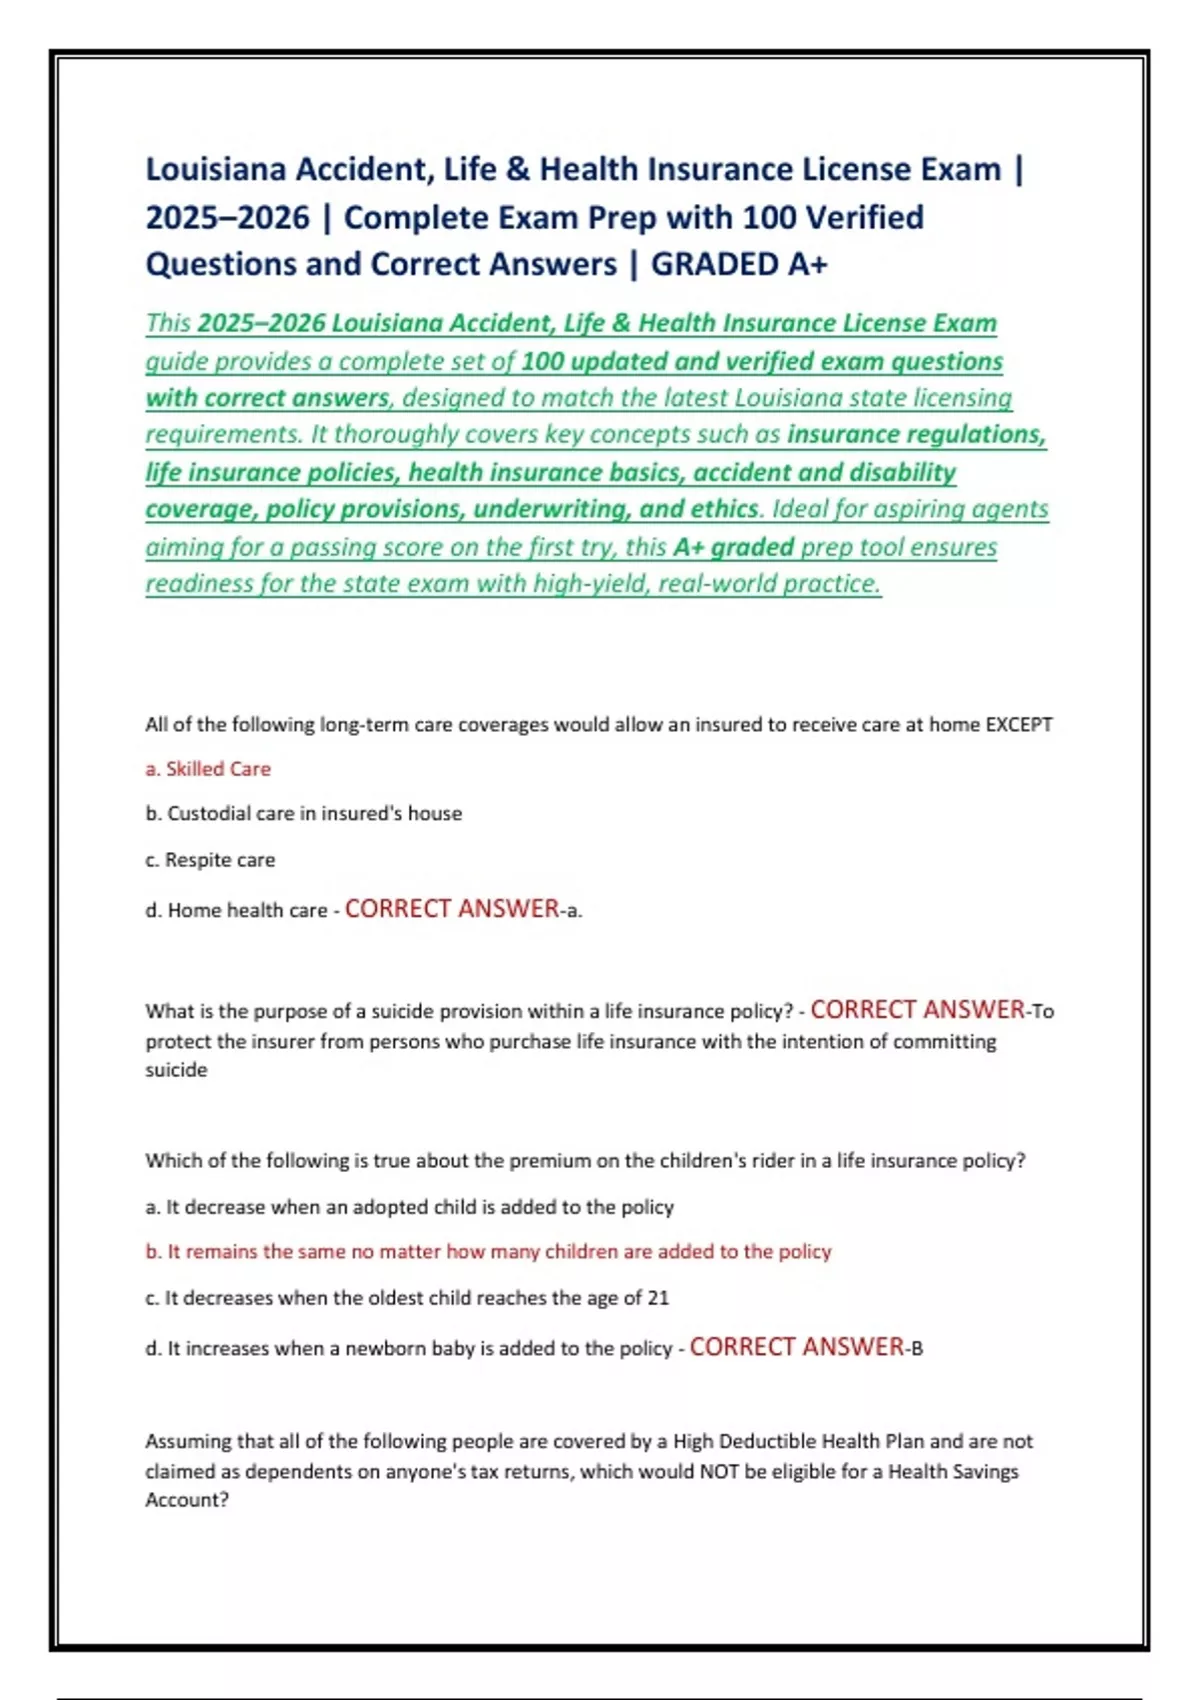
Get the Full Details
The Real Problem No One Talks About
The biggest hurdle isn't the exam content. It's the background check and fingerprinting that happens in parallel. After you pass the exam, you still need to submit fingerprints through Idology or a similar provider, wait for the FBI and state clearance, and then apply for your actual license through the ELI system. The whole administrative tail end typically takes three to four weeks, sometimes longer if there's a mismatch in your name or Social Security number between your exam registration and your application. I ran into a specific issue last year where an agent had passed his exam under a nickname he'd used for most of his adult life. His driver's license said Robert but his exam registration was under Bob. The DOI rejected his initial license application without much explanation. He spent another two weeks gathering documentation proving the name variation, including a sworn affidavit and a copy of his marriage certificate showing the legal change. The workaround is straightforward, but nobody mentions it until it happens to you. Use the exact legal name on every form from the very first step. There's also the matter of Continuing Education requirements that hit you immediately after licensing. Louisiana requires 24 hours every two years, including a specific anti-fraud module and a course on Louisiana insurance law. New agents often assume they have a full two-year grace period. They don't. If your license is issued after July 1st, you might only have a short window before your first CE deadline lands. I've seen agents miss this and get their license suspended within six months of earning it.
Study Strategy That Actually Works
The most effective approach isn't re-reading textbooks. It's taking practice exams under timed conditions and reviewing every wrong answer until you understand why the correct choice is right. Most people skim past their mistakes. I tell them to write down the reasoning for each incorrect answer they pick. Within three or four practice tests, the pattern of your errors becomes obvious and you can target your weak spots precisely. For the Louisiana-specific content, read the actual statutes rather than relying solely on your course material. The DOI publishes the relevant insurance code sections, and several questions pull directly from specific regulatory language. If your course says a certain timeframe applies to claims handling, check the statute yourself. You'll find the exact wording and avoid surprises on exam day. The bottom line is that the Louisiana Insurance License Exam is passable with focused preparation, but the administrative process around it has enough quirks to derail people who aren't paying attention. Verify your course provider, use your legal name everywhere, study the state-specific regulations, and budget extra time for the fingerprinting and application steps. That's how you get licensed without wasting months on avoidable problems.