Filling Out Louisiana Non Resident Income Tax Instructions
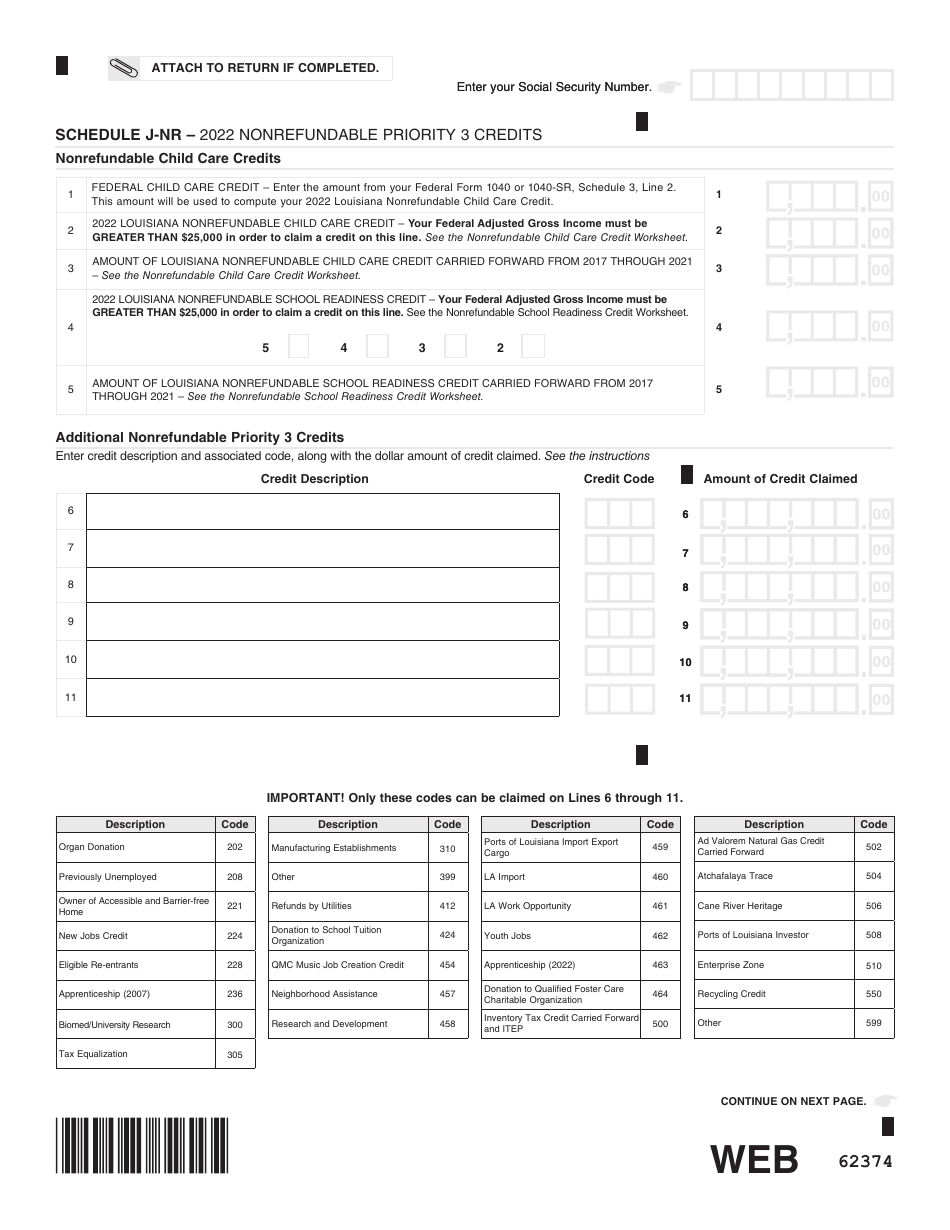
You earned money connected to Louisiana but don't live there. That triggers a filing requirement, and the state wants a cut of the Louisiana-sourced portion only. Most people who run into trouble do it because they try to apportion blindly without tracking where each dollar was actually earned or where each transaction closed. The form you will most likely see is IT-203, the Nonresident and Part-Year Resident Income Tax Return. If you lived in Louisiana part of the year and moved out, you file as a part-year resident for the months you were domiciled there and as a nonresident for the rest. Two separate calculations go on that single return. The instructions walk you through the splitting method, which is more arithmetic than you want it to be on a Friday afternoon. Nonresident tax hinges on source rules. Louisiana taxes income that originates from Louisiana activities, not all of your worldwide income. Wages for work you performed inside the state count as Louisiana source. Rent from a property in Louisiana counts. A gain on selling Louisiana real estate counts. Interest and dividends from non-Louisiana sources do not count. Business income from a trade or profession carried on in Louisiana counts, and that is where people lose their minds because "carried on" has specific meaning under Louisiana law.
The core mechanism is apportionment. You compute a percentage based on Louisiana activity divided by total activity, then apply that percentage to your total income. For employees, it is usually a straightforward days-worked or mileage-based split. For business owners, it can get ugly fast. I handled a situation last spring where a plumbing contractor filed as a Louisiana nonresident. He had a home office in Texas, traveled into Louisiana for jobs, and his bookkeeper allocated revenue by invoice date rather than job location. That mistake inflated his Louisiana source income by roughly thirty percent. The fix required pulling the job tickets, noting which property each service was performed at, and rebuilding the apportionment numerator from the field records instead of the cash receipts log. It took me about three hours of back-and-forth with his scheduler to get accurate data. I submitted the corrected IT-203 with a statement explaining the revision, and the department accepted it without prompting an audit notice. That does not mean the department never checks. It just means keeping granular job records upfront saves you from scrambling later.
Where the calculation actually breaks down
People assume the apportionment fraction applies uniformly across every line item. It does not. Louisiana treats different income categories differently. Compensation income uses a separate numerator and denominator from business income. Rental income sits in its own bucket. Capital gains follow their own sourcing rules. You cannot lump everything into one apportionment fraction and call it done. The instructions list these buckets explicitly, and skipping that separation is the single most common error I see on review. Another trap involves the SUTA credit. Louisiana gives a credit for income taxes paid to other states, but the credit is limited to Louisiana tax attributable to the same income. If you earned wages in two states, you can claim a credit against Louisiana tax only for the Louisiana portion of the wages. Claiming a full credit for taxes paid to another state on the same dollars will trigger a correction. I once saw a taxpayer claim a credit for Mississippi tax on wages earned entirely in Louisiana. The department adjusted it within six weeks, and the taxpayer owed interest from the original due date. Keep your credit schedule tight. Reciprocal agreements exist with Mississippi, Arkansas, and Texas for certain situations, but they do not erase the filing obligation. They change who gets taxed on what. If you live in Texas and work in Louisiana, Louisiana still expects a nonresident return for Louisiana-source wages, even though Texas does not tax that income. The reciprocal arrangement mainly affects withholding mechanics, not the underlying filing duty. Do not skip the Louisiana return because your employer stopped withholding. The department does not care about your employer's withholding choices. It cares about what you owe based on source.
Get the Full Details

What the form actually asks you to do
Start by determining your filing status and residency period. If you moved into or out of Louisiana during the year, you need to date-stamp every entry. The instructions include a section on determining part-year status, and the worksheets there force you to separate income by period. Do not skip those worksheets. The department's audit software cross-checks the entries automatically, and mismatches get flagged within days of submission. Next, identify your Louisiana source income. Pull payroll statements, 1099s, lease agreements, and closing documents. Match each item to a specific Louisiana activity. If a payment covers multiple states, apportion it. The instructions provide default methods, but default methods are not always optimal. If you have actual records that more accurately reflect where the work happened or where the property sits, use those. Louisiana permits more precise allocation when you can document it. For business income, compute the apportionment fraction. Louisiana generally requires a single-sales-factor method for most nonresident business income unless you qualify for an alternative. The numerator is Louisiana gross receipts. The denominator is total gross receipts from all states. Multiply your total business income by that fraction to get Louisiana taxable business income. Then apply the Louisiana tax rate to that amount. If you have losses in Louisiana, the fraction still applies to your total loss, and you may generate a negative Louisiana source amount that offsets other Louisiana income. The instructions are explicit about netting losses against gains within the same category before moving to the next category.
Withholding and estimated payments
If Louisiana withholding was already taken from your wages, you do not need to pay again. The withholding applies as a credit against your final liability. But withholding on Louisiana wages does not cover Louisiana-source rental income or business income. You may need to make estimated tax payments if you expect to owe more than the withholding covers. The threshold for required estimated payments is the same as the federal rule, which is currently 90 percent of the current year tax or 100 percent of the prior year tax, depending on your adjusted gross income. Louisiana conforms to the federal adjusted gross income figure, so your federal AGI carries over directly to the Louisiana return. Estimated payments can be made quarterly. Missing a deadline adds penalties and interest, and the penalty calculation starts from the due date, not from when you eventually pay. Set a calendar reminder for April 15, June 15, September 15, and January 15 if you are required to estimate. I have seen too many professionals treat quarterly deadlines as suggestions. They are not.
Filing options and processing times
You can file electronically or by mail. Electronic filing is faster and less likely to suffer data-entry errors from transcription. The Louisiana Department of Revenue offers e-file for IT-203 through approved tax preparation software. Paper filing takes longer, usually four to six weeks for a first-time return without issues. If you owe money, electronic payment reduces the chance of a missed payment posting. The department posts payments to the wrong account occasionally, and a paper check mailed to Baton Rouge can sit in a queue for weeks before it clears. Keep a copy of everything. Receipts, worksheets, correspondence, and the final signed return. The department can assess additional tax up to three years after the filing date, and sometimes longer if they find a substantial omission. I recommend retaining documents for at least six years, because interstate compact disputes and reciprocal credit challenges tend to surface later rather than sooner.
When to seek professional help
Simple wage income from a single employer who withheld correctly is straightforward. You fill out the forms, attach the W-2, and move on. Multi-state business income, mixed personal and business use of a Louisiana property, pass-through entities with operations in three or more states, and transactions involving both gain and loss across categories are the scenarios where DIY filing becomes risky. The Louisiana instructions are detailed, but they are not exhaustive for every edge case. If your situation involves any of those complications, a licensed CPA or tax attorney familiar with Louisiana source rules will pay for themselves in avoided adjustments and penalties within a single filing season. The department publishes the current IT-203 instructions on its website. Download the package, read the source rules section first, then work through the worksheets in order. Do not jump to the payment section before you finish the apportionment calculation. The numbers on the later pages depend entirely on the earlier ones, and fixing them after you have already filed an amended return wastes time that you could have saved by being careful the first time around.