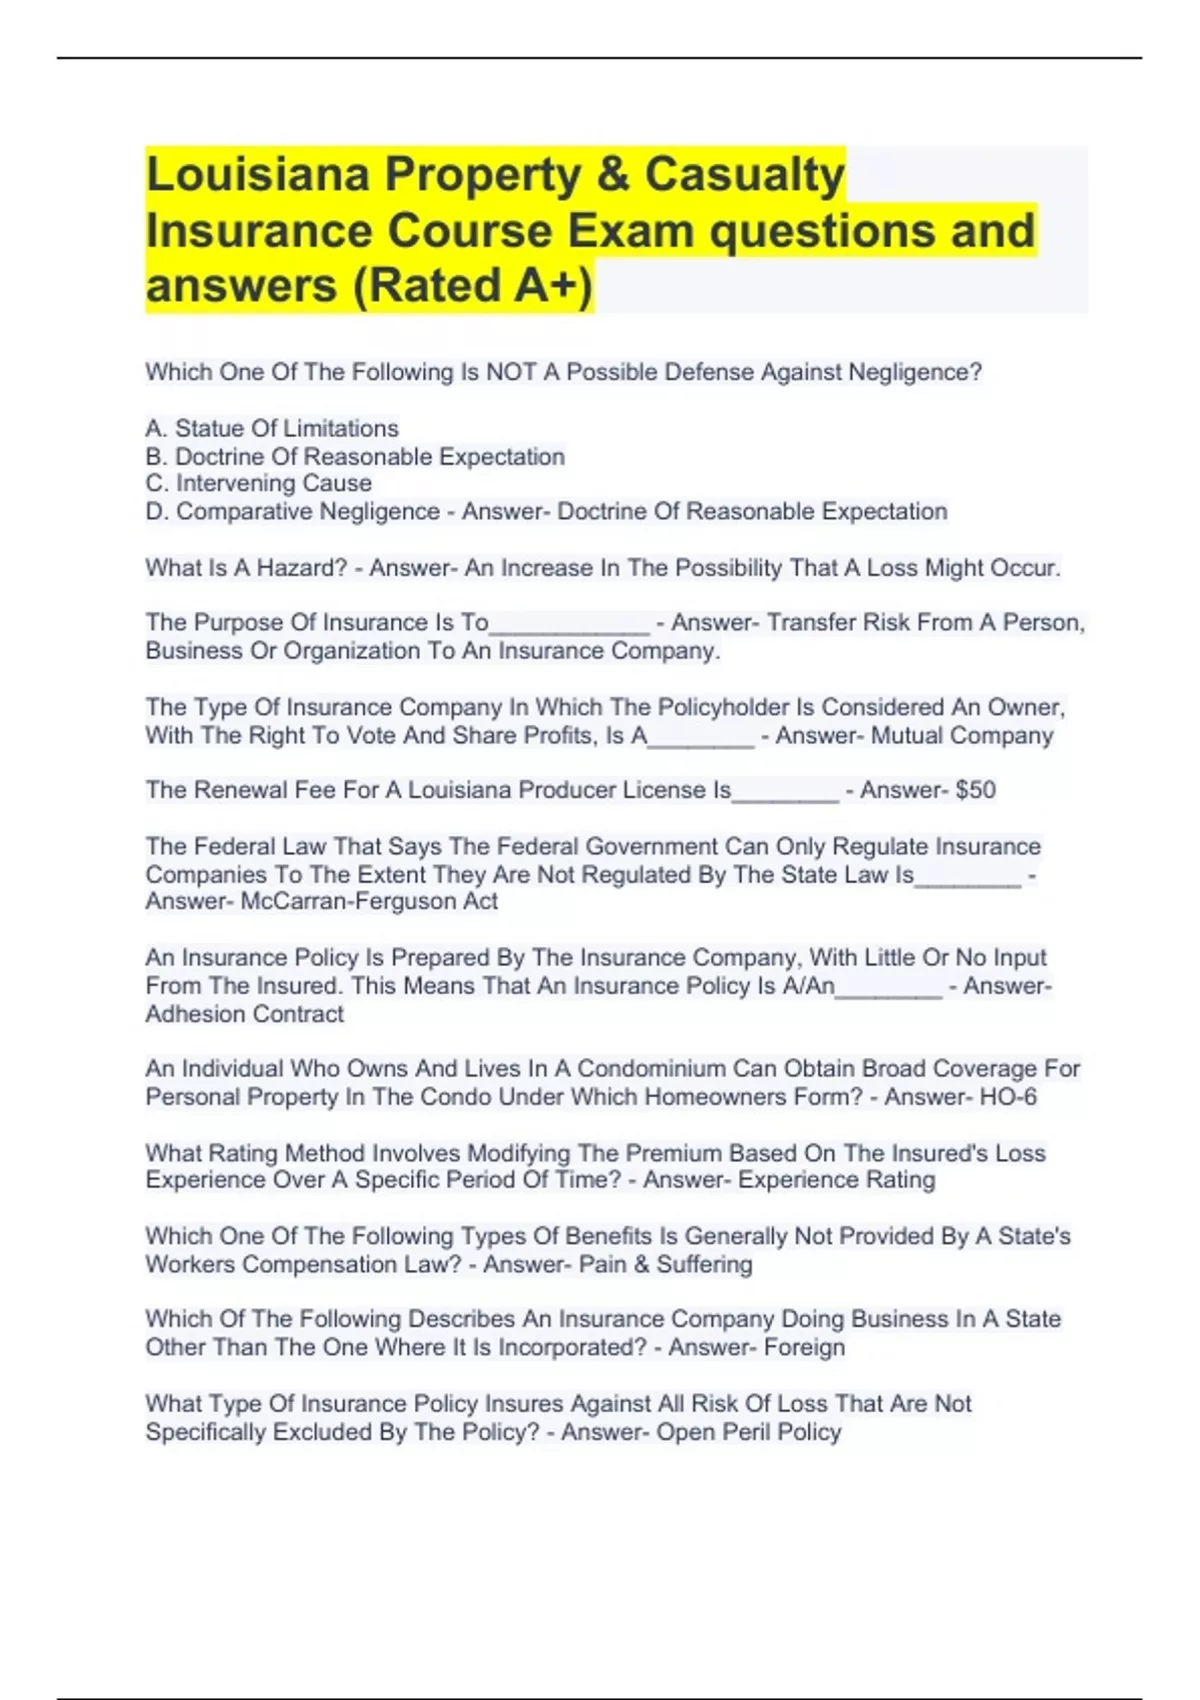
What You Actually Need to Know Before Taking the Louisiana Property And Casualty Insurance Exam
The exam is 100 questions, two hours, and you need a 60% to pass. That sounds generous until you realize half the questions are scenario-based word problems designed to test whether you can read carefully, not whether you memorized definitions. I failed my first attempt by burning through the easy recall questions in forty minutes and then spending seventy-five minutes tripping over the fact that the question asked what the agent should do LAST, not FIRST. That took me three weeks to recover from financially. Here is how the exam actually breaks down. About forty percent covers general insurance principles—concepts like indemnity, subrogation, proximate cause, and the duties of good faith. Another thirty percent is dedicated to property coverage, which means dwelling policies, homeowners forms, commercial property, and inland marine. The remaining thirty percent is casualty: liability, auto, commercial general liability, workers compensation, andErrors and Omissions. The state of Louisiana also tacks on specific provisions from its own insurance code, so you cannot study entirely from generic national prep materials. You need something that addresses Louisiana's unique rules on things like the claim settlement practices section of the Louisiana Insurance Code. One thing nobody warns you about is the way the exam tests your ability to distinguish between a condition and a promise. A condition is something that must happen before coverage triggers. A promise is an obligation the insurer undertakes. The difference shows up in questions about warranties, representations, and concealment, and the answer choices are deliberately close. I once marked a question wrong because I assumed a policy provision was a condition when it was actually a promise, and that one question cost me my passing score by one point.
For studying, the most practical path is to combine a national prep course like preppade or ExamFX with the Louisiana-specific study guide from Pearson VUE. Do not skip the Louisiana portion. The national materials cover subrogation limits and claims timelines, but they do not cover the Louisiana requirement that insurers provide a written explanation of denial within thirty days after receiving proof of loss. That specific timeline appears on every exam I have seen someone take. When you schedule the exam, you take it at a Pearson VUE testing center. You bring two forms of identification, one with a photo and one with your signature. If your signature ID is missing or expired, they will not let you in, and you forfeit your fee. I learned this by watching a woman get turned away at the door on a Tuesday morning while I waited outside with my coffee. She had a library card and an expired passport. Bad combination. The retake policy allows you to retake the exam after thirty days, and you can take it again immediately if you fail by fewer than five questions on a second attempt, though that policy has shifted a couple of times over the years. Check the current rules on the Louisiana Department of Insurance website before you register. The information there is more current than any prep book.
If you are working and studying at the same time, which most people are, dedicate six to eight weeks of consistent review. Two hours a day, five days a week, is enough to cover the material thoroughly without burning out. Use practice exams to identify weak areas rather than to boost your confidence. A score of seventy percent on practice tests means you are probably going to pass, but only if your weak areas happen to be minor topics rather than coverage fundamentals. I know someone who scored sixty-eight percent on practice exams and passed on the real thing because his weak area was commercial lines, which only made up about ten questions on the actual exam. That is luck, not skill, and you should not plan for luck. The biggest waste of time I see people do is rereading textbooks passively. It feels productive. It is not. You need to answer questions, review why each wrong answer is wrong, and rebuild your understanding from those mistakes. Flashcards work for definitions and timelines. Practice questions work for everything else. There is no official study schedule released by the state, and there is no mandated prep course. The Louisiana Department of Insurance does not require you to take a specific class before sitting for the exam, which means you are responsible for your own preparation quality. Some agents take sixty days to study and pass. Some take six months and still struggle because they rely only on memorization instead of understanding how policies interact with state law. The difference is usually whether they practice with scenario questions or just highlight text.
Get the Full Details
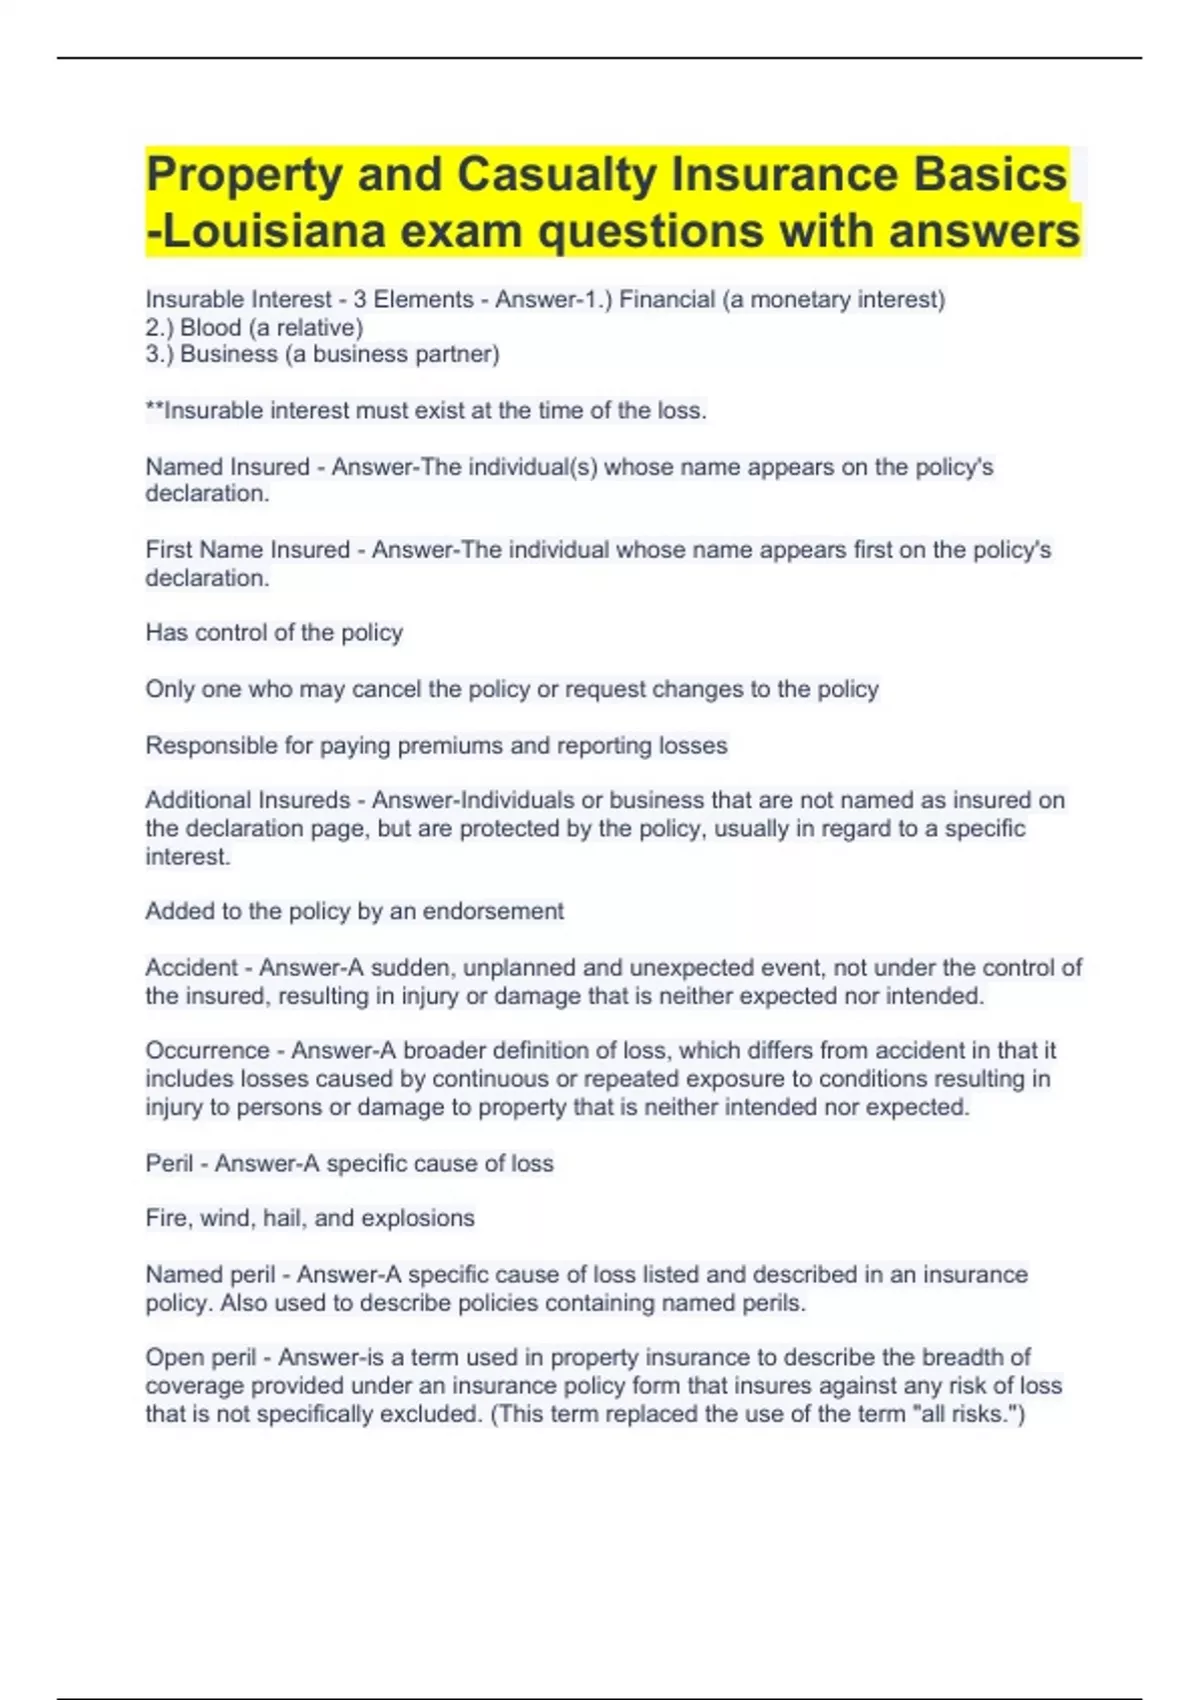
If you want a direct resource, the Louisiana Department of Insurance publishes the candidate handbook on their website, which includes the exact content outline and the current fee structure. The exam fee is one hundred and fifty dollars as of the last update I have on record. Payment is required at scheduling through Pearson VUE. Study guides are available through the major providers, and I recommend picking one that includes at least two full-length practice exams with detailed explanations for every answer choice.