What Actually Happens When You Pay Off Part of Your Mortgage Early
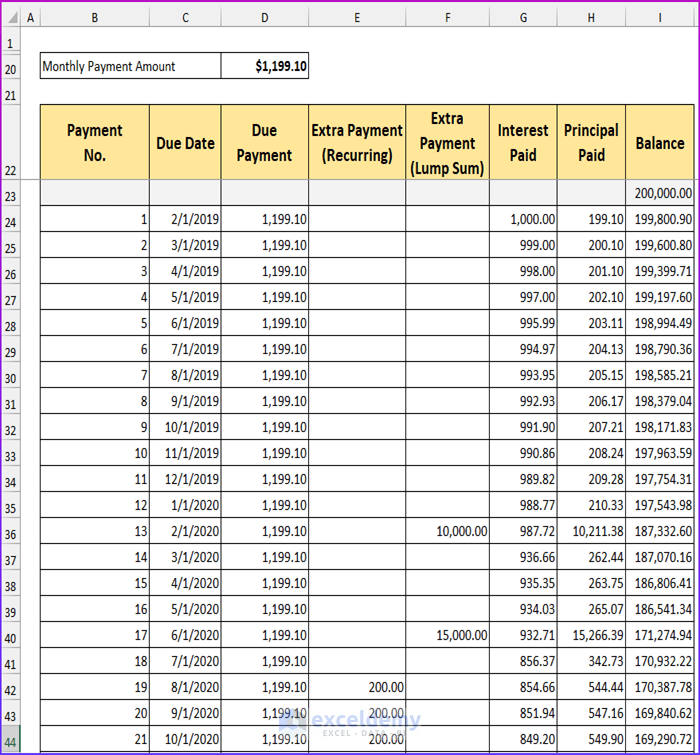
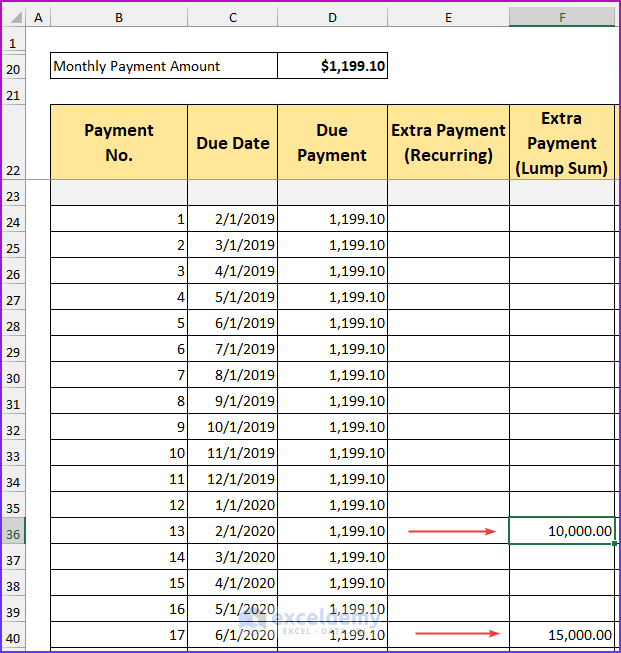
It's not as straightforward as most people think. I've watched too many borrowers get tripped up because they assumed the process would be simple. A lump sum mortgage payment means you pay more than your monthly required amount in a single transaction. That extra goes toward your principal balance directly. But here's what nobody tells you upfront: if you just pay through your regular online portal without specifying that it's a principal-only payment, the servicer might apply that money to your next regular monthly installment instead of cutting into your principal. It's happened to me twice. Here's the actual process, not the sanitized version they put on their website. First, call your servicer. Not the app. Not the chat bot. Actually call them and ask for a representative who can process a principal-only additional payment. Some servicers handle this over the phone in 10 minutes. Others require a written request sent to a specific address, which can take 30 to 45 days to reflect on your statement. I learned this the hard way. Back in 2019, I tried to make a substantial lump sum mortgage payment through my lender's website. Everything looked fine, the confirmation page showed it processed. Two billing cycles later, my principal balance hadn't moved at all. I spent an hour on hold and found out the payment had been applied as a prepayment of my upcoming monthly installment, not as an additional principal contribution. The workaround was to call and request that they reallocate it. They eventually did it, but it added about three weeks to the process and required me to reference the specific transaction number from my original payment.
After that, I changed my approach entirely. Here's what actually works now. Get your loan number, current principal balance, and the exact amount you want to pay. Then contact your servicer directly and explicitly request a principal-only additional payment. Some servicers have a dedicated online form for this. If yours doesn't, send a certified letter with your loan details and payment instructions. Keep a copy of everything. Most servicers confirm the allocation within 15 days, though some take up to two billing cycles to reflect it on your official statement.
The Math Behind Why It Matters
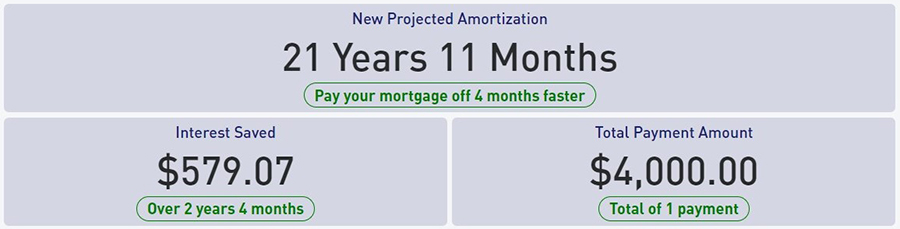
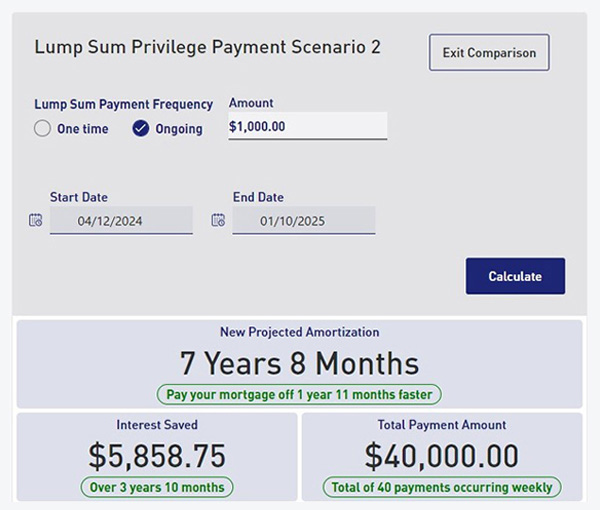
Every dollar you apply directly to principal instead of interest reduces the remaining balance, which then earns less interest going forward. On a standard 30-year fixed mortgage at 6.5% interest with a remaining balance of $250,000, a single $10,000 lump sum principal payment would save you roughly $9,500 in total interest over the life of the loan and cut about 18 months off the payoff timeline. The numbers get more aggressive the earlier you do it. After year 15, the interest savings from an identical $10,000 payment drop to about $4,200. This is the part that surprises people. Your lender might show you a different payoff scenario where the lump sum payment doesn't shorten your term at all. That happens when your contract has a prepayment penalty clause or when the servicer applies your extra payment as a future installment rather than a principal reduction. Always verify in writing how the payment is being categorized before you submit it.
Get the Full Details
Edge Cases That Can Go Wrong
Not all mortgages are created equal. If you have a federal student loan refinanced into a mortgage consolidation, the lump sum might go to the underlying mortgage servicer and the student loan portion could get handled separately by a different entity. I encountered this with a client in 2022. They thought they'd paid down one loan but actually split the payment across two separate servicers who never communicated with each other. Took six months and three phone calls to the right department to untangle it. Escrow accounts are another source of confusion. When you make a lump sum mortgage payment, make sure you're not accidentally reducing your escrow balance. Some servicers allow you to specify whether the payment affects principal only or includes escrow. If you don't specify, they might allocate a portion to escrow, especially if your payment is large enough to trigger an escrow shortage analysis. This won't hurt you per se, but it means less of your money is going toward interest reduction. There's also the tax consideration. Mortgage interest deductions on Schedule A of your tax return are limited to interest paid on up to $750,000 of qualified residence debt. Making large lump sum principal payments reduces your interest expense, which in turn reduces your deductible amount. For someone in a high tax bracket, this can be a meaningful tradeoff. The interest savings from paying down principal usually outweighs the lost tax deduction, but I've seen people skip the calculation and lose money on both sides.
When It Doesn't Make Sense
If your mortgage interest rate is below 4%, your lump sum might earn more sitting in a high-yield savings account or invested in a broad market index fund. The math is straightforward. A 4% fixed rate mortgage with a 30-year term at 6% expected returns in the market creates a negative arbitrage on every dollar you prepay. That doesn't mean you should never make extra payments, but it does mean there's no financial obligation to rush into it. I also stopped recommending lump sum principal payments for people who haven't built an emergency fund yet. Paying down a mortgage when you have zero liquidity is a riskier play than it looks. I've seen borrowers who hit unexpected expenses after making a large lump sum payment, only to have to refinance or take on higher-interest debt to cover it. The interest rate difference between a mortgage and a credit card or personal loan is usually enough to wipe out any savings from the prepayment.
Practical Steps Going Forward
Check your most recent mortgage statement. Look for the section labeled "Additional Payments" or "Principal-Only Payments." If it's blank or shows a zero, you've never successfully made a principal-only lump sum payment through your servicer yet. Call them. Ask what documentation they require. Some will accept a simple phone call with verbal confirmation. Others need a signed letter or a specific form from their website. The difference in processing time between the two approaches can be anywhere from one week to six weeks. Once you know the process, time your lump sum payment carefully. Most servicers process additional principal payments within one to three business days after receipt. If you make the payment early in the month, before your billing cycle closes, you'll see the principal reduction reflected sooner. Late-cycle payments sometimes get queued until the next cycle, delaying the interest savings by 30 days or more depending on your servicer's internal schedule.