How Extra Mortgage Payments Actually Work
Most people think throwing extra money at their mortgage is simple. It's not, because lenders and servicers have a vested interest in keeping payments structured. If you just send in an extra check without doing this right, the servicer will likely apply it to your next regular payment cycle as a prepayment, which does nothing to reduce your principal balance or shorten your term. I've seen this happen with my own loan, and I learned the hard way.Making Extra Payments On Mortgage: The Real Mechanics
When you make an extra payment, there are two destinations that money can go. First, it can be applied as a prepayment credit to your upcoming monthly installment. This is the default behavior for most servicers, and it's worthless for anyone trying to pay off their loan faster. Second, it can be applied directly to principal reduction. This is what actually matters, but servicers make you work for it. The key mechanism here is called principal-only (PO) designation. You have to actively instruct your servicer to direct your extra payment to principal, not interest or escrow. This isn't always obvious because servicers bury the instructions deep in their portals or require a separate form. Without that designation, your extra payment gets absorbed into the next month's billing cycle and disappears from your perspective. I ran into a specific problem with my refinanced loan in 2019. The online portal had no option to designate a principal-only payment. The help line told me to write "principal only" on the memo line of a paper check, which I did for three consecutive months. Each month, the payment went toward principal, interest, and taxes instead of just principal. The system was misreading or ignoring the memo line entirely. What actually worked was calling the servicer and asking them to set up a recurring extra principal payment through their system, which they then properly tagged. The workaround was never about the payment itself. It was about getting the servicer's backend to handle the designation correctly.
The Practical Steps
Before you do anything, pull your most recent mortgage statement. You need to know your current principal balance, your interest rate, and your remaining term. More importantly, check if your loan has a prepayment penalty clause. Most conventional loans don't, but some government-backed loans and certain refinance products still carry one, usually structured as two to six months of interest. If yours does, making extra payments in a single large chunk could trigger that penalty, which would negate the savings. Next, find your servicer's policy on extra payments. Look on their website for something like "extra payments" or "pay off my loan." Call them if you can't find it. Ask specifically: can I make a principal-only payment? How do I designate it? Do you have a minimum increment? Most servicers will tell you right away, but the ones that are difficult about it tend to be the ones where the online system is the most confusing, which is its own data point. Once you know the rules, pick a payment amount and schedule. You can go one-time or recurring. A common strategy is the bi-weekly method, where you pay half your monthly payment every two weeks. This results in thirteen full payments per year instead of twelve, because you're splitting each monthly payment in half and paying every two weeks. That one extra payment per year goes straight to principal if designated correctly, and it shaves years off a 30-year loan. Another approach is rounding up. Pay $1,650 instead of $1,612 every month. The $38 goes to principal. Small amounts add up when they're consistently applied to principal rather than interest.
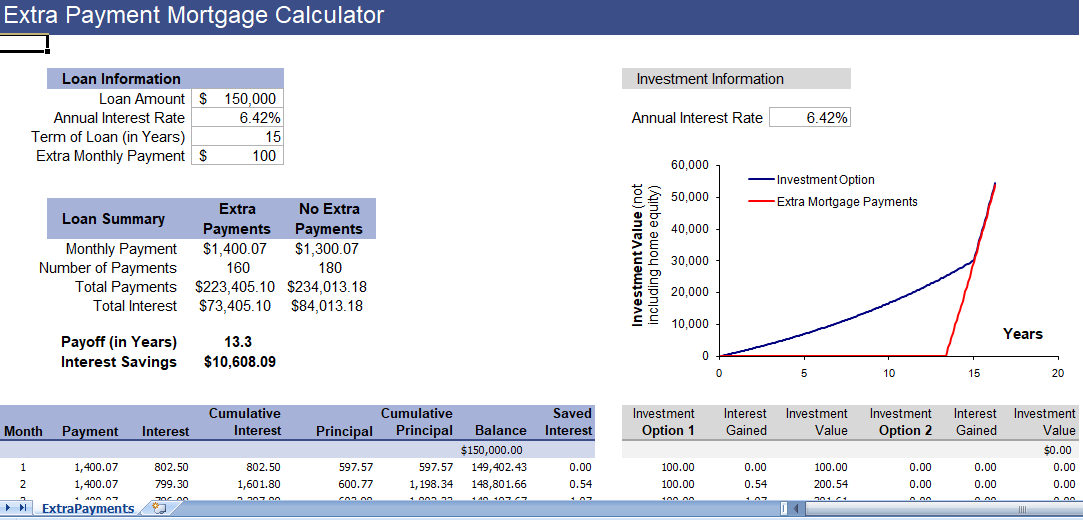
The math is straightforward enough that you don't need a tool, but if you want to see the impact, any mortgage calculator with an extra payment field will show you the reduced payoff date and total interest savings. For a typical $350,000 loan at 6.5% over 30 years, adding just $100 per month to principal saves roughly $42,000 in total interest and cuts about five years off the loan. The numbers are consistent. They don't change based on who you ask or which calculator you use, though different calculators might round slightly differently.
Get the Full Details
Where People Go Wrong
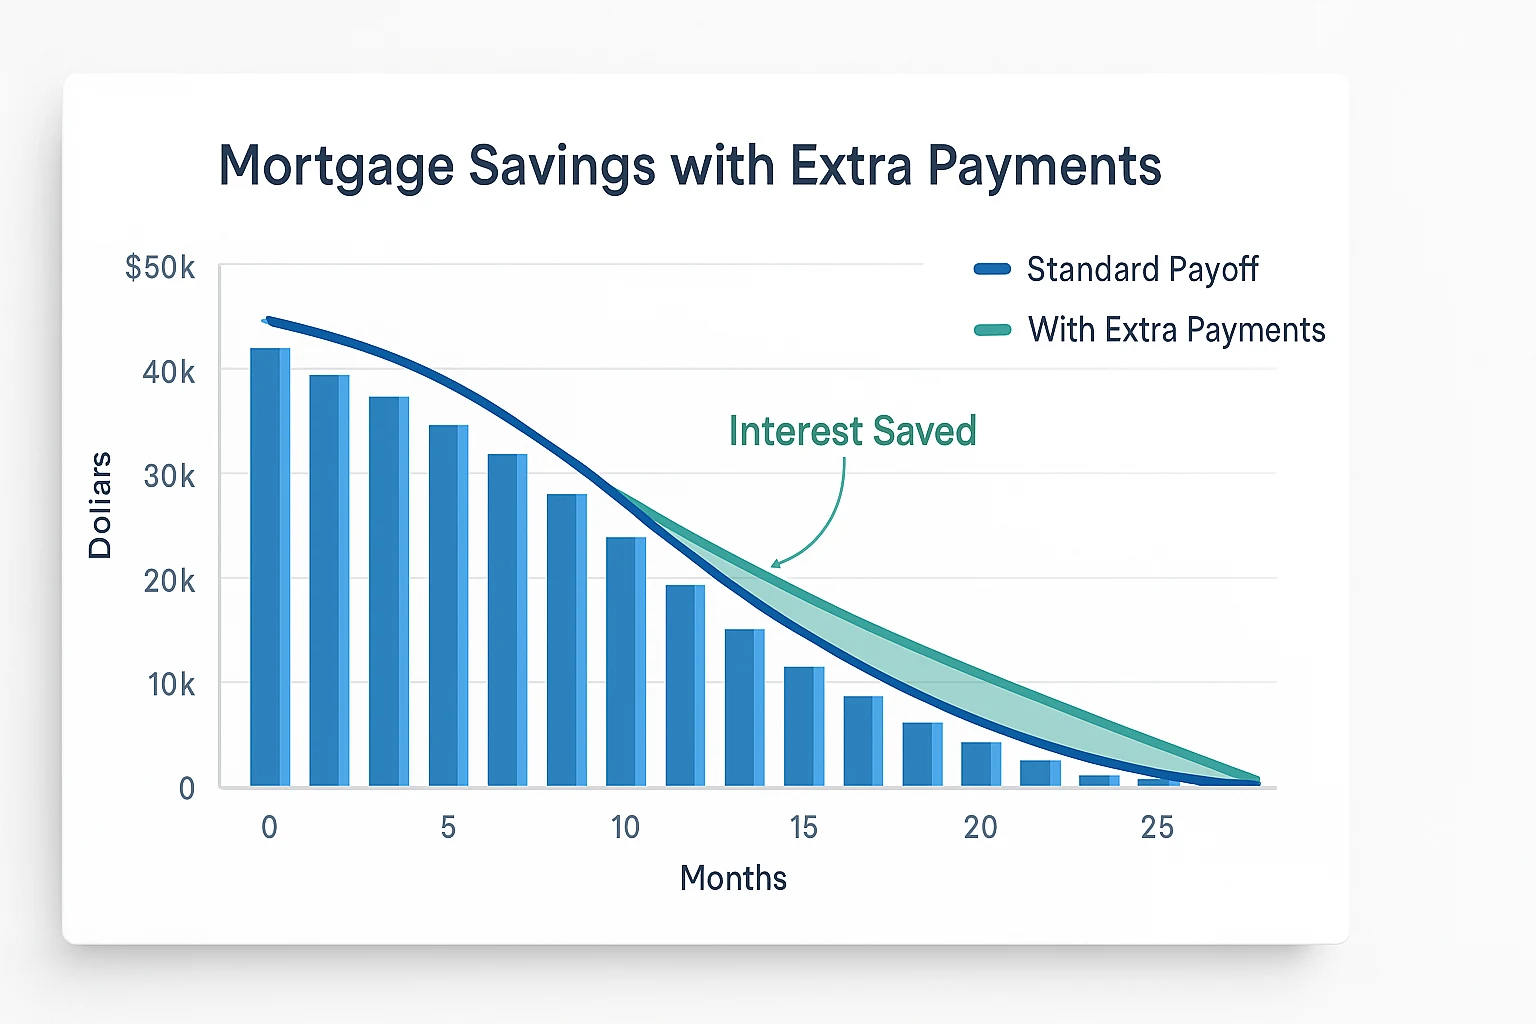
The biggest mistake I see is assuming that any extra payment reduces principal. It doesn't. The servicer applies it according to their default rules unless you tell them otherwise. Some servicers have started adding checkboxes for principal-only designation in their portals, but the ones that don't will happily process your extra payment as a prepayment credit and tell you it's being handled. It's not. Another issue is escrow. If your monthly payment includes taxes and insurance held in an escrow account, an extra payment doesn't touch that portion. Make sure you're calculating your extra amount based on the principal and interest portion of your payment, not the total. If you send extra money meant to cover the full payment amount, the servicer will apply it proportionally across principal, interest, and escrow, which defeats the purpose. There's also the matter of how the extra payment affects your amortization schedule. Each extra principal payment reduces the remaining balance, which means less interest accrues in the next billing cycle. This creates a compounding effect where each additional payment saves you more than the one before it. People sometimes miss this because they only look at the total interest saved over the life of the loan without understanding the mechanics. It's not linear. It accelerates as the balance drops.
A counter-intuitive point that most beginners miss: paying extra on a higher-interest loan saves you more than paying extra on a lower-interest loan, even if the balances are identical. A $250,000 loan at 7% saves significantly more in interest than a $250,000 loan at 5%, because the interest portion of your payment is larger at the start. If you have multiple loans, prioritize the one with the highest rate. The math is unambiguous.
When It Doesn't Make Sense
Extra mortgage payments aren't always the best move. If you have credit card debt at 18% or personal loan debt at 12%, paying down that debt first will save you far more money than accelerating your mortgage. The opportunity cost is real. Similarly, if you don't have an emergency fund, tying up extra cash in home equity is risky. Home equity is illiquid. You can't access it without refinancing or a home equity loan, both of which come with their own costs and qualification requirements. There's also the tax angle. Mortgage interest deductions matter less now that the standard deduction is higher for most people, but if you itemize and your loan balance is above the new $750,000 limit, you may be losing deductions on the portion of interest you could otherwise pay down. Again, the math depends on your specific situation, but it's worth checking with a tax professional rather than assuming. If you're close to retirement and your mortgage is nearly paid off anyway, the time value of money changes. A $100 extra payment per month on a loan with five years left saves maybe $300 in total interest over the remaining term. That's a 2.5% return on your money. You'd likely do better parking that $100 in a diversified portfolio or high-yield account, depending on your risk tolerance and timeline.

The Bottom Line
The process itself takes about ten minutes once you know your servicer's rules. The hard part is figuring out the rules and making sure your extra payments are properly designated as principal-only. Set up a recurring extra payment if you can, verify it's being applied correctly by checking your next statement, and adjust if the designation isn't showing up where it should. That's it. The rest is just patience and consistency.