Why most management due diligence gets swept under the rug
You spend weeks running financial and commercial checks, crunching EBITDA, validating the customer base, mapping out competitive positioning. Then you get to management assessment and basically go through the motions because the seller provided a few CVs and you have a deadline to meet. This is where deals quietly get derailed. Not from bad numbers. From misreads on the people running the business. I've seen a $40 million acquisition fall apart three days before signing because the buyer realized the CFO had been falsifying working capital schedules and the GM had no succession plan, just a guy who claimed he'd retire in six months. The commercial and financial due diligence had been immaculate. Nobody had bothered to dig into the actual management depth or governance gaps. It happens more often than you'd like to admit.
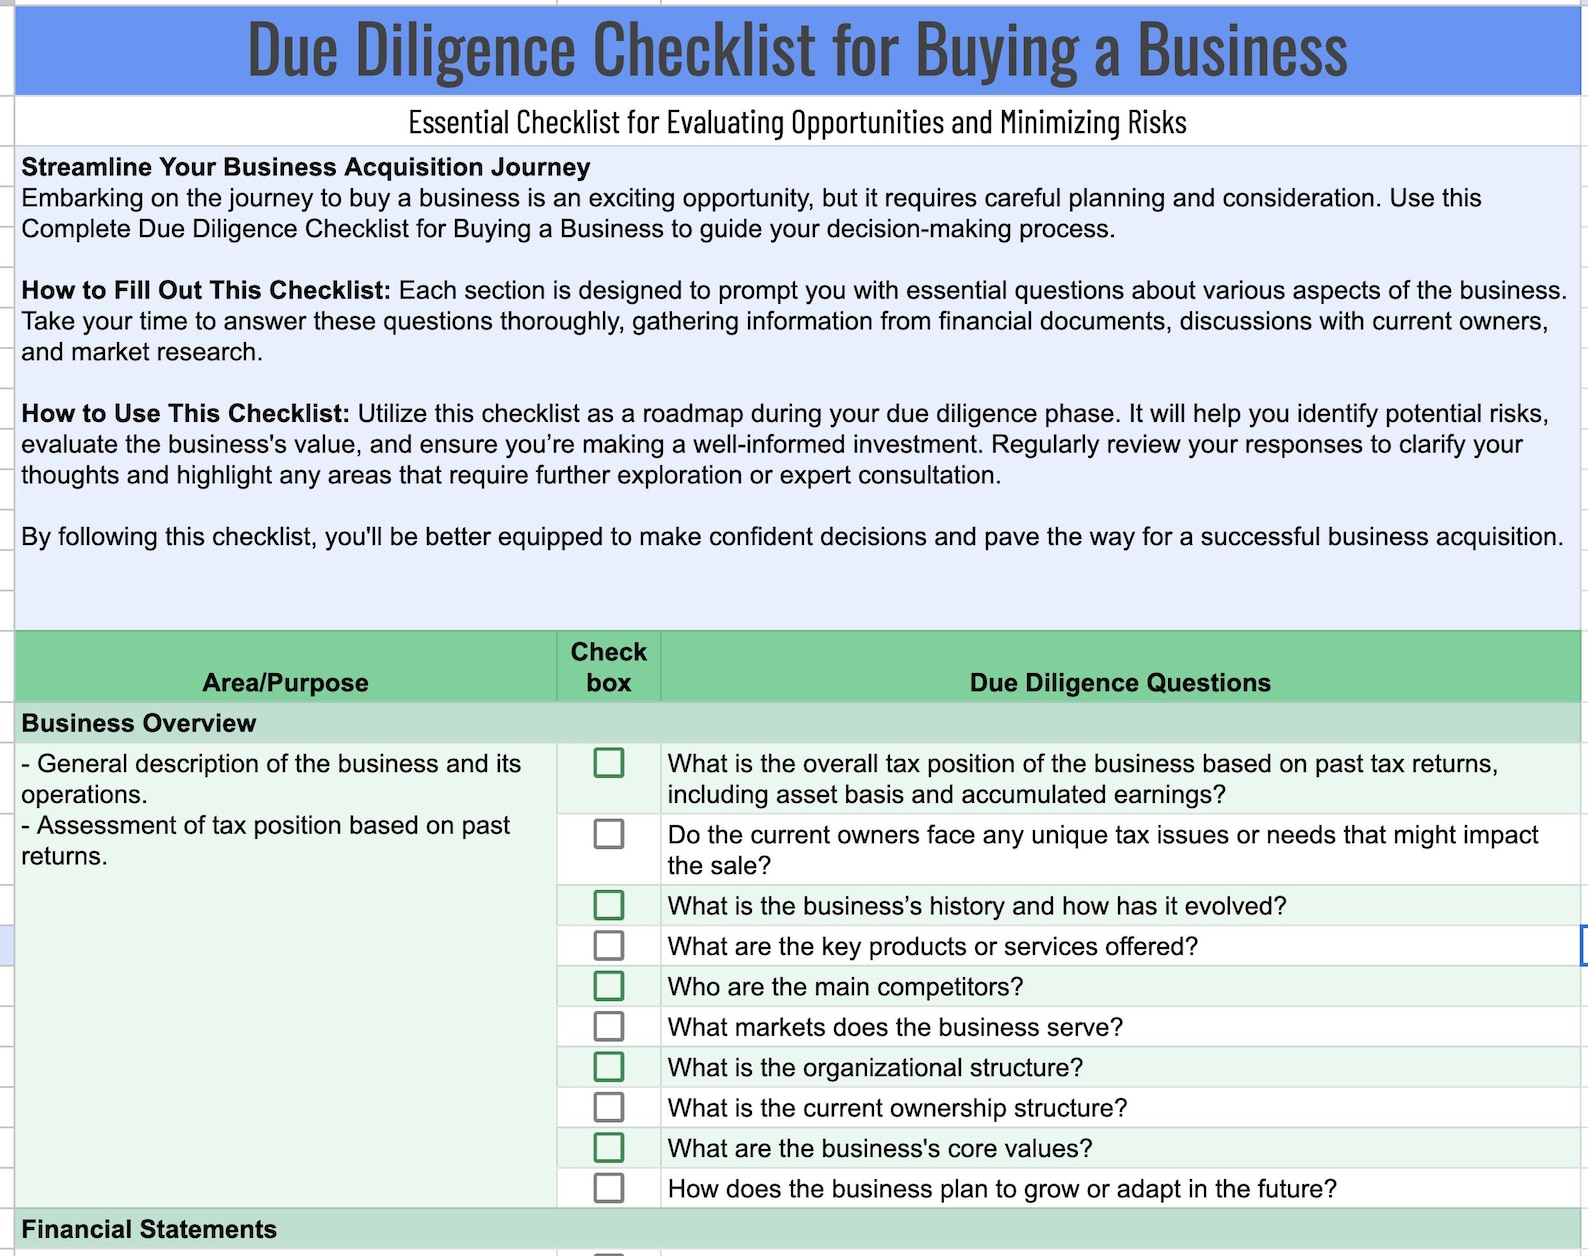
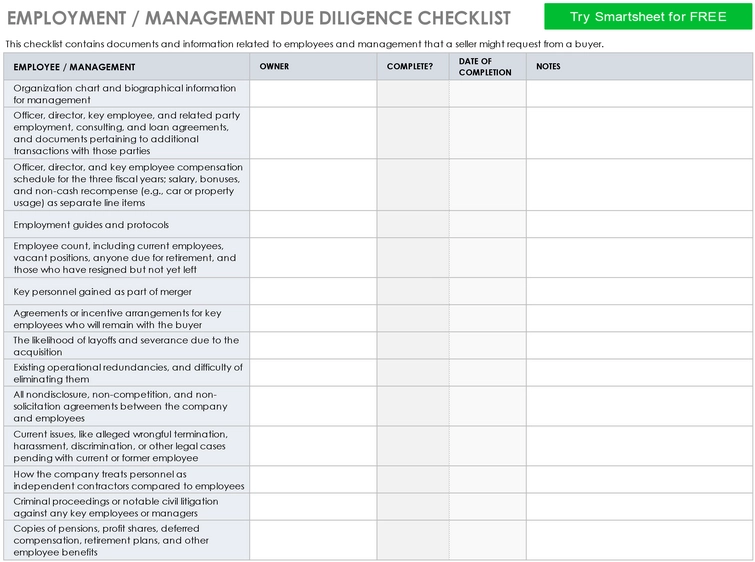
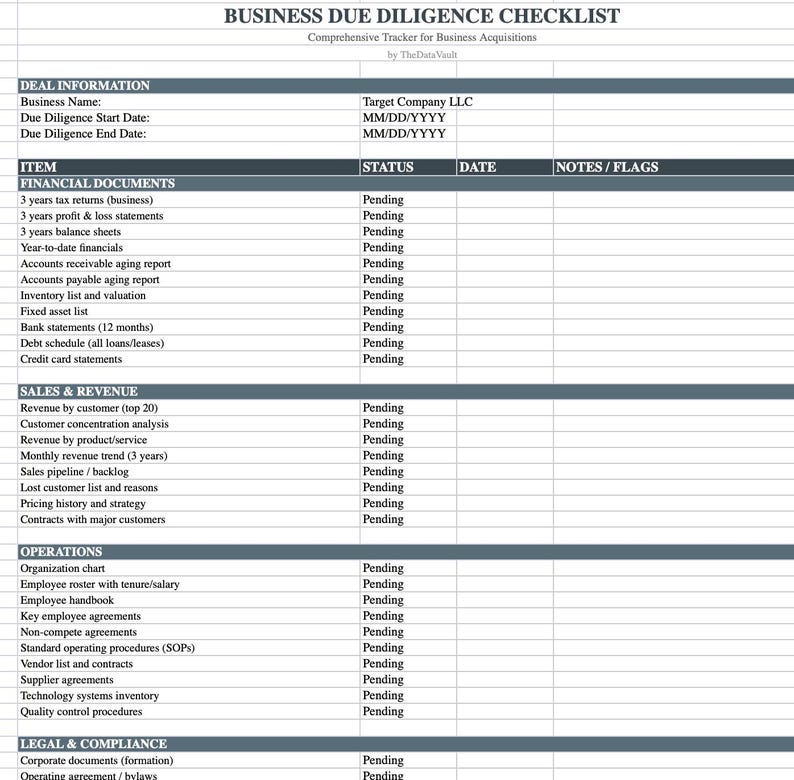
Management Due Diligence Checklist
Here's what I actually use in practice. Not a theoretical framework from a consulting slide deck. The things I check, the things that have tripped me up, and where the real risks hide. Start with the org chart, but don't accept the one the seller provides without verification. Map it against actual reporting relationships, budget authority, and decision-making chains. The public-facing structure usually omits critical gaps. A mid-market company might show five VPs to looking healthy on paper while actually running on three people who are each wearing three hats and one of those hats is "keeping the lights on" without any backup. I once worked a deal where the org chart showed a dedicated Head of Operations. When I dug into payroll and organizational access, that role didn't exist. The GM had been performing the function himself for eight years. This is the gap that kills integration. If you assume the role is filled and it isn't, your post-close plan is built on fiction.
Leadership Team Profiles and Competency Assessment
Review executive and key management biographies, but go beyond tenure and title. Look for patterns. Job hopping without promotion, gaps that aren't explained, roles where the scope seems inflated compared to company size. Cross-reference LinkedIn with actual references and look at board meeting minutes if available. The narrative in a CV is not the reality of performance. Competency mapping matters more than credentials. A CFO with a CPA and twelve years at a large corporation may not have the skillset for a fast-growing private company that needs cash flow management, investor communications, and hands-on systems work simultaneously. Different game entirely. Document the gap between what the role requires and what the candidate demonstrably has.
Get the Full Details

Culture Fit and Organizational Health Assessment
This is the section most people half-ass. Run structured interviews with direct reports, not just the C-suite. Conduct anonymous surveys if the deal is large enough. Look for consistency in responses about decision-making speed, conflict resolution, and retention rates. If half the leadership team says they'd leave tomorrow given the chance, that's your answer regardless of what the CEO told you in the interview room. Red flag: when everyone in the reference check process is a friend, colleague from the same small company, or someone who has something to gain from the deal closing. Independent references matter. Former colleagues from different employers, suppliers, customers, or board members who can speak to how the leadership team operates under pressure.
Succession Planning and Key Person Risk
Every founder-led or small-cap company has this problem to some degree. The question is how severe. Identify every critical role where losing that person would materially disrupt operations. Then assess whether there's an actual successor in place with the skills and institutional knowledge to step up. Documented succession plans are often theater. Look for evidence: has anyone actually been promoted into a critical role from within? What's the average tenure in mid-level management positions? I found one case where the entire engineering organization reported to a single CTO who had been there fifteen years. Zero documented knowledge transfer, no second-tier engineering leadership with equal depth. When we offered him an earnout tied to transition, he declined and effectively walked away. The deal required us to restructure the offer and secure his commitment, which changed the economics significantly.
Incentive Alignment and Retention Strategy
Review current compensation structures, equity holdings, and retention agreements. Misaligned incentives are a silent deal killer. If the CEO owns 30% and is set to cash out fully on close, what motivation does he have to perform during earnout or transition? Conversely, if key middle managers have no equity participation and the acquirer plans immediate restructuring, expect mass departures. Retention packages need to be designed around actual behavioral incentives, not just golden handcuffs. Time-based vesting alone keeps people passive, not engaged. Consider performance milestones tied to transition deliverables. But also recognize that money doesn't always solve the problem. Some people want out. Forcing them to stay with aggressive retention packages creates a poisoned environment during integration.
Decision-Making Processes and Governance Framework
How does this company actually make decisions? Is it centralized with one person, or distributed? What's the approval threshold for capital expenditure, hiring, strategic pivots? These questions matter because the acquirer's governance model will likely differ. Friction here creates integration drag that manifests as missed targets and blame-shifting in the first twelve months post-close. Run background checks on the leadership team. Litigation history, regulatory actions, IP conflicts, non-compete enforceability. This isn't about being paranoid. It's about identifying exposure. A key executive with an unresolved IP dispute from a previous venture could create liability for the acquiring company. Non-compete agreements may be unenforceable in certain jurisdictions, which changes your risk calculation entirely. Assess how the target's leadership team will integrate with yours. Not just whether they're competent people, but whether their management style, communication patterns, and decision-making approach will mesh. This is subjective but critical. Two competent teams with fundamentally different operating philosophies will produce a dysfunctional integration even if the financial numbers look perfect.
Conduct joint working sessions before close. Put the target's leadership in rooms with your people and observe the dynamics. Does communication flow naturally? Are there cultural friction points that will escalate during high-stress periods? These signals are difficult to catch through documents alone.
Where this process breaks down
Management due diligence has hard limitations. You can't fully assess leadership quality from a desk. Some problems only reveal themselves under stress. A leadership team that appears cohesive during due diligence may fracture during the first quarter of integration when real operational pressure hits. This is unavoidable. Reference checks are inherently biased toward positive feedback. People rarely give honest negative assessments in writing during an active deal. Anonymous surveys help but have low response rates in small organizations where everyone knows who took them. Direct observation through site visits and working sessions is more reliable but time-consuming and often skipped under deal pressure. The biggest practical constraint is time. Proper management due diligence requires 2-3 weeks minimum for a mid-market transaction, longer for complex organizations. Most deals are pressured into completion timelines that don't accommodate this. The workaround is prioritization. Identify the top five leadership risks and focus deeply on those rather than attempting comprehensive assessment across every function.
Practical execution notes
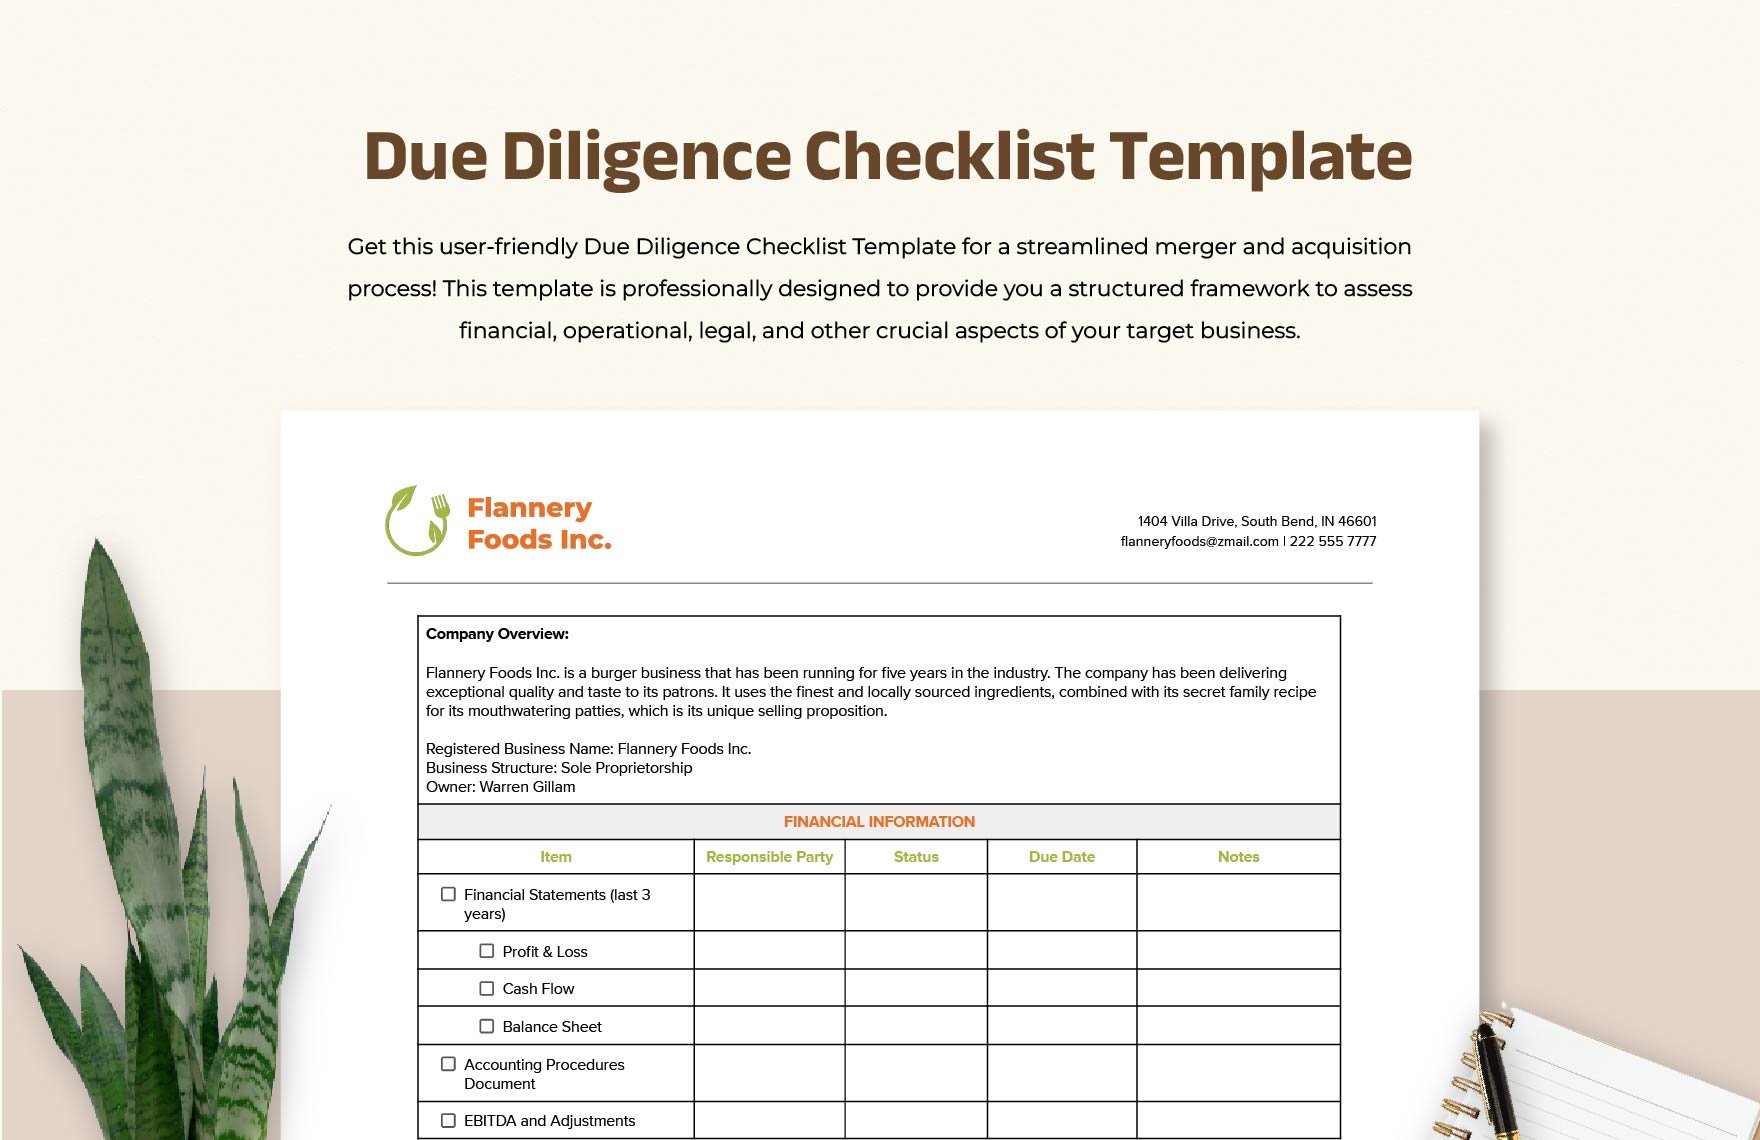
Interview protocol: conduct management interviews separately from seller-sponsored events. Independent scheduling prevents groupthink and gives candidates the space to provide candid responses. Limit each interview to sixty to ninety minutes. Longer sessions produce diminishing returns and increased performance anxiety that skews responses. Data sources: combine multiple inputs. HR records, performance reviews, exit interview summaries, vendor feedback, customer complaints referencing specific executives, board minutes, and direct observation. No single source is sufficient. Cross-referencing three independent data points about a leadership claim is the minimum threshold for reasonable assurance. Documentation: maintain a risk register throughout the process. Score each finding by likelihood and impact. This becomes the basis for deal adjustments, representations and warranties insurance considerations, and post-close monitoring priorities. A qualitative assessment without quantitative scoring is just opinion dressed up as analysis.
The tools you need are straightforward. Excel or a simple database for organizing findings, a standardized interview questionnaire, reference check templates, and a scoring matrix for risk assessment. There's no specialized software requirement that justifies the cost for most transactions. The value comes from the rigor of execution, not the sophistication of the tool. If you're working with smaller deals under $10 million where formal due diligence budgets are limited, compress the checklist to the essential elements: leadership competency verification, key person risk assessment, succession gaps, and culture compatibility. Everything else can be addressed through post-close monitoring and phased integration planning.