What Actually Happens When You Try to Manage Business Taxes
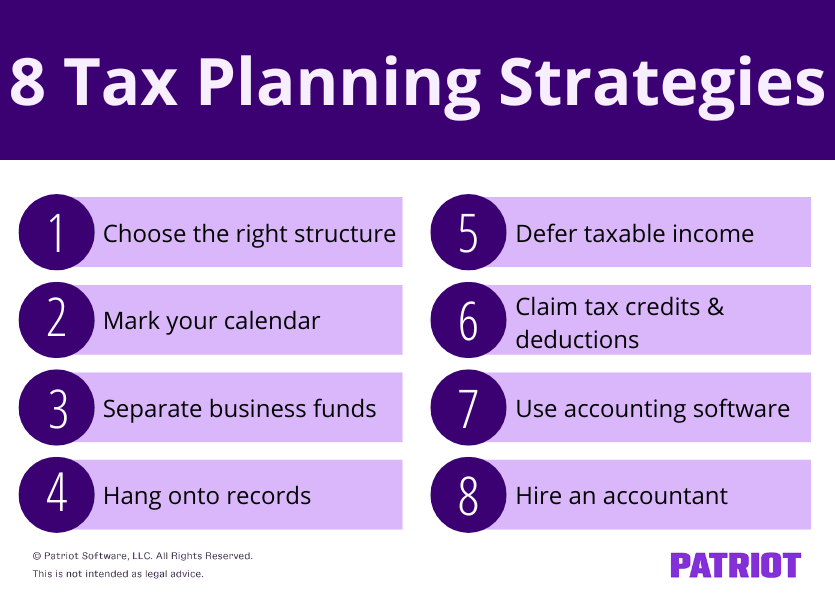
I spent three years working with small business owners who kept making the same mistakes with their taxes. Most weren't evil. They were just confused about how different deductions actually work when you combine multiple revenue streams. One guy had a consulting business and a rental property. He thought he could just subtract expenses from one against the other. That didn't work the way he expected. Management Tax Strategies sound good in theory. In practice, they require understanding how the IRS actually interprets things versus how you interpret things. The gap between those two is where most business owners get into trouble. Or worse, leave money on the table.
Why Entity Selection Changes Everything About Your Tax Situation
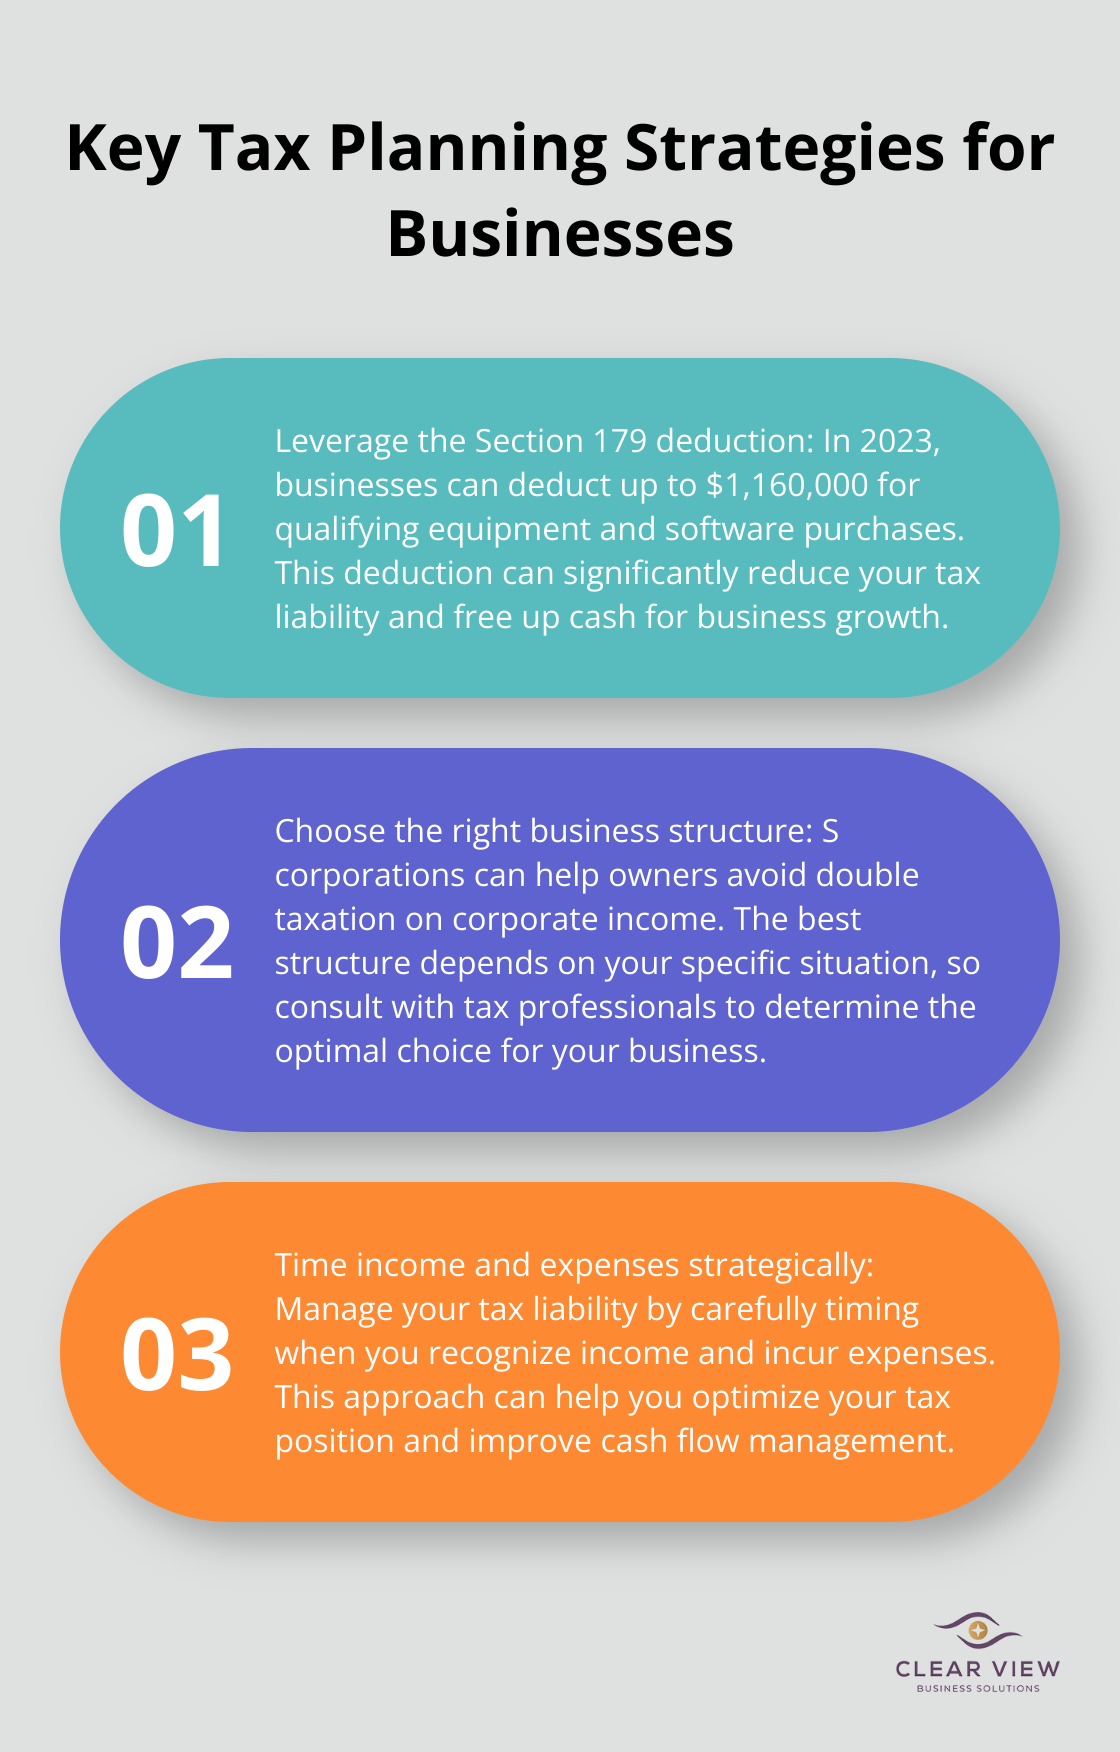
The biggest mistake I see is people picking an LLC or S-corp because their friend recommended it. That friend might have been right for their situation, but your situation is probably different. An LLC by default is a pass-through entity. That means all profits flow to your personal tax return, regardless of whether you actually took the money out of the business. You pay tax on money you never saw. S-corps solve that problem partially, but they create new ones. You have to pay yourself a reasonable salary through payroll. That salary creates employment tax obligations. The remaining profit can be taken as distributions, which don't face self-employment tax. But "reasonable salary" is fuzzy. The IRS has published guidance, but it's guidance, not hard rules. One audit later, your "reasonable" salary looks pretty unreasonable to a revenue agent. C-corps are rarely the right answer for small businesses, but they exist for a reason. Retained earnings get taxed at the corporate level, which is currently 21 percent. That's not terrible compared to individual top rates, but you'll face double taxation when you eventually distribute those earnings. Unless you're planning to reinvest heavily in the business or you're in a high-income bracket, this path usually creates more problems than it solves.
The Depreciation Trap Most People Don't See Coming
Section 179 lets you expense certain assets in the year you buy them instead of depreciating them over time. The limits change annually. For 2024, you can expense up to $1,220,000 of equipment purchases, but that phases out dollar-for-dollar once you buy more than $3,050,000 worth. Bonus depreciation used to be 100 percent. Now it's 60 percent for 2024, dropping 20 percent each year after that. Here's what nobody tells you: using Section 179 on equipment you plan to sell within a few years can trigger recapture. The IRS wants its share of depreciation you claimed but didn't really earn over the asset's full life. If you sell the equipment for more than its adjusted basis, that gain becomes ordinary income up to the amount of depreciation you claimed. It's not a catastrophe, but it's a surprise most people don't budget for. I worked with a landscaping company that bought $800,000 in equipment in one year. They maxed out Section 179. Two years later, they sold half the equipment to upgrade to newer models. The depreciation recapture wiped out most of their expected gain. They'd saved on current taxes but created a bigger problem later. Sometimes straight-line depreciation over the full recovery period is actually smarter, even if it means smaller deductions now.
Get the Full Details
Mixed-Income Businesses Require Layered Strategies
Most modern businesses aren't simple anymore. You might have W-2 employees, 1099 contractors, rental income, investment income, and maybe some side gig money from platforms like Uber or Shopify. Each type of income gets taxed differently. The IRS calls this "mixed income" and it complicates everything. Self-employment tax applies to Schedule C income. That's 15.3 percent on top of your regular income tax. Qualified Business Income deduction under Section 199A can reduce your effective rate, but it doesn't apply to everything. Rental income generally doesn't qualify unless you meet specific active participation tests. Investment income definitely doesn't qualify. Trying to bundle all that together without understanding the boundaries is how people make errors on their returns. One client had an e-commerce store, a small apartment building, and some dividend income. I recommended separating the businesses into different entities not because of liability, but because of tax treatment. The e-commerce stayed as a sole proprietorship for simplicity. The rental property went into an LLC taxed as a partnership so we could allocate expenses properly. The investment accounts stayed personal. This structure let us apply different strategies to each income stream instead of treating everything as one messy pile.
Common Management Tax Strategies That Actually Work
Timing Income and Deductions Strategically
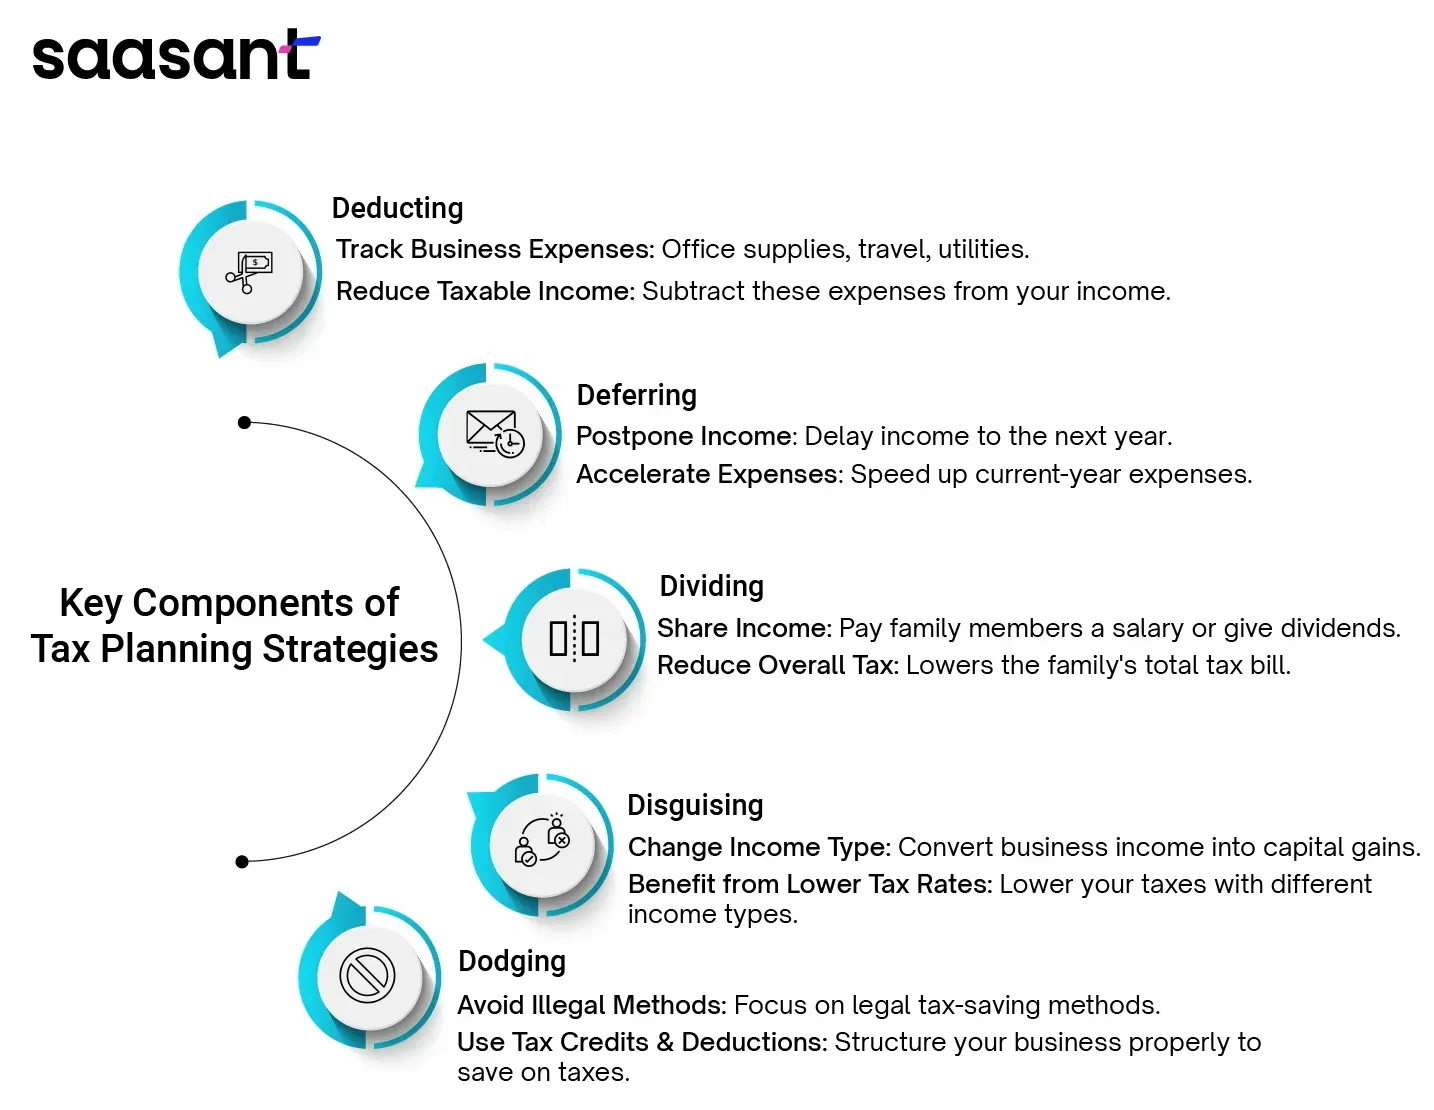
Cash-basis taxpayers have more control over when they recognize income and claim deductions than accrual-basis taxpayers do. If you're on the cash method, you can delay invoicing until next year to push income forward. You can also prepay certain expenses before year-end to accelerate deductions. The rules around prepaid expenses changed after the Tax Cuts and Jobs Act, but certain prepaid items like insurance premiums and subscription services can still be deducted in the year you pay them if the benefit doesn't extend beyond 12 months or the end of the next tax year, whichever is later. This strategy works best when you expect to be in a higher tax bracket next year. If you think rates might go up, accelerating deductions makes sense. If you think they might go down, deferring income becomes more attractive. Nobody can predict tax policy with certainty, but having a plan for both scenarios helps you avoid panic decisions in April.
Retirement Plans as Tax Shelters
SEP-IRAs and Solo 401(k)s let self-employed people shelter significant income from current taxes. A SEP-IRA allows contributions up to 25 percent of compensation, capped at around $69,000 for 2024. A Solo 401(k) lets you contribute as both employee and employer, potentially reaching over $70,000 depending on your income level. These aren't tiny amounts. Contributing the maximum can reduce your taxable income dramatically. The catch is that these contributions reduce your QBI deduction. The relationship between retirement contributions and qualified business income gets complicated fast. Running the numbers both ways before deciding which approach to take usually reveals the optimal path. Most people skip this step and just pick the plan with the highest contribution limit, not realizing they might be worse off financially.
R&D Credits Are Not Just for Tech Companies
The research and development tax credit sounds like something for big corporations with labs. It applies to much smaller operations too. Any business that develops new products, processes, or software may qualify. The credit covers up to 20 percent of qualified research expenses above a base amount. For small businesses, there's also an alternative simplified calculation that can be easier to document. I helped a manufacturing client claim this credit. They weren't inventing anything revolutionary. They were improving their production process, reducing material waste, and testing new formulations. The IRS defines qualified research broadly enough that most engineering-type work qualifies. The documentation requirement is the real hurdle. Keeping contemporaneous records of experiments, failures, and iterations matters more than the actual work in many cases.
Health Insurance Deductions Have Limits You Should Know
Self-employed health insurance premiums are deductible on your personal tax return, but only if you have net profit from the business providing the income. The deduction can't exceed your earned income from that business. If your business shows a loss, you can't use the health insurance deduction to create or increase a net operating loss. This rule prevents people from using business losses as a vehicle to claim personal deductions. Another limitation involves families where one spouse has access to employer-subsidized health insurance. You can't claim the self-employed health insurance deduction if your spouse's employer plan is available to you, even if you don't actually enroll in it. The IRS sees availability as enough to disqualify you. This catches a lot of people off guard during tax season.
When These Strategies Fail Completely
No tax strategy works if you're not keeping accurate records. I've seen business owners try to implement sophisticated deduction timing schemes while still losing receipts in shoeboxes. The IRS doesn't care about your clever plan if you can't prove your expenses. Simple bookkeeping software and consistent habits beat complex strategies every time. Another scenario where strategies fail is when your business structure creates more compliance costs than tax savings. Setting up separate entities, maintaining corporate formalities, filing separate returns, and managing payroll systems all cost money. If your tax savings are under $3,000 annually, you're probably spending more on accountants and administrative time than you're saving. Sometimes the boring approach is the right approach. The biggest failure point I see is people following advice from sources that don't understand their specific situation. A strategy that works for a restaurant owner might destroy a consulting business. A technique that benefits a freelancer could hurt a manufacturer. Generic advice creates generic results at best and costly mistakes at worst. Working with someone who understands your industry and your numbers changes everything.