What Management Tracker Top 10 Actually Means in Practice
Everyone talks about tracking the top ten holdings of major funds, but most people treat it like a crystal ball. It isn't. I've been doing this for years across mutual funds, ETFs, and private accounts, and the honest answer is that it's useful as a sentiment barometer and a rough risk check, not as a standalone buy signal. The basic mechanism is straightforward. Institutions disclose their top ten stock positions quarterly through 13F filings in the US, or through periodic reports in other markets. When you see a fund's Management Tracker Top 10 list, you're looking at the ten biggest bets the portfolio manager made in that quarter. The weights matter as much as the names. A stock at 8% of a portfolio is a conviction bet. A stock at 1.2% is basically noise.
How to Build a Working Management Tracker Top 10 System
Start by pulling the data from the right source. In the US, that's the SEC's EDGAR database, specifically 13F-HR filings due within 45 days of each quarter end. For Chinese A-shares, it's the regular reports from funds disclosed on the AMAC website or through East Money and Wind terminals. European UCITS funds publish annual and semi-annual reports with portfolio holdings. Pick one market and stick with it before expanding. The next step is normalization. Raw 13F data has quirks. Options get reported as calls or puts separately, short positions can be hidden, and some managers report derivatives rather than the underlying shares. I once spent three weeks trying to reconcile why a particular fund's top holding appeared to have doubled in weight between two quarters, only to discover they'd swapped a long position for call options and the raw filing didn't show the delta-adjusted exposure. The workaround was pulling their proxy statements and cross-referencing with FactSet holdings data, which gives you a cleaner picture of actual economic exposure. After you clean the data, track two things: the holdings themselves and the changes. A fund adding a stock to its top ten is different from a fund simply maintaining a position. The change tells you more than the level. I weight entries and exits at roughly twice the importance of unchanged positions when I'm building a composite signal.
The Real Problems People Miss
Here's what most guides don't tell you. First, lag is brutal. By the time a 13F hits the news cycle, the data is 45 to 60 days old. Smart money often adjusted that position before filing, and the trailing edge of a trade is already gone. If you're chasing Management Tracker Top 10 changes as a timing tool, you're almost always late. Treat it as a confirmation tool, not an entry trigger. Second, survivorship bias skews the picture heavily. You see the winners because their top holdings look impressive. You don't see the funds that got crushed and then liquidated their positions, because those disappear from public data. I keep a graveyard list of dissolved funds and empty 13Fs to adjust my impression of how often top-10 convergence actually works. It's far less reliable than the highlight reels suggest. Third, crowded trades kill themselves. When every retail tracker sees the same Management Tracker Top 10 and buys the same five names, those stocks become overbought on alone. I've watched this play out in 2021 with certain AI-themed funds where the top holdings compressed into three or four names across half a dozen strategies. By the time the consensus formed, the risk-reward had flipped negative.
Get the Full Details
What I Actually Do With This Data
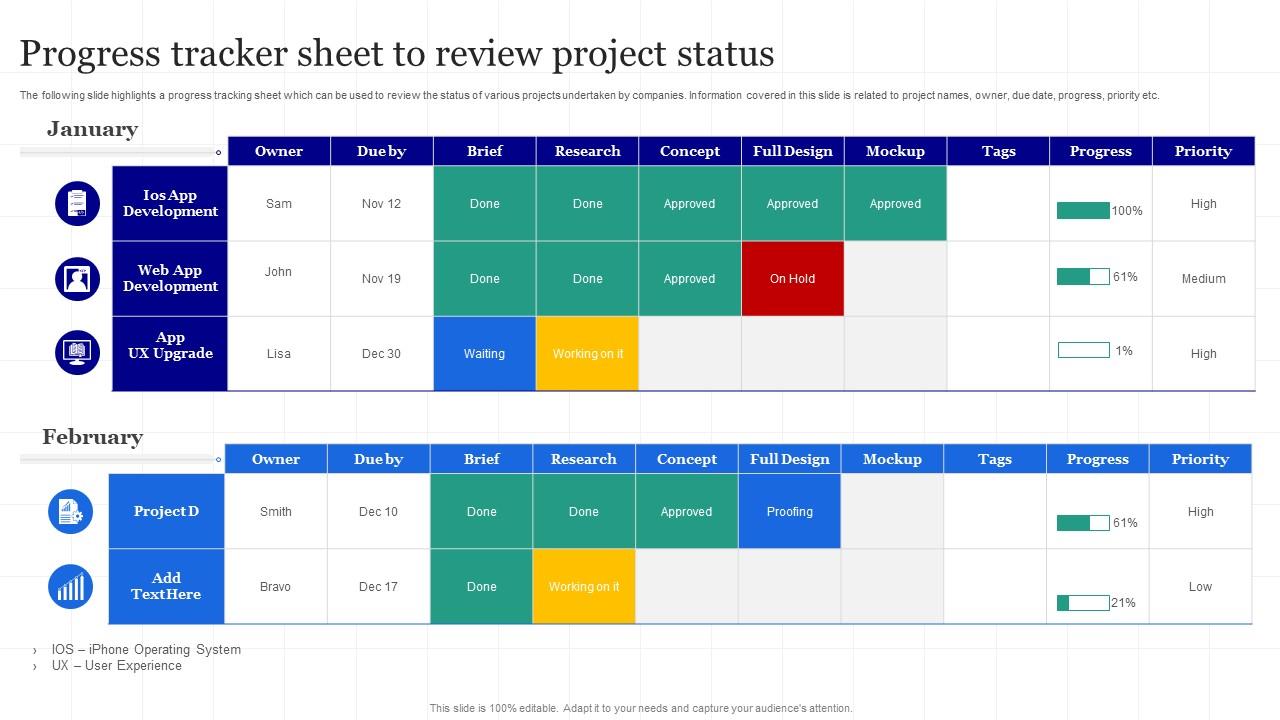
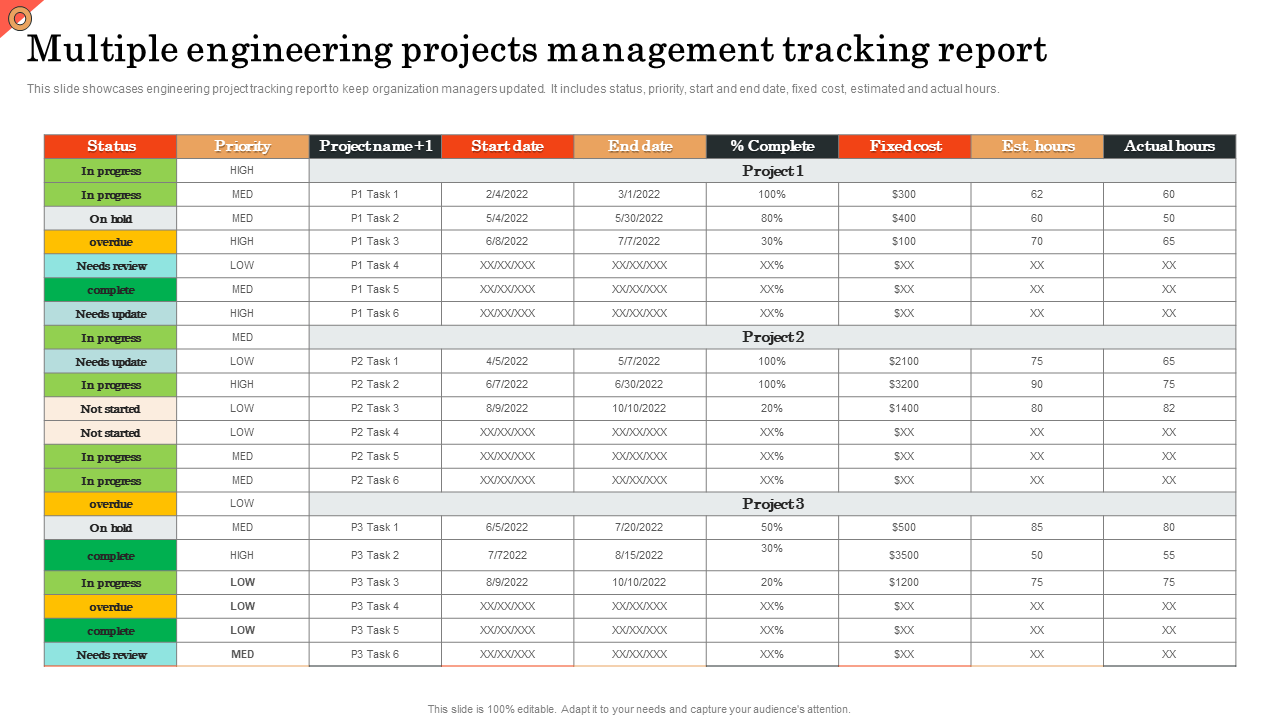
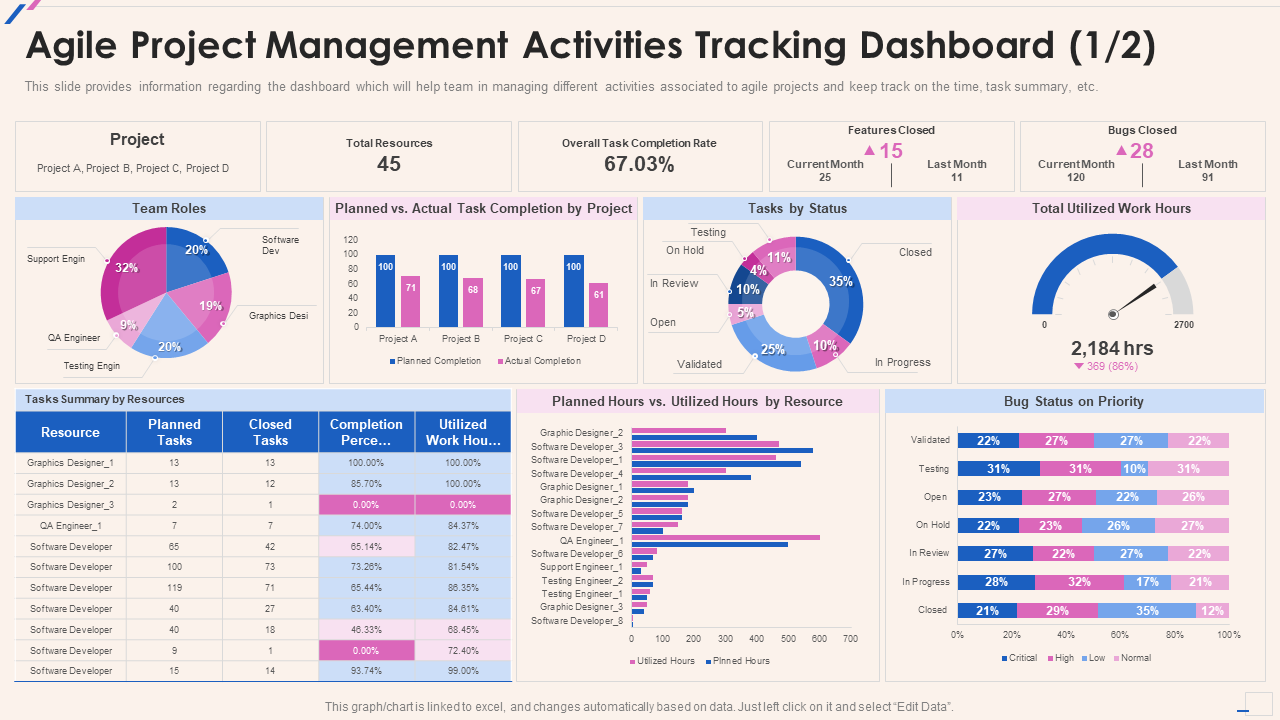
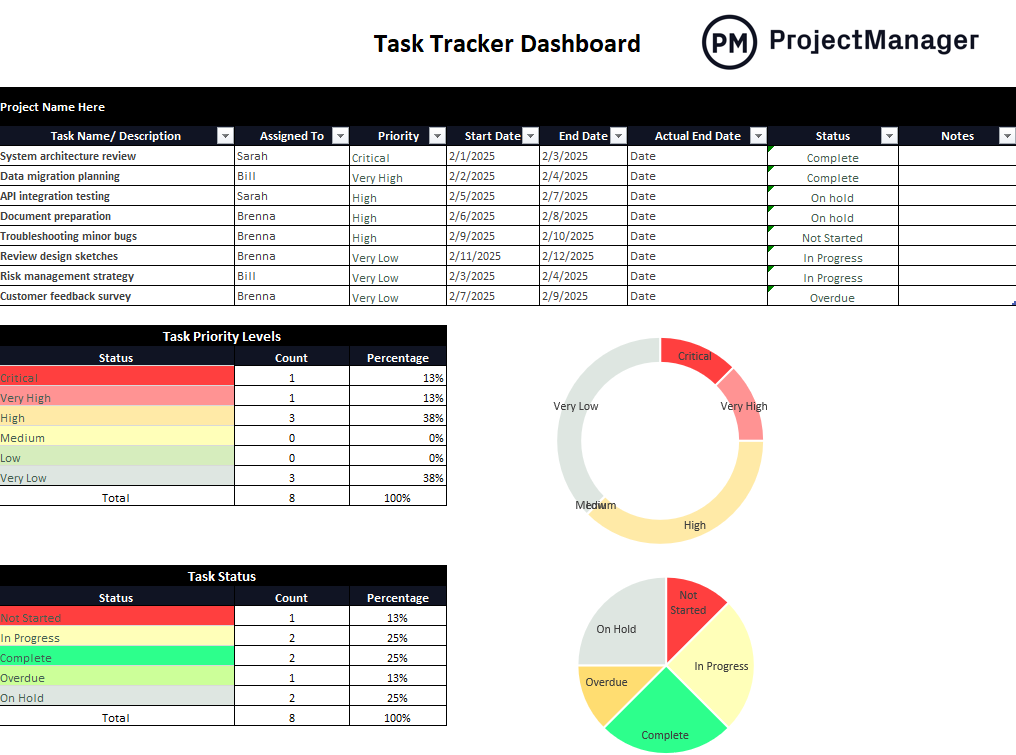
I run a weekly scan across about forty large-cap funds and twenty ETFs, pull their top ten holdings, normalize by asset class, and build a composite heatmap of sector concentration. When three or more funds in my universe all add the same name to their top ten in the same quarter, I flag it. Not as a buy, but as something worth watching. The signal has historically predicted sector rotation about two months before price action confirms it, but that's an average. Some quarters it's immediate, some it doesn't fire at all. For individual stock screening, I use the inverse approach. If a fund known for value discipline removes a name from its top ten, I take that more seriously than if a growth fund does the same. Fund style matters. A deep-value manager exiting a position usually means the thesis is broken, not that they found a better opportunity elsewhere. The practical output is a simple spreadsheet with columns for fund name, filing date, stock, weight, quarter-over-quarter change, and my own rating of conviction strength. It takes about twenty minutes to update each week once the pipeline is automated. I read a lot of these systems as elaborate dashboards that eat hours and produce nothing new. The twenty-minute version catches most meaningful moves.
Management Tracker Top 10 analysis won't make you rich on its own. It fails hard in choppy markets where position changes are noise rather than signal. It breaks down completely for hedge funds that don't file 13Fs or file incomplete ones. But as a rough compass for where institutional capital is tilting, it still works, and it's better than guessing.