Working with Marginal Cost in Calculus
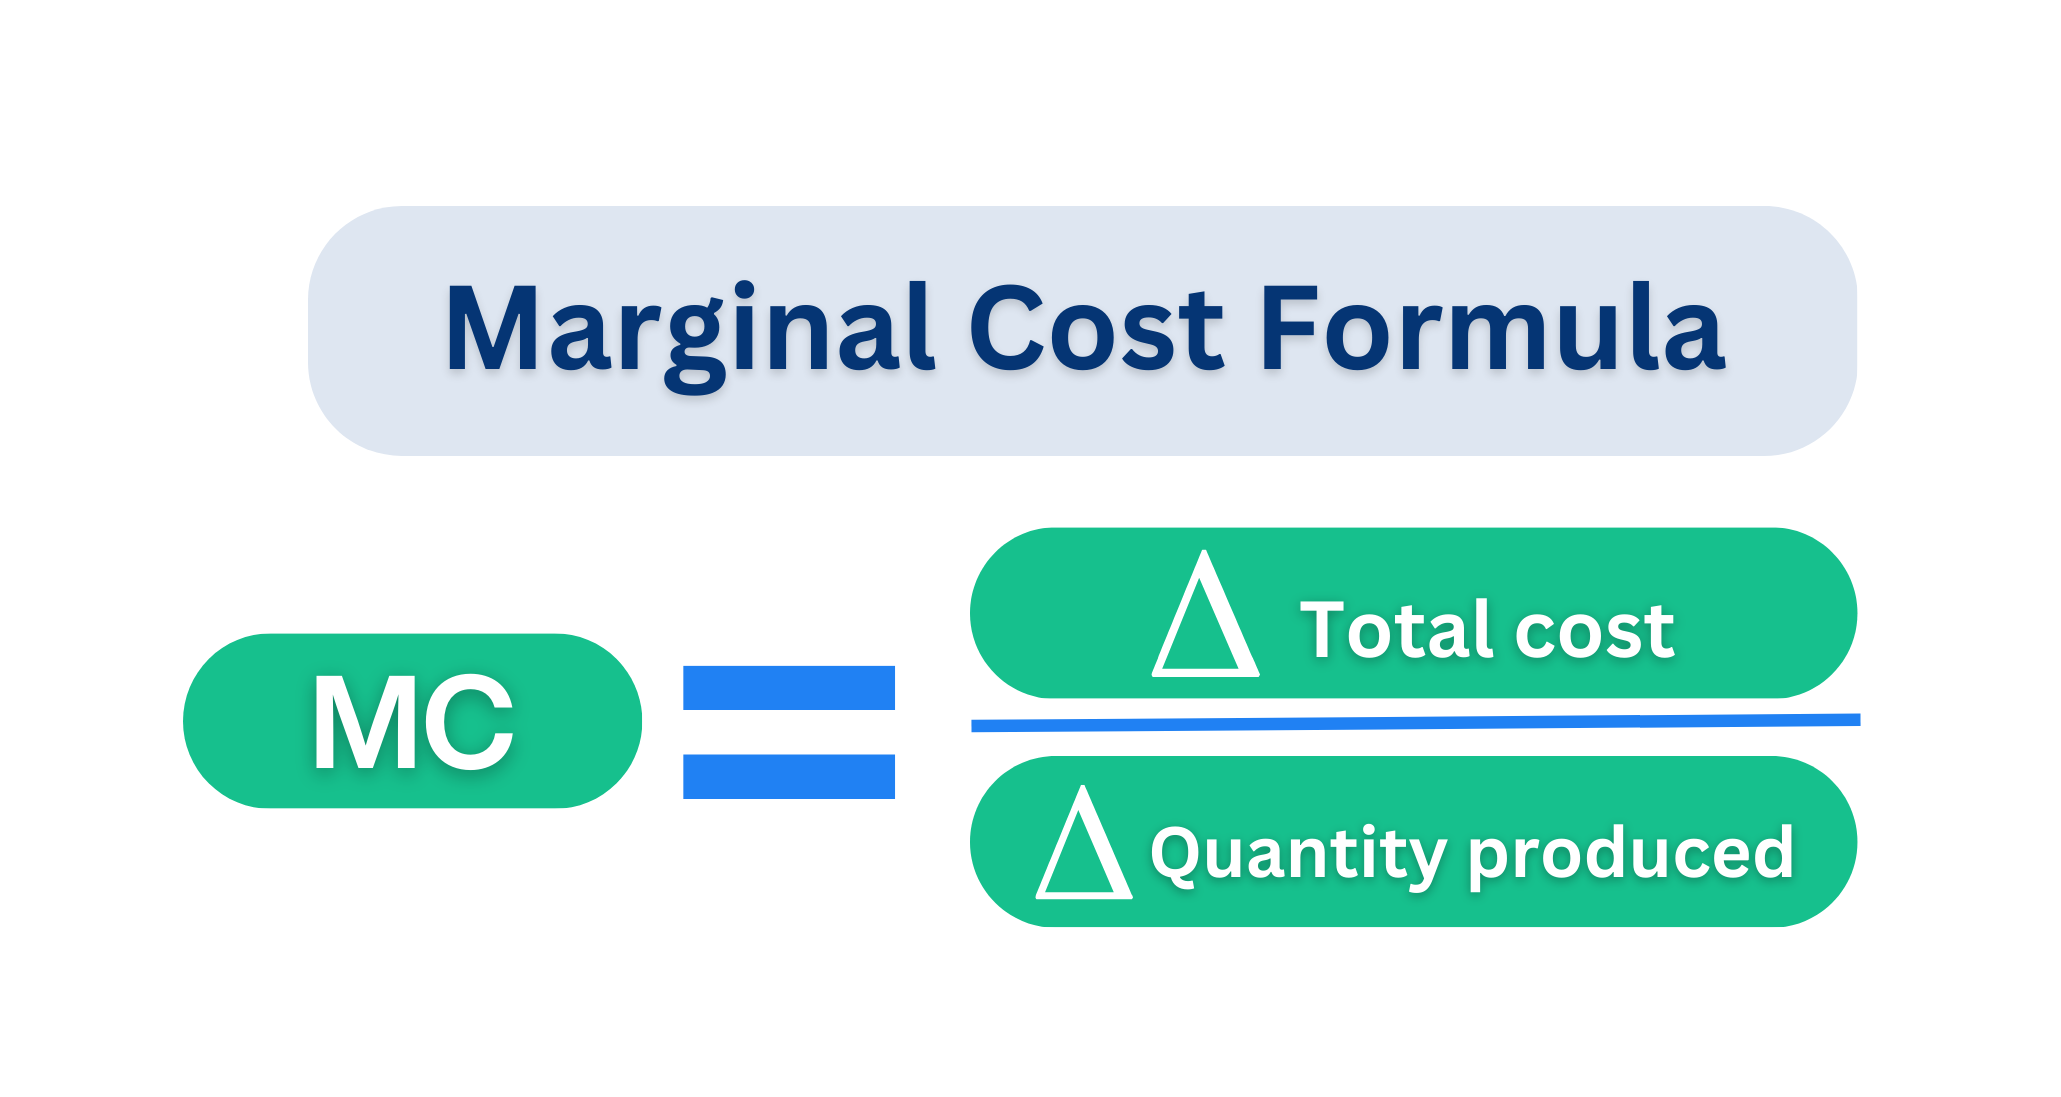
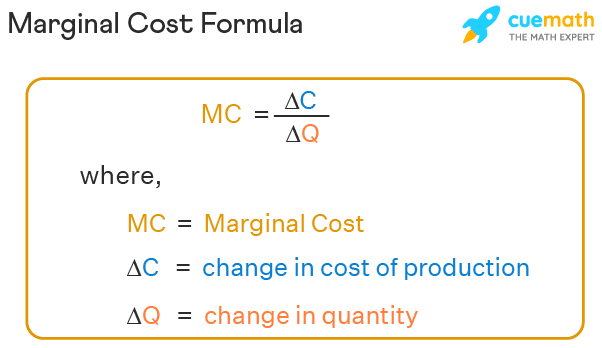
The basic idea is straightforward enough. Marginal cost tells you how much it costs to produce one additional unit. In calculus, you get there by taking the derivative of your total cost function. If C(q) represents the total cost of producing q units, then MC(q) = C'(q). That's it. The rest is mostly about knowing when this framework falls apart and what to do instead. I've seen people try to apply marginal cost calculus to real production data without thinking about the assumptions baked into the math. It doesn't take long before something goes sideways. The most common issue I run into is when people treat discrete production runs as if they're continuous. You can't meaningfully take a derivative of a cost function if your factory only produces whole widgets and you can't make half a batch. The math will give you an answer, but the answer won't match reality.
How the Marginal Cost Calculator Calculus Works
When you set this up properly, you start with your total cost function. That function should include fixed costs, variable costs, and any economies or diseconomies of scale you're tracking. The derivative operation itself is just standard calculus — power rule for polynomial terms, chain rule where needed. What trips people up isn't the differentiation, it's specifying the right cost function in the first place. Here's a concrete example. Say your cost function is C(q) = 5000 + 12q + 0.03q². The fixed cost is 5000, the linear term is 12 per unit, and the quadratic term captures rising variable costs at higher volumes — maybe overtime pay or material inefficiency. The marginal cost is C'(q) = 12 + 0.06q. At q = 100, the marginal cost is 18. At q = 500, it's 42. The cost of the next unit jumps significantly as you scale up. That's the quadratic term doing its job, showing you where diminishing returns kick in. The tricky part is that this only works cleanly when your cost function is differentiable everywhere in your range of interest. Real cost functions often have kinks. A bulk discount at q = 200 creates a discontinuity in the derivative. A step change in labor costs at q = 500 does the same. Your calculator will choke on these, or worse, give you a number that looks precise but is actually meaningless at the kink point.
I dealt with this specifically last year on a manufacturing project. We had a cost model where raw material pricing dropped sharply at certain quantity thresholds — supplier volume contracts. The cost function had several jump points, and the derivative was undefined at each threshold. Running a standard Marginal Cost Calculator Calculus approach through those points produced garbage results. The workaround was to treat each segment between thresholds as its own piecewise function, calculate marginal cost within each segment, and then manually check the left and right limits at each jump point. It added about twenty minutes of work but saved us from making a pricing decision based on a false continuity assumption. I've done this kind of manual segmentation ever since whenever volume discounts are involved. Another thing nobody mentions enough: marginal cost and average total cost intersect at the minimum of the ATC curve. This isn't just a textbook fact — it's a genuine diagnostic tool. If your calculated marginal cost curve crosses your average total cost from below at a point that doesn't match your known cost structure, something is wrong with your cost function specification. I've caught several mis-specified models this way. The intersection point gives you a quick sanity check without needing to plot everything out. There are also cases where marginal cost calculus simply isn't the right tool. If you're dealing with extremely small production batches where fixed costs dominate and variable costs are negligible, the derivative approach gives you numbers that are mathematically correct but practically useless. The marginal cost might be 0.03 per unit at low volumes, but your actual incremental cost is the entire fixed overhead because you can't avoid it. In those situations, looking at average incremental cost over a realistic batch size is more honest.
Get the Full Details

Similarly, if your cost function is primarily driven by capacity constraints rather than per-unit variable costs — think a factory running at maximum output where the next unit requires building a whole new production line — marginal cost approaches infinity at the capacity limit. The calculus still works, but the result tells you something different than you might expect. It's not telling you the cost of one more unit. It's telling you that producing one more unit isn't feasible with current capacity, and the price signal you need is investment analysis, not marginal analysis. The numerical approximation route is worth mentioning if your cost function comes from empirical data rather than a clean formula. Finite differences — computing [C(q + h) - C(q)] / h for a small h — will approximate the derivative when you don't have an analytical function to differentiate. This is common when you're working from spreadsheet data or sensor readings rather than a modeled cost curve. The trade-off is that your result inherits whatever noise is in your data. I usually smooth the data first with a moving average or lowess filter, then apply finite differences. Skipping the smoothing step tends to produce marginal cost estimates that oscillate wildly and look wrong even when they're technically closer to the true derivative than the raw data would suggest. One final practical note: set your calculator or spreadsheet to show at least four decimal places during intermediate calculations and only round at the end. I've watched people lose accuracy fast by rounding the cost function coefficients early, then differentiating the rounded version. The difference seems small until you're evaluating at q = 1000 or higher, where rounding errors compound through the derivative terms.