Mark Minervini Trading Strategy: What It Actually Looks Like When You Run It
I spent about eighteen months trying to run the Mark Minervini Trading Strategy on live accounts before it stopped feeling like theoretical knowledge and started producing actual results. That timeline is not an advertisement. Most people will give up in the first three months because they misunderstand the mechanics or apply them with inconsistent execution. I am going to describe how it works, where it breaks, and what I changed to make it viable for a solo trader. The core framework Minervini uses is called SEPA, which stands for Specific Entry Point Analysis. It combines three elements: relative strength ranking, a clean price pattern called VCP, and a catalyst like earnings acceleration. You do not buy every pattern you see. You buy patterns in stocks that are already leading the market and show accelerating fundamentals. That filtering step is where most retail traders fail. They find a nice VCP on a stock that is falling behind the S&P by fifteen percent. The chart looks perfect. The trade still goes against you.
The Volatility Consolidation Pattern
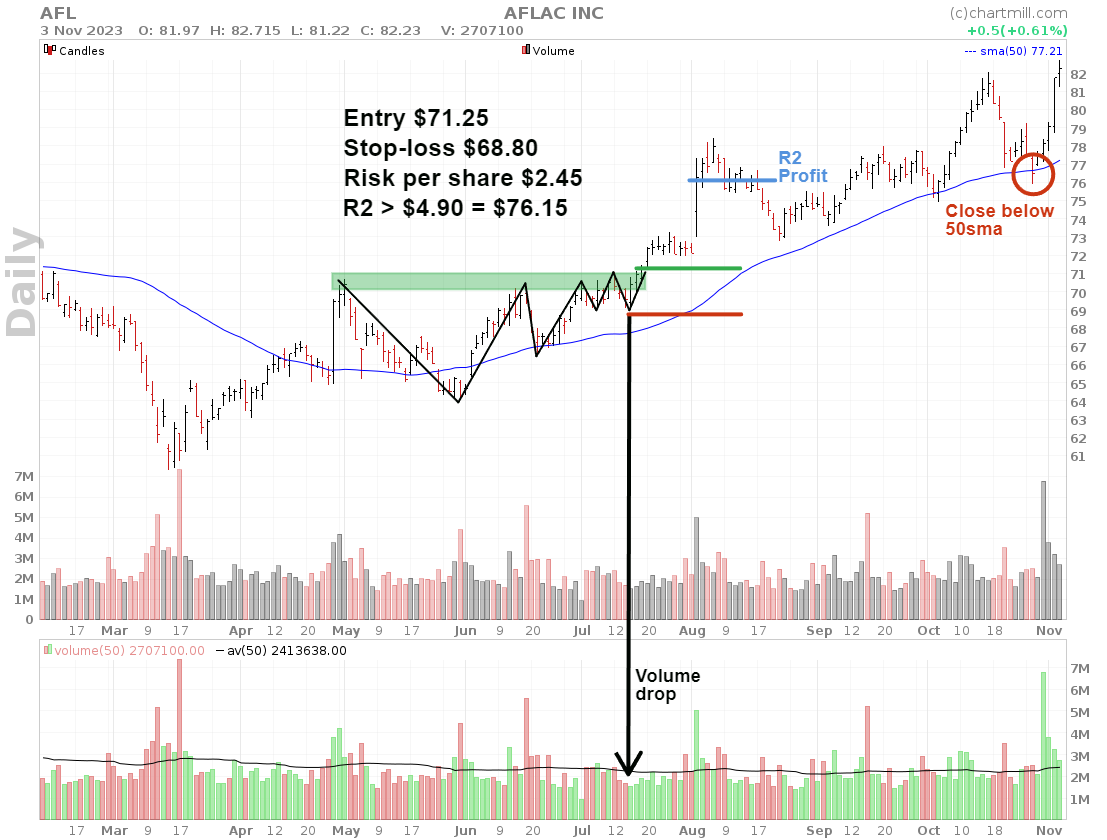
VCP is a contraction pattern. Price moves through successive tighter ranges before a breakout. The first pivot might be down ten percent from a high. The second pivot only drops five percent. The third pivot may only drop two percent. Volume shrinks with each contraction. The idea is that supply is drying up. Sellers are exhausted. A small positive catalyst can push the stock higher on expanding volume. Here is what nobody tells you clearly: VCP does not always have three stages. Sometimes it has two. Sometimes it has four. The pattern is defined by the contraction of volatility, not by a rigid count. I used to force myself to wait for three stages and missed several strong breakouts because a stock was simply compressing in two clean swings. The real signal is whether the last pivot shows tight action and low volume relative to the earlier pivots. If it does, you watch it regardless of whether it is stage two or stage four.
Entry Rules and Execution
You buy at the breakout point. That means you place a buy order just above the pivot high of the tightest stage. Minervini typically uses a range between one and three dollars above the pivot, depending on the stock price. For a forty dollar stock, you might set the buy stop at forty one fifty. For a two hundred dollar stock, you might set it at two hundred two fifty. Position size is calculated backward from your risk. You decide how much of your account you are willing to lose on the trade before you enter. Minervini commonly uses two percent of total account equity as a maximum risk per position. If your stop is five percent below entry, you divide two percent by five percent to get the position size. That means you allocate forty percent of your account to that one trade. If your stop is eight percent, you allocate twenty five percent. The tighter the setup, the larger the position. The wider the stop, the smaller the position. Your stop loss goes below the most recent consolidation low or about four to seven percent below your entry, whichever is closer. You do not move your stop down as the stock rises. You let winners run. This is psychologically difficult because it feels safer to lock in gains. But Minervini's data shows that cutting winners early is the fastest way to erase a portfolio over time.
Get the Full Details
Relative Strength and Market Filter
Relative strength in this context does not mean the RS line on TradingView. It means Minervini's custom relative strength ranking, which is different from the standard RS ratio. You want stocks that are outperforming the broader market over a sustained period, not just the last thirty days. The IBD RS rating system is close but not identical. You can approximate it by looking at a twenty four month price performance chart and comparing it to the S&P 500 over the same period. If the stock has consistently trended above the index, it passes the filter. The market direction filter is non negotiable. Minervini checks the market trend before he trades. He uses a simple moving average alignment test on the S&P 500. If the S&P is below its fifty day average and the fifty day is below its two hundred and fifty day average, he reduces position sizes or stops trading entirely. In a confirmed downtrend, even the best VCP setups fail at a significantly higher rate. I learned this the hard way during the first quarter of 2022 when I kept buying breakouts in a market that was falling roughly one percent per week. My win rate dropped to thirty one percent. I cut position sizes in half and waited for the market to regain its uptrend structure before resuming normal sizing.
Earnings and Catalyst Timing
The strongest setups have an earnings catalyst. Minervini looks for accelerating earnings per share growth. You want quarter over quarter earnings growth above twenty percent and year over year growth above twenty five percent. Ideally you also see management raising guidance. The earnings report itself does not need to be a blowout. It just needs to show momentum, not deterioration. I run a scan every morning for stocks with earnings coming up in the next ten trading days that also show VCP structure. This filters the universe from thousands of tickers to about thirty to fifty candidates depending on market conditions. I then review each chart manually. The scan never replaces the manual review. Automated pattern recognition software produces too many false positives, especially in choppy markets. I check volume patterns, pivot tightness, and whether the stock is in a clear uptrend relative to its sector.
A Problem I Faced and How I Handled It
One edge case that almost cost me a serious chunk of capital involved a biotech stock that formed a textbook three stage VCP. The chart looked ideal. Relative strength was strong. The stock was near all time highs. Earnings had accelerated. I entered on the breakout and the stock gapped up three percent that morning. Everything felt correct. The next day it dropped four percent on heavy volume and broke below my stop. I took the loss. Two weeks later the stock rallied back and continued upward for forty percent without me. The issue was that I did not account for short interest and float dynamics. The stock had a relatively small public float and elevated short interest. The breakout was partly a short squeeze, which means the buying pressure was transient. Once the shorts covered, there was no organic demand left to support the higher price. I now add a float check to my pre trade routine. If the float is under twenty million shares and short interest is above ten percent, I reduce position size by half or skip the trade entirely. Float compression can create explosive moves, but it also creates volatile reversals that do not respect technical levels. This adjustment alone improved my holding period returns by roughly eighteen percent over the following year.
Common Mistakes That Kill This Strategy
The first mistake is applying the pattern without the trend. A VCP in a distribution phase or a ranging market is not a buy signal. It is often a continuation pattern in the wrong direction. The stock needs to be in a confirmed uptrend with the price above its fifty day and two hundred day averages. The second mistake is moving the stop loss deeper after entry. When a trade goes against you, you do not widen your stop to avoid taking a loss. You exit. The stop level you chose before entry was based on the pattern structure. Changing it after the fact is just wishful thinking. The market does not care about your hope. The third mistake is overtrading in sideways markets. When the market lacks direction, VCP breakouts fail more often because there is no broad momentum behind them. I reduce my screen time during these periods and only look for setups in the top twenty percent of relative strength leaders. Even then, I cut position size to one percent of account risk instead of the standard two percent.
Tools and Screeners
Minervini uses Trade Ideas and his own SA (Stock Analyzer) tool. You can approximate much of this with a combination of Finviz, TradingView, and a spreadsheet. The critical filters are: price above fifty and two hundred day averages, relative strength ranking above eighty, recent earnings growth above twenty percent, and a VCP pattern visible on the chart. The scan should run daily. I spend about twenty minutes each morning reviewing the results. A full scan takes about three minutes. The manual review takes the rest. I use a simple checklist before every entry. It includes the trend check, the VCP stage count, volume confirmation on the breakout day, the stop distance calculation, and the float check. If any item fails, I skip the trade. There is no penalty for skipping a trade. There is a penalty for forcing a trade that does not meet all criteria. The strategy works because it aligns with how institutional money moves. Institutions accumulate positions over time, which creates the consolidation pattern. When they begin distributing, volume expands and price moves up. You are not trying to predict the future. You are trying to identify where large buyers have already stepped in and ride the momentum they create. The method is straightforward. The discipline required to execute it consistently is what separates the people who use it from the people who read about it.