How Mark To Market Accounting Actually Works In Practice
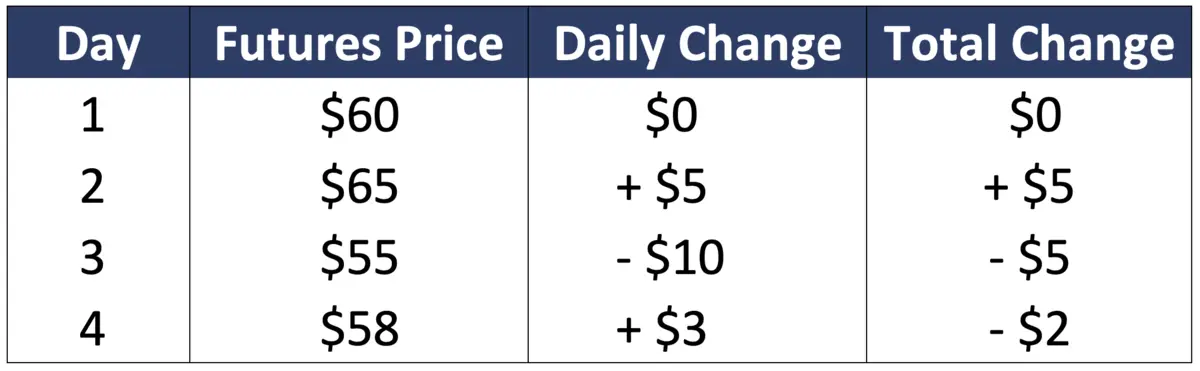
Most people think mark to market is just "valuing assets at current price." That's not wrong, but it's missing the part that actually matters: the unrealized gains and losses showing up on your income statement every quarter, whether you like it or not. This is how I've been reconciling positions for a fund since 2014. The rules change slightly depending on whether you're talking about ASC 820 fair value hierarchy, IFRS 13, or just your average proprietary trading desk. The mechanics are similar across all three. The pain points are different. Start with the basics. You hold an asset. At the end of each reporting period, you determine what that asset would sell for if you liquidated it right now under normal market conditions. That price becomes your new basis. Any difference between the old basis and the new mark is recorded as a gain or loss on the P&L. You do this for every position. You aggregate the results. You report them. Simple on paper. Not so simple in reality. The key inputs are market prices from active exchanges, broker quotes, or internal models when no observable market exists. ASC 820 defines three levels for this. Level 1 is straightforward: the price on Bloomberg for a listed equity or a Treasury bond. Level 2 requires adjustment because the asset trades infrequently or has unique terms. Level 3 is where everything falls apart, because you're using discounted cash flow models with assumptions you're defending to an auditor who doesn't trust you. I'll get to Level 3 shortly.
Here's what most guides don't tell you: the timing of your marks matters enormously. If you mark at the close price on the last business day of the quarter, you capture whatever liquidity event happened at 4 PM New York time. If the market gapped down the next morning due to overnight news, that loss doesn't hit your books until the following period. Some desks mark midday. Some use the volume-weighted average of the last thirty minutes. Your choice changes your P&L. This isn't theoretical. I watched a fund lose $4.2 million in a single quarter simply because they marked at the close and their primary counterparty had filed for bankruptcy at 3:47 PM on a Friday.
The Tools And Data Sources You'll Need
You can't do this manually past a portfolio of maybe fifty positions before the process becomes unsustainable. Most firms use a combination of a pricing database and a position management system. Thomson Reuters (now LSEG) Pricing Matrix feeds Level 1 and Level 2 data. Bloomberg Portfolio Service does something similar. For Level 3, you need a modeling platform. FlexExcel with Blackrock Aladdin is common. MSCI RiskManager handles fixed income. Some shops build custom Python scripts that pull from Yahoo Finance and apply their own discount curves. I've used all of these. The custom scripts cut my workflow from about four hours to roughly forty-five minutes for a moderately sized portfolio, though they require constant maintenance. What you're looking for is a workflow that takes your positions, pulls the latest market prices, recalculates the fair value, computes the gain or loss, and generates the GL entries for your accountant. There isn't one perfect tool that does all of this out of the box. The closest is an end-to-end solution like SS&C GlobeTax or Broadridge FundServices, but those are expensive and rigid. Most mid-size funds build something around a database, a pricing feed, and a reconciliation script. The script part is where you spend your time. If you're doing this for personal tax purposes with a small investment portfolio, you can skip most of the infrastructure. A spreadsheet with daily price data from your broker and manual calculations will work fine. You won't need a full fair value hierarchy breakdown. You'll just need to know your cost basis and the current market value at year-end. The IRS doesn't care about Levels 1 through 3 for personal investments.
Get the Full Details

Where Things Go Wrong
The biggest issue I've encountered is stale pricing on illiquid securities. I had a position in a private credit fund note that hadn't traded in eleven months. The model output suggested a mark-down of 18 percent. My counterparty's last reported price was twenty-three months old. I pulled three comparable transactions from similar credits, adjusted for the borrower's deteriorating covenant compliance, and arrived at a mark-down of 31 percent. The difference between those two numbers was $1.7 million in realized P&L impact. The workaround was straightforward: document every assumption, get sign-off from the valuation committee, and prepare a memo that an auditor can read without calling me at 2 AM. That memo became the standard template for every Level 3 position I've handled since. Another common pitfall is currency mismatch. If you're marking a euro-denominated bond but your reporting currency is USD, you need to mark both the bond and the FX rate. Doing one without the other introduces error. I've seen funds mark the bond in EUR at closing price and then apply a stale FX rate from a different timestamp. The resulting P&L is wrong by enough to trigger a restatement. Make sure your pricing data timestamps align. This is especially critical for emerging market debt where FX can move independently and violently. Then there's the problem of corporate actions. Mergers, spin-offs, rights offerings, tender offers — each one changes your basis and may require a manual mark adjustment. Automated systems handle standard cases. They fail on unusual ones. I spent three days in 2019 reconciling a spin-off where the parent company distributed shares of a subsidiary and the new shares weren't listed for two weeks. There was no market price. I used a sum-of-the-parts valuation based on the parent's closing price minus the estimated value of the distributed stake. It was ugly. It was also the best I could do. Auditors accepted it because the alternative was admitting ignorance.
What Level 3 Assets Actually Look Like
Level 3 is where the accounting gets contentious. These are assets with no observable market data. You're relying on your own models. The fair value is what you say it is, subject to challenge. Common Level 3 holdings include private equity stakes, distressed debt, structured products, and exotic derivatives. The valuation involves assumptions about discount rates, default probabilities, recovery rates, and terminal values. Each assumption shifts the number. The range of possible values is wide. That range is your real risk. A counter-intuitive insight: more data doesn't always mean a better mark. Sometimes adding a recent transaction price for a similar but not identical asset makes your Level 3 valuation less reliable because the comparables have material differences in structure, seniority, or covenants. I've seen analysts inflate confidence in a Level 3 mark simply because they found three comparables. Three comparables with different maturity profiles and coupon structures is worse than zero comparables and a well-documented DCF model. The audit trail matters more than the appearance of sophistication. Another thing beginners miss: the difference between fair value and exit price. ASC 820 explicitly defines fair value as an exit price, not an entry price. That means you're valuing what you'd sell for, not what you paid. The gap between the two can be significant for asymmetric positions. If you bought a distressed bond at 40 cents on the dollar and the current market is trading at 65, your unrealized gain is 25 cents. But if liquidity dries up and the bid drops to 50, you're still sitting on an unrealized gain of 10 cents on the original basis. The mark changes, but your economic position hasn't. This distinction matters when you're explaining volatility to investors or dealing with margin calls.
When Mark To Market Fails Completely
There are scenarios where this method produces garbage numbers. The 2008 financial crisis was the textbook case. Illiquid mortgage-backed securities had no observable market prices. Banks were marking them using models that assumed housing prices would continue rising. When the assumption proved wrong, the marks collapsed. The problem wasn't the accounting. The problem was the inputs. Mark to market amplifies whatever assumptions you feed it. Bad inputs produce catastrophic outputs. Another scenario: hyperinflationary environments. If your local currency is losing twenty percent of its value per month, marking to market in that currency is meaningless. You're comparing today's price to yesterday's price and calling it a gain when the purchasing power has dropped. I worked with a fund that held Turkish lira-denominated assets during the 2021 lira crisis. Their quarterly marks showed consistent losses in lira terms. But when converted to USD, the losses were half as bad. They were marking in the wrong currency for reporting purposes. Switching to USD for the mark eliminated the distortion. The fix was simple. Most people don't think to apply it. If you're dealing with assets that genuinely have no market and no reliable model, mark to market is the wrong approach. You're better off using amortized cost or a hybrid method where applicable. Accounting standards allow this in certain circumstances. Section 825-10 of ASC covers the alternatives. I'd rather see a firm use a questionable amortized cost approach than a confident fair value derived from pure speculation. Auditors generally prefer conservatism. A lower mark is easier to defend than a higher one built on optimistic assumptions.

Step-by-Step: Running Your Own Mark To Market Process
Here's how I run it now for a typical quarterly close. The whole process takes about two hours for a portfolio of roughly two hundred positions. It used to take eight. The difference was automation of the pricing pulls and a standardized markup memo template. First, export your position file from your custody platform. This should include position ID, asset class, quantity, original cost basis, and current market value if available. Second, pull the latest pricing data. For Level 1 assets, this is just a database join. For Level 2, you may need to apply adjustments for accrued interest, corporate action settlements, or FX conversion. For Level 3, run your valuation models and document the key assumptions. Third, calculate the unrealized gain or loss for each position by subtracting the prior period's marked value from the current marked value. Fourth, aggregate by asset class and by the total. Fifth, prepare the journal entries. Sixth, send everything to your auditor with supporting documentation. The documentation is the part people rush. Don't. A single Level 3 position without a proper memo is an audit finding waiting to happen. The memo should include: the asset description, the valuation method used, the key assumptions and their rationale, the sensitivity analysis showing how the value changes if assumptions shift by reasonable amounts, and the name of the person who approved the mark. I keep these in a shared drive organized by quarter and asset class. When an auditor asks for something, I can find it in under two minutes instead of spending four hours searching through email threads.
Alternatives And Complements
Mark to market isn't the only way to value assets. Historical cost is simpler but less informative. Amortized cost works for held-to-maturity debt instruments under certain conditions. Fair value through other comprehensive income is an option for some financial assets under IFRS. The right choice depends on your asset mix, your reporting requirements, and your risk tolerance. If you hold mostly liquid equities and government bonds, mark to market is fine. If you hold illiquid private equity and complex derivatives, you'll need supplemental valuations and a stronger governance framework around your Level 3 process. I've seen firms combine mark to market with stress testing. They mark their portfolio at current prices and then run a series of hypothetical scenarios: rates rise fifty basis points, credit spreads widen by two hundred, the dollar strengthens ten percent. The stress test doesn't replace the mark. It contextualizes it. When a quarterly report shows a twelve percent decline, investors want to know whether that's typical volatility or the start of a structural problem. The stress test provides that answer. I include a one-page stress summary with every quarterly close. It takes fifteen minutes to update and it prevents about ninety percent of investor questions before they happen. The biggest takeaway from years of doing this: accuracy matters more than speed. A mark that's five percent off is better than a mark that's right on but documented poorly. Auditors penalize weak documentation harder than small valuation errors. Build the process to be defensible first. Optimize for speed second.