What You Need to Know About Maryland Employer Withholding Guide 2023
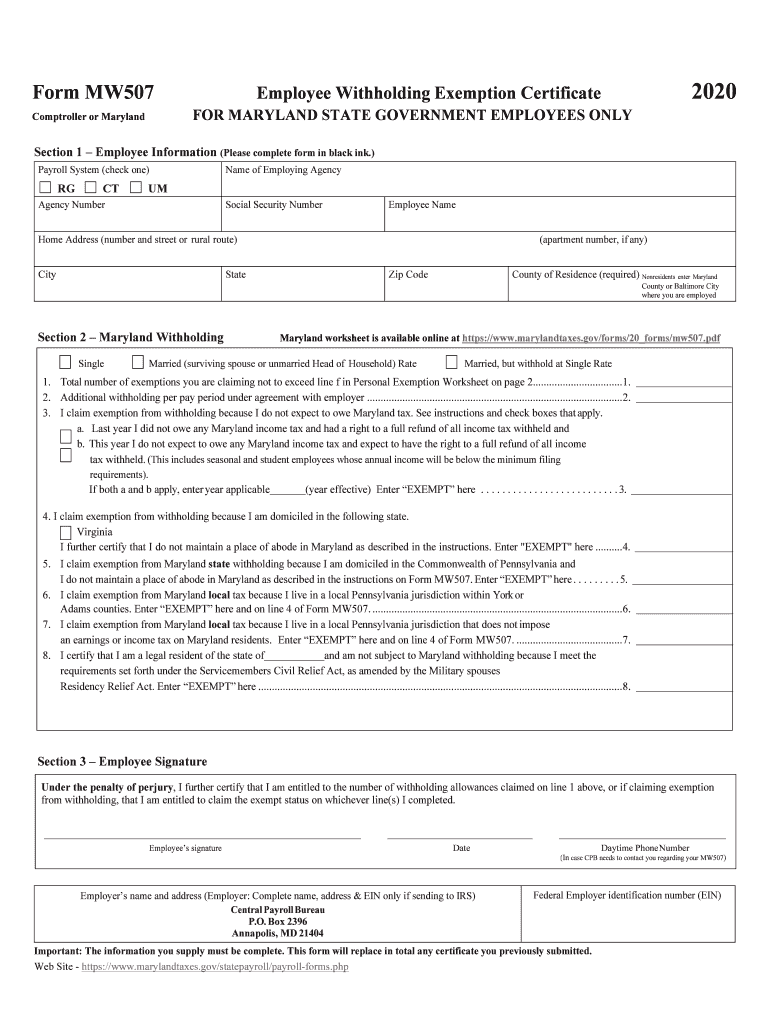
Handling employee withholding in Maryland requires navigating a system that is neither simple nor particularly well-documented. The state uses its own calculation methods for both income tax withholding and unemployment insurance contributions. Most employers stumble on the specifics rather than the basics. Maryland mandates that employers withhold state income tax from employee wages using specific tables and percentages published by the Comptroller of Maryland's office. Unlike federal withholding where you have W-4 forms and standard allowance methods, Maryland requires its own declaration process. Employees must complete Form MW3—Maryland Withholding Allowance Certificate—or rely on default withholding levels set by the state. The actual withholding calculation depends on several factors including pay frequency, filing status, and the number of allowances claimed. The state provides withholding tables in two formats: percentage method and wage bracket method. For most small businesses paying weekly or biweekly, the wage bracket tables are simpler to use. Medium to large employers typically benefit from the percentage method, especially when dealing with commissions, bonuses, or overtime that fall outside standard brackets.
I learned this distinction the hard way back in 2019 when I was managing payroll for a mid-size operations team. We had been using the wage bracket tables for everything, including quarterly bonuses. The Maryland Comptroller's office audited us and flagged that the bonus withholdings didn't match what the percentage method would produce. We owed approximately $4,200 in additional withholding plus interest. The workaround was switching entirely to the percentage method for all subsequent payments and recalculating everything retroactively for that quarter. It took about six hours to correct the calculations but saved us from future audit exposure.
Quarterly Payment Requirements and Deadlines
Maryland requires quarterly withholding tax payments, unlike some states that operate on monthly schedules. The due dates align with the end of each calendar quarter—March 31, June 30, September 30, and December 31. Payments must be made electronically through the Maryland Tax Gateway unless your liability falls below certain thresholds that permit paper check submission. The estimated payment amounts come from summing up all withholding taxes collected during the quarter. Employers who have been in business for more than one year can use prior year liability as a reference point. New businesses should estimate based on projected payroll. Underpayment penalties apply when quarterly payments fall below 90% of the current year liability or 100% of the prior year amount, whichever is smaller. The penalty rate currently sits at roughly 3% per annum on the underpaid portion. One thing nobody warns you about: Maryland does not prorate withholding for partial quarters. If you start operations on the 15th of a month and run payroll for that partial month, you still owe the full quarter's payment by the end date. This tripped up a client of mine who opened a warehouse facility mid-quarter and expected proportional withholding treatment. The state rejected their partial calculation outright.
Get the Full Details
Unemployment Insurance Tax Obligations
Beyond income tax withholding, Maryland employers must handle unemployment insurance contributions through the Maryland Department of Labor. Your experience rate determines the percentage applied to taxable wages. New employers typically start at a statutory rate around 2.7% but can adjust significantly based on layoff history and claims experience. The UI tax calculation applies only to the first $35,000 of annual wages per employee. Wages above that threshold do not factor into unemployment tax calculations. This cap matters for higher-paid staff where the income tax withholding continues on full wages but UI contributions stop after reaching the cap. Tracking both simultaneously requires separate ledger lines in your payroll system. Quarterly UI contributions follow the same payment schedule as withholding taxes. Employers must file Form UC-10 quarterly and submit payment covering current quarter liabilities. Late filings incur penalties starting at 10% of the unpaid amount, escalating to 25% for repeated violations. The state also charges interest at 1.5% monthly on overdue balances.
Annual Reconciliation and Reporting
Every January, Maryland employers must reconcile withholding amounts collected against payments made throughout the year. Form 500—the Annual Return of Income Tax Withheld for Employees—serves as the reconciliation document. The filing deadline is February 28th or March 31st if filing electronically. Missing this deadline triggers automatic penalty assessments regardless of whether you believe the numbers balance. The form requires matching gross wages paid, total withholding collected, and total payments already submitted quarterly. Any discrepancy between these figures prompts immediate review by the Comptroller's office. Employers who discover errors after submitting Form 500 must file corrected versions rather than waiting for the next year's reconciliation. Amended filings carry no penalty if submitted within 30 days of discovering the mistake. Form W-2 distribution to employees remains mandatory alongside the annual state filing. Maryland requires that W-2s show state withholding in Box 17 with the state code MD entered in Box 15. Employers who fail to include state withholding information on employee copies face separate penalties distinct from the withholding tax penalties.
Common Pitfalls to Avoid
Several recurring mistakes show up in Maryland withholding compliance reviews. The first involves misclassifying independent contractors versus employees. Maryland follows IRS guidelines for worker classification but maintains its own enforcement standards. misclassifying a worker as a contractor eliminates withholding obligations entirely, which draws scrutiny during random audits. The second common error concerns vacation and severance pay. Some employers assume these payments bypass state withholding requirements. Maryland taxes both vacation and severance pay as ordinary wages subject to withholding. The only exception involves certain death benefits paid to beneficiaries. A third mistake involves multi-state operations. Employers with workers performing duties across state lines must determine which state holds withholding jurisdiction. Maryland claims taxing rights when work is performed primarily within the state, even if the employer maintains headquarters elsewhere. This nexus rule creates complications for remote work arrangements that became common post-2020.
Resources for Continued Reference
The Maryland Comptroller's office maintains an employer resource section online with current forms, publication schedules, and FAQ documentation. Their telephone assistance line operates during standard business hours and can clarify specific calculation questions. Third-party payroll providers familiar with Maryland requirements generally handle compliance automatically when properly configured. Membership in professional payroll associations provides access to updated guidance and peer networks for troubleshooting unusual situations. The American Payroll Association maintains state-specific chapters that often host compliance workshops before major deadline periods.