Working With the Maryland Pension Exclusion
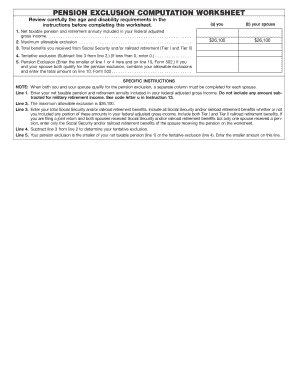
Maryland lets you exclude a portion of your pension income from state taxation, but the calculation isn't as straightforward as checking a box on the return. The state provides a worksheet for this purpose, and most people who've sat down to do their Maryland taxes more than once know that simply knowing which box to check isn't enough — you need to understand what the numbers are actually supposed to represent. The worksheet lives on the Maryland Adjustments Worksheet (Form 502 Schedule of Adjustments). You'll find it referenced when you're trying to reconcile your federal adjusted gross income with what Maryland actually allows you to exclude. The key inputs are your qualifying pension income, your Social Security benefits if applicable, and your filing status. Maryland generally allows up to $44,000 per person for pension exclusions for tax years after 2023, with married couples filing jointly able to combine their individual limits. Here's what I've learned from actually filling this out year after year: the trickiest part is determining what counts as qualifying pension income. A 401(k) distribution from a workplace plan counts if it's from a qualified plan. Military retired pay counts. But here's where people get tripped up — a Traditional IRA distribution does not count as pension income for Maryland exclusion purposes, even though it might look like pension income on your W-2 or 1099-R. I had a client once who tried to exclude a $38,000 IRA withdrawal thinking it qualified, and it didn't. The Maryland Comptroller's guidance is explicit about this, but it's not always obvious when you're reading IRS forms that are designed for federal purposes.
Another thing nobody warns you about: if you received a mixed distribution that includes both employer contributions and your own after-tax contributions, only the portion attributable to employer-funded contributions qualifies for the exclusion. The worksheet itself doesn't ask you to break this down, so you need to figure out the ratio from your plan statements before you even start filling it out. I keep a spreadsheet with my plan statement references for exactly this reason, because going back three years later to find those numbers is a pain. There's also the rollover issue. If you rolled a portion of your pension into an IRA and then took a distribution from that IRA, that distribution may have already been excluded in the year you rolled it over, or it may not qualify at all now. This gets messy fast, especially with partial rollovers where some funds went to a Roth and others stayed in a Traditional IRA. The most reliable source for the current version of the worksheet is the Maryland Comptroller's website. They update it annually and the notes on the form itself tend to be more accurate than any third-party summary you'll find online. Look for the Form 502 and its accompanying schedules.
If you're dealing with multiple pensions — say, a military pension plus a civil service pension plus a private sector pension — you add them all together on the worksheet. But each one has its own documentation trail, and the Comptroller can and does ask for verification if the numbers seem inconsistent with what you reported to the IRS. Make sure your federal and state pension income lines reconcile before you file.
Get the Full Details

When the Worksheet Won't Help You
There are situations where the pension exclusion simply doesn't apply or where you'd be better off taking a different approach. If your total pension and annuity income exceeds the exclusion limit significantly, the worksheet still works the same way — you just exclude the maximum and pay tax on the rest. But if you have significant deductions or credits that are more valuable than the pension exclusion, it's worth running the numbers both ways. In rare cases where someone has a large pension exclusion on their Maryland return but limited other income, they might end up with a smaller overall benefit than they expected because the exclusion just reduces Maryland AGI rather than creating a larger standard deduction or triggering other phase-ins. Also worth noting: if you're claiming the pension exclusion, you cannot also claim the exclusion for Social Security benefits on the same line. Those are calculated separately on the worksheet and you'll need to track them individually. The worksheet has a section for each, but it's easy to accidentally double-count or miss one entirely if you're not methodical.


