Getting Your Massmutual Whole Life Dividend History
Massmutual Whole Life Dividend History isn't something you can pull up in two clicks the way you'd check a 401(k) balance. It lives inside their member portal, but the interface isn't exactly intuitive if you've never navigated it before. I've gone through this probably half a dozen times for different clients and for my own policies, so here's how the process actually works. First, log into the MassMutual online member portal. If you don't have an account set up yet, you'll need your policy number from your original contract or any statement that came in the mail. They require identity verification the first time around — usually a government-issued ID photo upload and a security question setup. Factor in about ten to fifteen minutes just for the initial registration because their fraud check can be slow.
Where to Find Massmutual Whole Life Dividend History
Once you're in, navigate to the policies section. Select your whole life policy, then look for something labeled "dividend illustration," "policy history," or "annual statements." The exact label shifts depending on which version of their portal you landed on. From there, you should see a downloadable PDF of your annual dividend declarations going back to when the policy was issued. Some older policies might only show data going back about twenty years in digital form, even though MassMutual keeps records indefinitely. If you can't find it online, calling their member services line is the fallback. The wait time varies. I'd recommend calling between 8 and 9 in the morning on a Tuesday if you want a reasonable chance of getting through within twenty minutes. When you do get a representative, ask them to walk you through pulling the full dividend history. They can often send it via secure email within a few business days.
What the Numbers Actually Mean
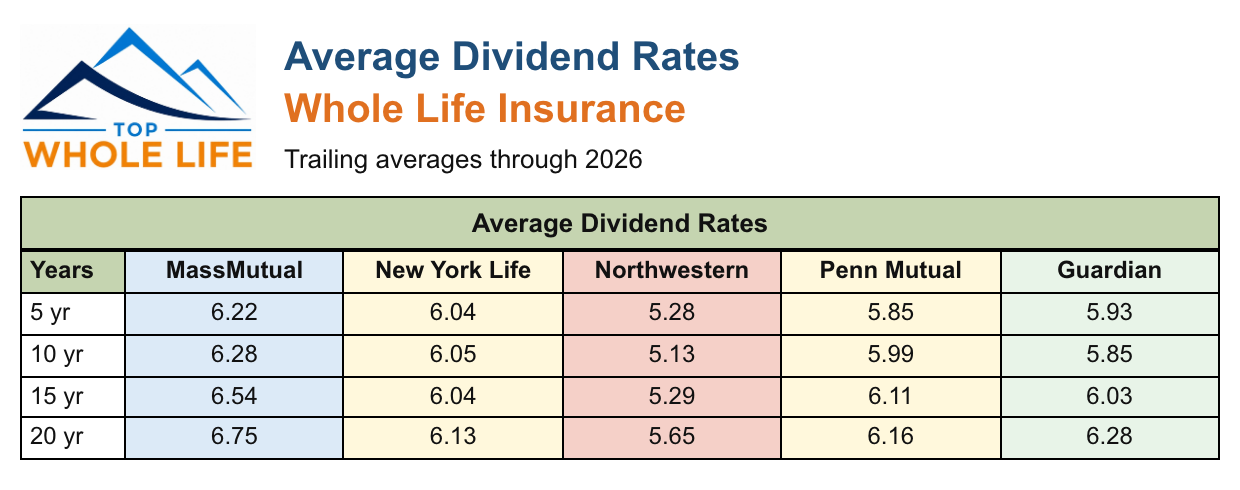
This is where most people get tripped up. MassMutual publishes two different dividend-related figures and they mean completely different things. The dividend scale is the current year's declared rate as a percentage of the policy's face amount. The historical dividend scale, which shows up in your annual illustration, reflects what was being used when that particular policy was issued. These two numbers rarely match, and confusing them will make your projections look wrong. MassMutual's participating whole life policies have one of the longest continuous dividend payment records in the industry. They've paid dividends every year since the company started issuing participating policies, which goes back to the late 1800s. That track record is why AM Best and the other rating agencies give them some of the highest grades in the industry for dividend continuity. But past payments don't guarantee future ones, and nobody at MassMutual will tell you that loudly enough. Here's a detail that matters and that almost no one explains: the dividend per thousand figure you see on your statement is calculated against your original face amount, not your current cash value. So if you bought a twenty thousand dollar policy and your dividend per thousand is four dollars, you're getting eight hundred dollars annually. That hasn't changed just because your cash value has grown to forty thousand. People frequently misread this as their returns compounding faster than they actually are.
Get the Full Details
A Problem I Ran Into
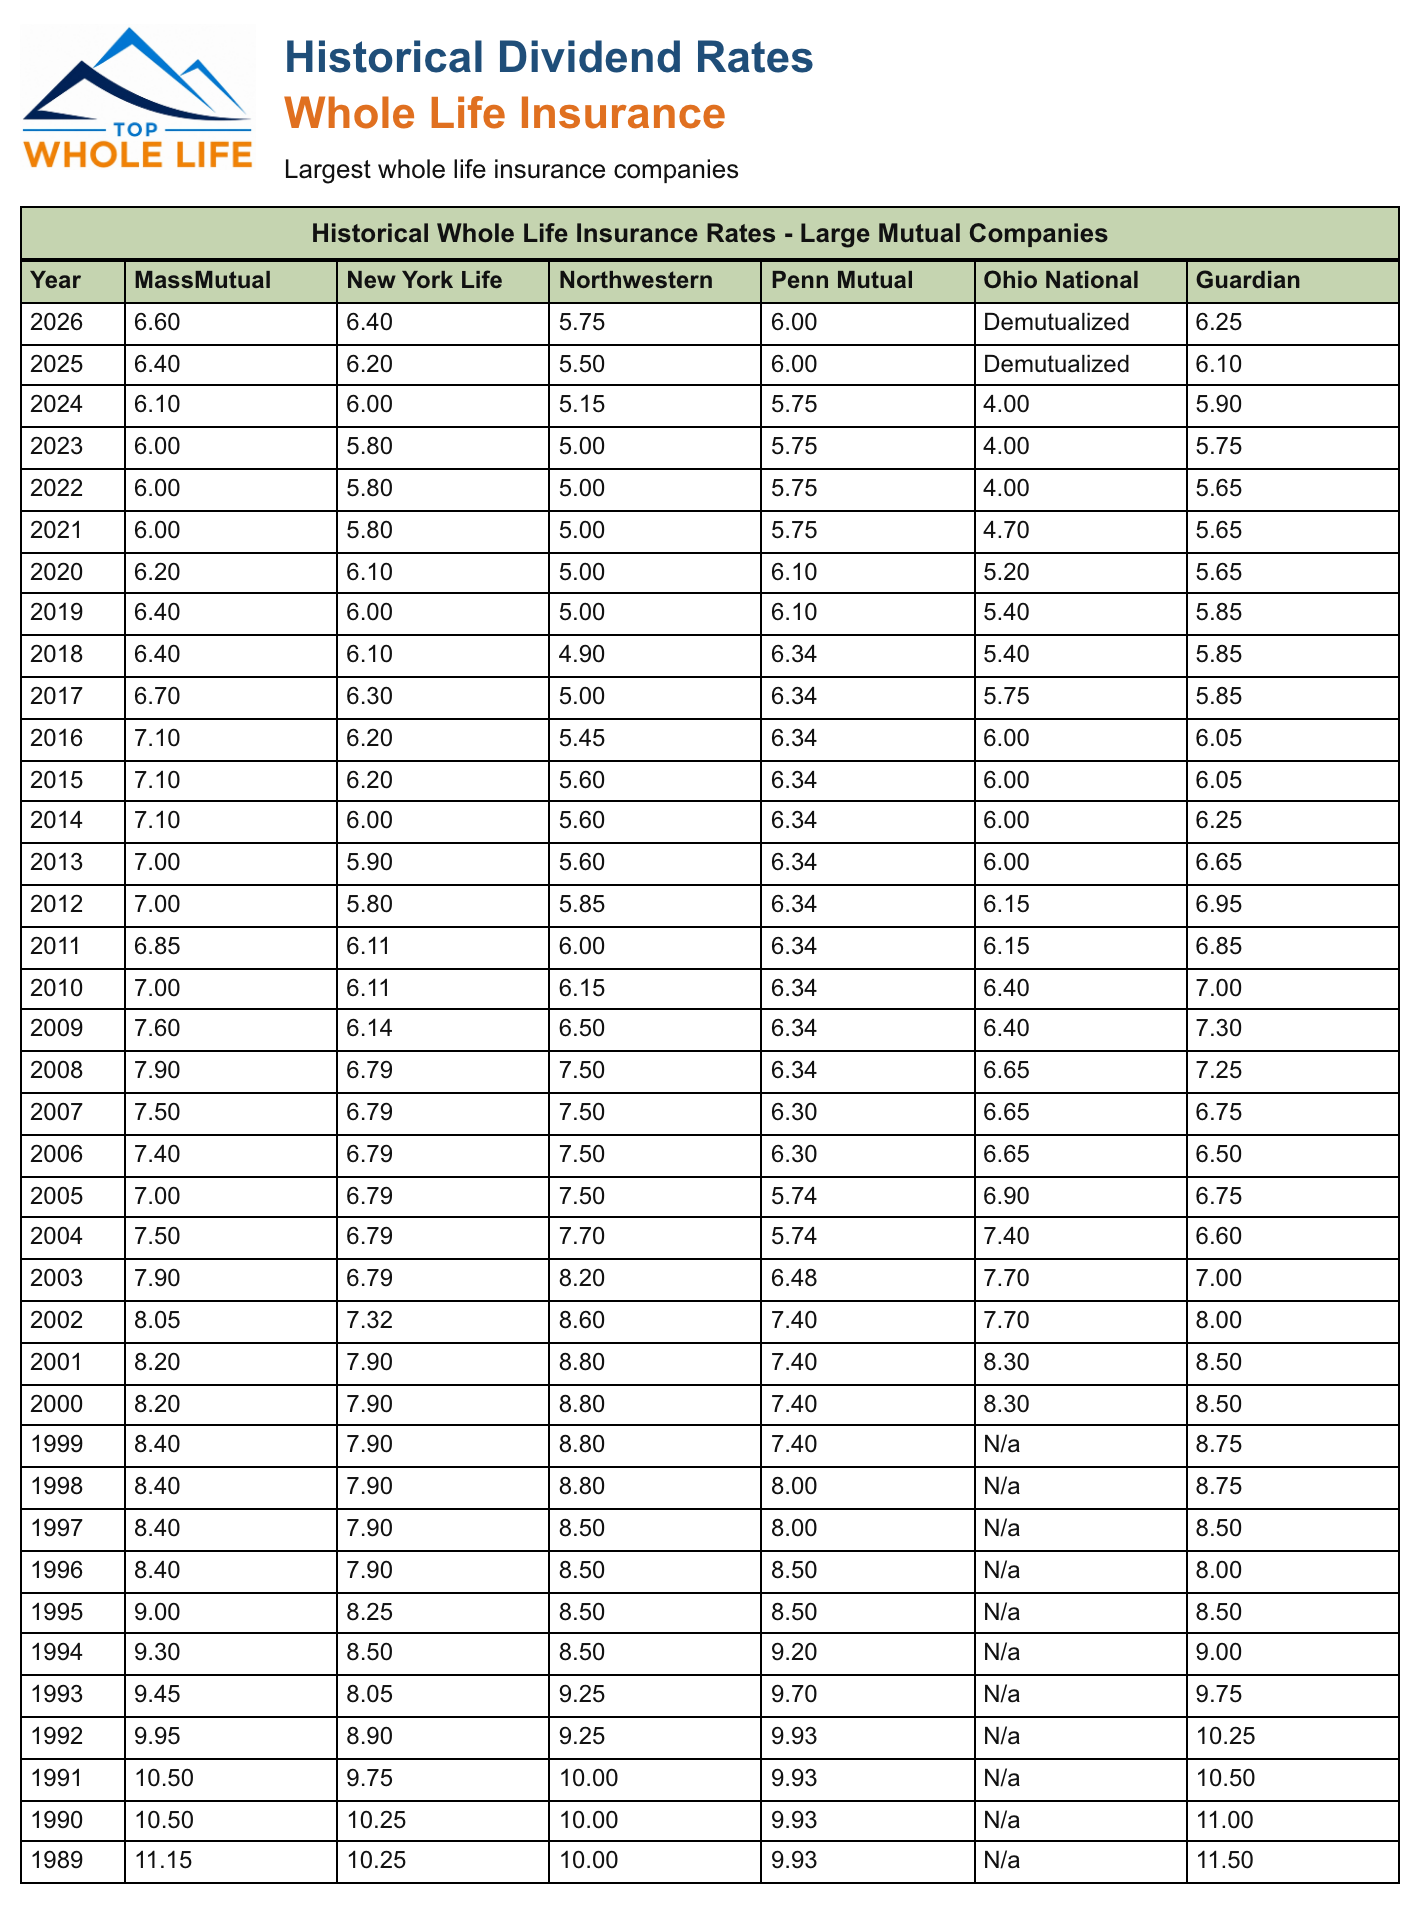
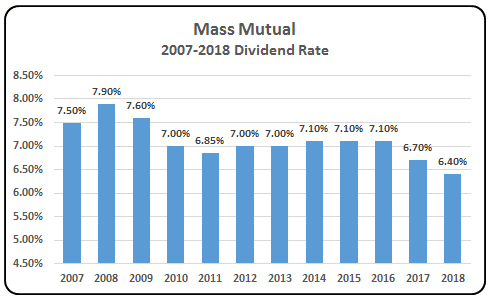
A few years ago I was reviewing a client's MassMutual whole life policy and noticed the dividend history file that downloaded from the portal was missing three years in the middle. Something like 2008, 2009, and 2010 were just blank gaps in the timeline. The policy had clearly been active the whole time because the cash value was growing. I spent about forty-five minutes on the phone with their support team before someone in the backend records department figured out that a system migration in their dividend processing had caused those years to not populate in the digital archive. The workaround was straightforward once I knew what to ask for. I requested the physical annual statements by mail instead of relying on the digital download. Each statement is a separate PDF and they take about five to seven business days to arrive. You can request up to twenty years at a time through their secure message center. Those paper statements filled in the gaps and included the actual dividend checks that were deposited, which confirmed the amounts matched what the policy illustration had always shown.
Pitfalls to Watch For
The biggest issue I see people run into is assuming the dividend history reflects guaranteed growth. Dividends on MassMutual whole life are non-guaranteed. The company's board of directors declares them annually based on actual experience — mortality, investment returns, and expense margins — against the assumptions built into the policy. In bad economic years, dividends can drop. They haven't gone to zero, but the scale has shifted downward before, most noticeably during the 2008 financial crisis when several carriers adjusted their scales significantly. Another thing that catches people off guard: the dividend history and the current policy illustration use different bases. Your annual illustration will show projected dividends using the current scale applied to the original face amount. But if your policy has paid return of premium dividends or if there have been any modifications, those can alter the effective dividend picture without showing up clearly in the historical table. Always cross-reference the dividend history against your latest in-force illustration, not just your original policy documents. One more nuance that's easy to miss. MassMutual offers different dividend options — cash, paid-up additions, premium offset, accumulated at interest, and so on. The dividend history shows the declared amount, but what you actually received depends entirely on which election you made each year. If you switched options mid-policy, the history will still list the same declared dividend but your cash value growth will tell a different story. I've seen people think their dividends were declining when actually they'd just been accumulating at a lower interest rate than they expected.
How Long It Takes and What to Expect
Downloading the digital dividend history from the portal takes maybe five minutes if the files are all there. Mailing requests for older years adds a week or two. If you need everything organized — say you're comparing multiple policies or preparing for a meeting with a financial advisor — I'd recommend spending a Saturday afternoon going through it methodically rather than rushing it. You'll miss important details if you skim. The bottom line is that Massmutual Whole Life Dividend History is thorough but not user-friendly by design. The data exists and it's accurate when you can get to it, but the company doesn't make it especially easy to access in a clean format. If you need it regularly for planning purposes, consider asking your agent or the company directly about bulk statement requests or periodic mailed copies. It saves you from having to log in and dig through the portal every time something comes up.