Working Through the Tax Calculations
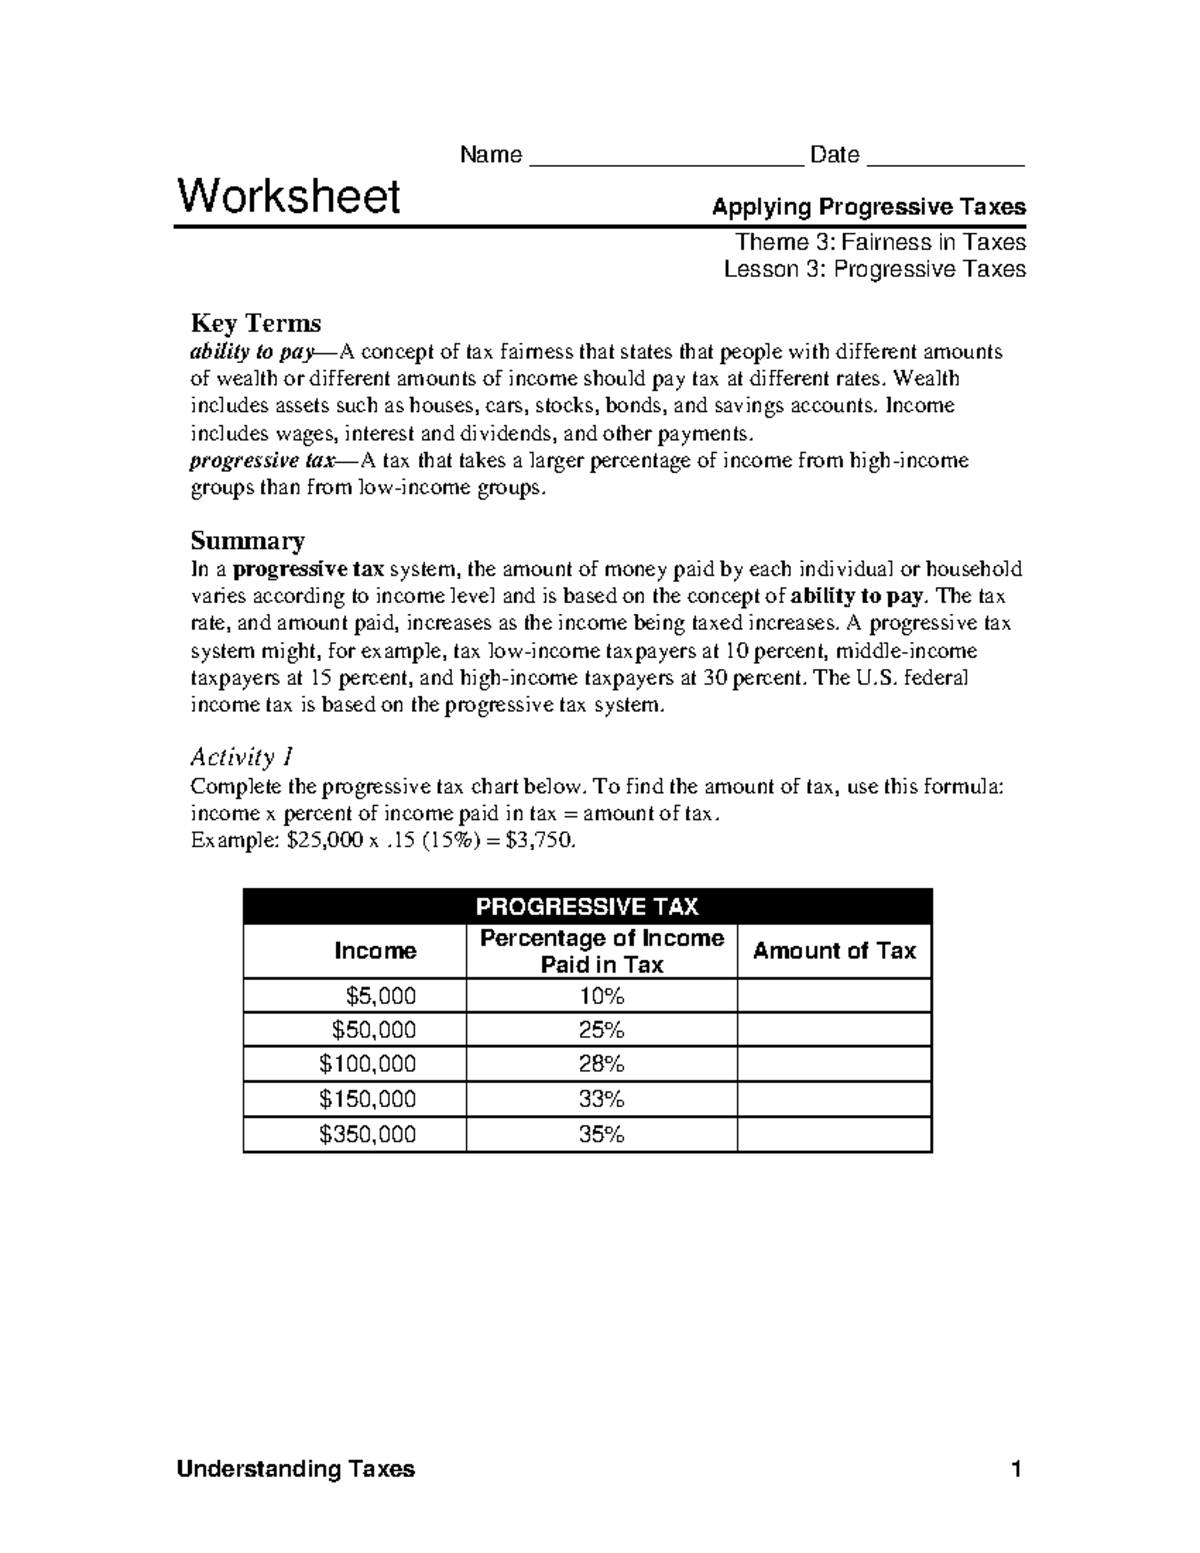
I've gone through enough of these practice sheets to know how they're structured and where students tend to mess up. Activity 14 is one of the more straightforward ones, but it still catches people off guard if they're not careful about the progressive tax brackets. The answer key for this activity covers the core skill of calculating income tax using given tax brackets. Most versions of this worksheet present a scenario where a student is given a taxable income figure and asked to compute the total tax owed by applying different rates to different portions of that income. The idea behind it is to teach progressive taxation, not just simple percentage multiplication. Here's how the method actually works in practice. Say your worksheet gives you a taxable income of $45,000 and the brackets are set up like this: 10% on the first $10,000, 15% on the next $20,000, and 25% on everything above $30,000. You don't just slap 25% on the whole amount. You calculate each tier separately. First $10,000 at 10% comes to $1,000. The next $20,000 at 15% comes to $3,000. The remaining $15,000 at 25% comes to $3,750. Add those together and the total tax is $7,750. That's the pattern across every problem in this activity.
I remember working through a version of this activity where the brackets were set differently than the standard model. The tax table listed marginal rates but didn't explicitly state the bracket boundaries in dollar amounts. Instead, it gave you cumulative income thresholds. A student who didn't read carefully would look at a 20% rate and apply it to their entire income because they assumed flat taxation. I caught this in my own grading once. A student calculated $60,000 times 20% and wrote $12,000 as the answer when the correct answer was $8,200. The mistake was treating a marginal rate as a flat rate. That mistake shows up in roughly one out of every four attempts on this activity. Another thing to watch for is whether the problem includes adjustments to income before tax calculation. Some versions of Activity 14 have a two-part setup where you first subtract deductions or exemptions from gross income to arrive at taxable income, then apply the brackets. If you skip the deduction step, your answer will be wrong even if your bracket math is perfect. I've seen this trip up students who jump straight to the tax tables without reading the full problem statement. Read the problem once all the way through before you start calculating. If you're looking for the answer key, most educators and textbook publishers make it available through their official resources pages. Check the publisher's website for the corresponding teacher edition or online resource center. The activity number and chapter should match the edition of your textbook. Some schools also post scanned copies on their learning management systems. The key typically lists the final answer for each problem plus the working steps, which is useful for checking your bracket calculations.
One counter-intuitive thing about this activity that beginners miss is that moving into a higher tax bracket doesn't mean your entire income gets taxed at that higher rate. Students often resist the concept because it feels like it should be simpler. The progressive structure means only the portion of income above each threshold gets taxed at the higher rate. This is why understanding marginal vs. average tax rates matters here. Your effective or average tax rate on $45,000 in the example above would be about 17.2%, not 25%. The worksheet may ask you to compute that as well, so be ready. There's also a rounding issue that sometimes appears. Depending on the problem, you might need to round to the nearest dollar or nearest cent. The answer key will specify, but if it doesn't, follow the convention used in earlier activities in the same chapter. Inconsistency on this point is another common source of errors. The main limitation of this activity is that it uses simplified brackets that don't reflect real IRS tax tables. Actual tax forms involve standard deductions, itemized deductions, credits, and phase-outs that this worksheet doesn't cover. It's good for learning the mechanics of progressive taxation, but it won't prepare you for filing actual taxes. If you want something closer to real-world application, look for activities that incorporate Form 1040-style problems with standard deductions and tax credits built in. Those give you a fuller picture without being overwhelming.
Get the Full Details
Another edge case I encountered involved problems where the taxable income fell exactly on a bracket boundary. Some worksheets have a question where income is exactly $30,000, and students get confused about whether to apply the next bracket's rate to that final dollar or stop at the previous rate. The answer is you stop. The $30,000th dollar is still within the second bracket. This kind of boundary question is designed to test whether you understand the bracket system or are just mechanically applying percentages. The answer key will confirm that no over-rounding or bracket creep occurs at exact boundaries. Working through these problems methodically—writing out each bracket calculation separately rather than trying to do it in your head—will reduce errors significantly. I usually recommend using a small table with columns for bracket range, rate, taxable amount in that bracket, and tax owed per bracket. It takes a little extra space but eliminates the most common mistakes I see. You'll finish the activity faster and with fewer corrections.