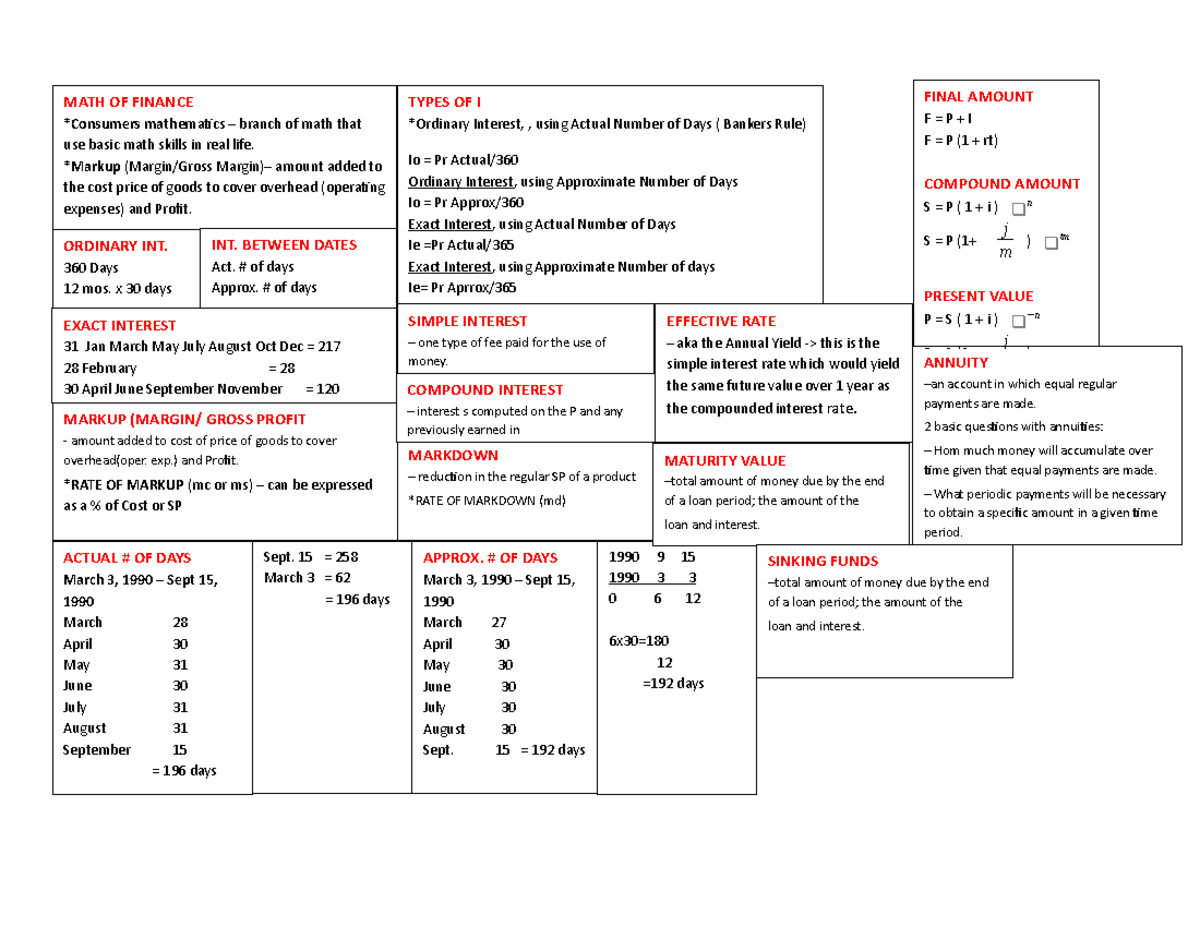
What these notes actually cover and how to use them
Most universities treat the mathematics of finance as a sequence of isolated formulas that happen to look like calculus. They aren't. The subject is really about compounding assumptions, cash flow timing, and the gaps between textbook idealizations and real market conventions. If you grab random lecture notes off a professor's website and try to memorize the formulas, you'll be able to pass a midterm and then fail immediately when someone asks you why a bond's yield changed while its price stayed flat for two days. I recommend starting with whatever set of Mathematics Of Finance Lecture Notes your institution provides, but treating it as a starting scaffold, not a curriculum. The notes will give you the standard notation and the standard derivations. That's useful. What the notes usually miss is the boundary condition where each formula breaks down, and that's where you actually learn the material.
Where to find Mathematics Of Finance Lecture Notes that aren't complete garbage
Clean sets tend to come from programs that treat the course as part of an actuarial or quantitative finance track. Look for notes associated with SOA Exam FM topics, MIT OpenCourseWare, or university departments that cross-list between mathematics and financial engineering. A decent set should have at least three components: discount factor derivations, annuity and bond valuation, and a section on interest rate modeling that doesn't stop at the flat term structure. If the notes jump from present value straight to Black-Scholes without covering duration, convexity, or bootstrapping, they're either oversimplified or misordered. I usually start by downloading three different sets and comparing how each handles the same topic, like the derivation of the Macaulay duration formula. One professor might derive it from first principles using a sum of weighted cash flows. Another might state it as a definition. A third will connect it to portfolio immunization in a way that actually matters for risk management. The truth sits somewhere in the overlap.
The core structure you need to understand before memorizing anything
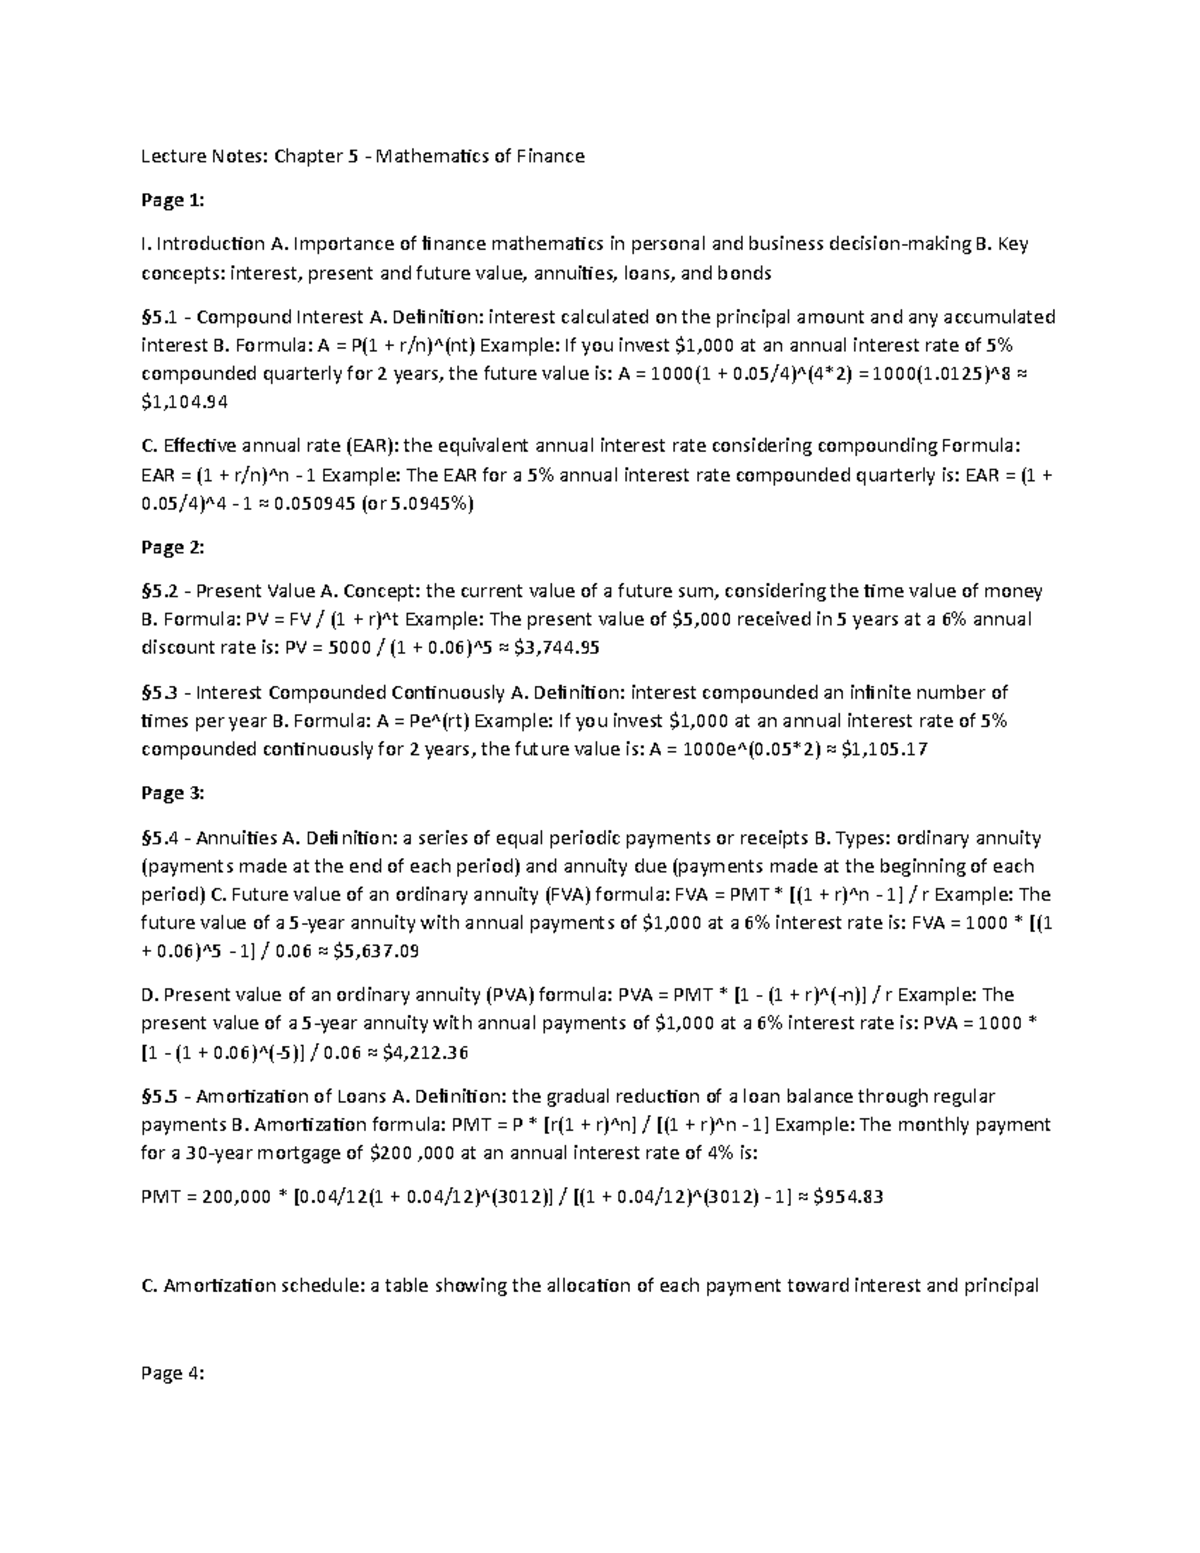
Everything in financial mathematics traces back to the concept of a discount factor. A discount factor converts a future cash flow into a present value based on an assumed rate of return over a specific time period. That sounds trivial until you deal with multiple currencies, stochastic rates, or illiquid markets, at which point the discount factor becomes the single most contested number in the model. From the discount factor, you build three parallel tracks. The first is annuity mathematics, which handles repeated cash flows under various timing assumptions. The second is fixed income valuation, which applies those same discounting principles to bonds with coupons, call features, and embedded options. The third is derivative pricing, which introduces the no-arbitrage assumption and risk-neutral valuation. Most lecture notes introduce these tracks in order, but they are logically independent once you understand the discounting foundation. You can study bonds without ever touching options if you want to, but you cannot understand options without understanding the discounting mechanism first. A practical warning: many students confuse the effective annual rate with the nominal rate compounded at some interval. These are not interchangeable. The effective rate E satisfies 1 plus E equals one plus r over n raised to the nth power, where r is the nominal rate and n is the compounding frequency. Mixing these up will cost you marks on an exam and money in a job. The difference between a 5 percent nominal rate compounded monthly and an effective annual rate of approximately 5.12 percent matters when you're discounting cash flows ten years out.
Get the Full Details
What lecture notes rarely explain well: the timing convention problem
The single most confusing aspect of financial mathematics for beginners is payment timing. Annuities due versus annuities immediate. Bonds settling on different dates than their coupon dates. Forward rate agreements with odd day-count conventions. Lecture notes usually present a clean timeline with payments at the end of each period and call it a day. Real problems are messier. I spent a week once trying to reconcile a pension liability projection where the payment schedule switched from monthly to quarterly mid-stream because of a plan amendment in year four. The standard annuity formulas in the notes assumed constant timing throughout. I ended up splitting the calculation into two segments, discounting the first four years with a monthly annuity factor and the remaining term with a quarterly annuity factor, then bridging them at the transition point using the appropriate accumulation factor. It added about an hour to the work but prevented a material misstatement. No textbook example I found covered that exact scenario. The workaround is always the same: identify where the convention changes, break the cash flow stream at that point, and apply the correct formula to each segment separately.
Bond valuation and why yield to maturity is misleading
Yield to maturity is the internal rate of return on a bond assuming you hold it to maturity and all coupons are reinvested at the same yield. That second assumption is almost never true. In practice, coupon reinvestment happens at whatever short-term rates are available at the time, which can differ significantly from the YTM you calculated at purchase. Duration measures the sensitivity of a bond's price to changes in yield, but it assumes a parallel shift in the yield curve. When the curve steepens or flattens, duration becomes an approximation, not an exact measure. Convexity corrects for the curvature in the price-yield relationship. Including convexity in your calculations usually improves accuracy by enough to matter when yields move more than fifty basis points. Most introductory notes mention convexity in a single paragraph. You should spend more time on it than they do. Here's a counter-intuitive point that trips people up regularly: a zero-coupon bond has the highest duration of any bond with the same maturity because all of its cash flow is concentrated at a single point in time. Par bonds have lower duration because the earlier coupon payments pull the weighted average timing forward. This means that in a rising rate environment, zero-coupon bonds suffer larger price declines than par bonds of the same maturity, despite having no coupons to reinvest at lower rates.
Interest rate models and what they actually assume
The Vasicek model assumes mean reversion in interest rates with normally distributed shocks. The Cox-Ingersoll-Ross model adds a square-root diffusion term that keeps rates non-negative. The Hull-White model extends Vasicek with a time-dependent drift. Each model makes tradeoffs between mathematical tractability and realistic behavior. If you're using lecture notes that present only the Vasicek model and call it sufficient, those notes are incomplete for practical purposes. The Vasicek model can produce negative interest rates, which may be appropriate in a low-rate environment but becomes problematic when you're calibrating to a market with positive rates and expecting stability. The CIR model prevents negative rates but introduces more complex mathematics. Hull-White gives you flexibility but requires numerical methods for many applications. One limitation worth noting: these models assume you can calibrate them to observable market data. In thin or stressed markets, calibration becomes unreliable. When I worked on a project during a period of abnormal volatility, the implied volatility surface was so distorted that standard calibration techniques produced parameter estimates that made no economic sense. The workaround was to impose bounds on the mean reversion speed and use a subset of liquid instruments for calibration rather than attempting a full-surface fit. The resulting model was less precise but more stable under stress.
Derivative pricing: the no-arbitrage assumption and its cracks
The Black-Scholes model rests on several assumptions: constant volatility, continuous trading, no transaction costs, and a lognormal distribution of asset prices. None of these hold perfectly in reality. Volatility is stochastic. Markets close. Transaction costs exist. Returns exhibit fat tails. The model still produces useful prices, but you need to understand where it deviates and by how much. The Greeks in Black-Scholes, particularly delta and gamma, are the primary hedging tools derived from the model. Delta tells you how much the option price changes relative to a small change in the underlying asset price. Gamma tells you how delta changes. In practice, hedging with delta alone is insufficient because gamma exposure causes the hedge to drift as prices move. A portfolio that is delta-neutral at one moment becomes directionally exposed as the underlying price changes, and you need to rebalance based on gamma considerations. Most introductory notes introduce the Greeks but don't emphasize how quickly delta becomes stale in volatile conditions. Another nuance that lecture notes often skip: the Black-Scholes framework assumes a single numeraire, typically the money market account. In multi-currency or multi-asset contexts, changing the numeraire simplifies calculations significantly. The forward measure, for example, makes certain option pricing problems trivial compared to the risk-neutral measure. This isn't advanced exotic theory. It's standard practice in any quantitative desk that prices cross-currency products, and it's usually absent from undergraduate lecture materials.
How to study from these notes effectively
Work through the derivations yourself. Don't just read them. A derivation that takes you twenty minutes to reproduce from first principles teaches you more than a derivation you read twice. The goal is to be able to reconstruct the key formulas without looking, not to recognize them on sight. Practice with problems that have messy parameters. Real exam questions and real job tasks rarely use round numbers and integer periods. Practice with semi-annual coupons on bonds that settle between coupon dates. Practice with annuities that have deferred starts or variable payment amounts. The effort of handling these edge cases compounds over time. Compare your answers against multiple sources. If one lecture note set gives a different approach to the same problem, trace through both and check whether they arrive at the same result. Disagreements between sources usually reveal a difference in convention or an error in one of them. Either way, resolving the discrepancy forces you to understand the material more deeply.
When lecture notes are not enough
If your notes don't cover stochastic calculus, bootstrapping procedures, or Monte Carlo simulation methods, don't treat that as a failure of the notes. Treat it as a signal that your course or your goals require supplementary material. Numerical methods are increasingly important in finance. Closed-form solutions are elegant but limited. Understanding how to simulate paths, price American options with binomial trees, or calibrate models to market data will serve you better than memorizing every formula in a standard set of Mathematics Of Finance Lecture Notes. The material is internally consistent once you accept the assumptions. The assumptions themselves are where the real work lives. Recognizing which assumptions your problem demands and which ones you need to relax is the skill that separates someone who can solve textbook exercises from someone who can price a real product.