Understanding How Medicaid Income Limits Work in New York for 2025
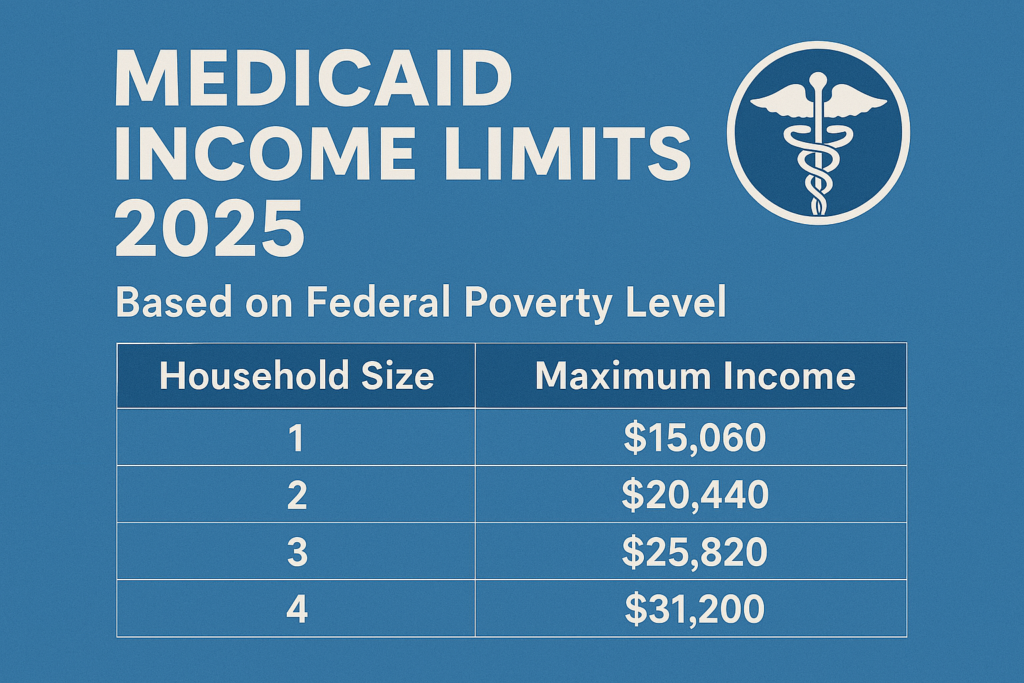
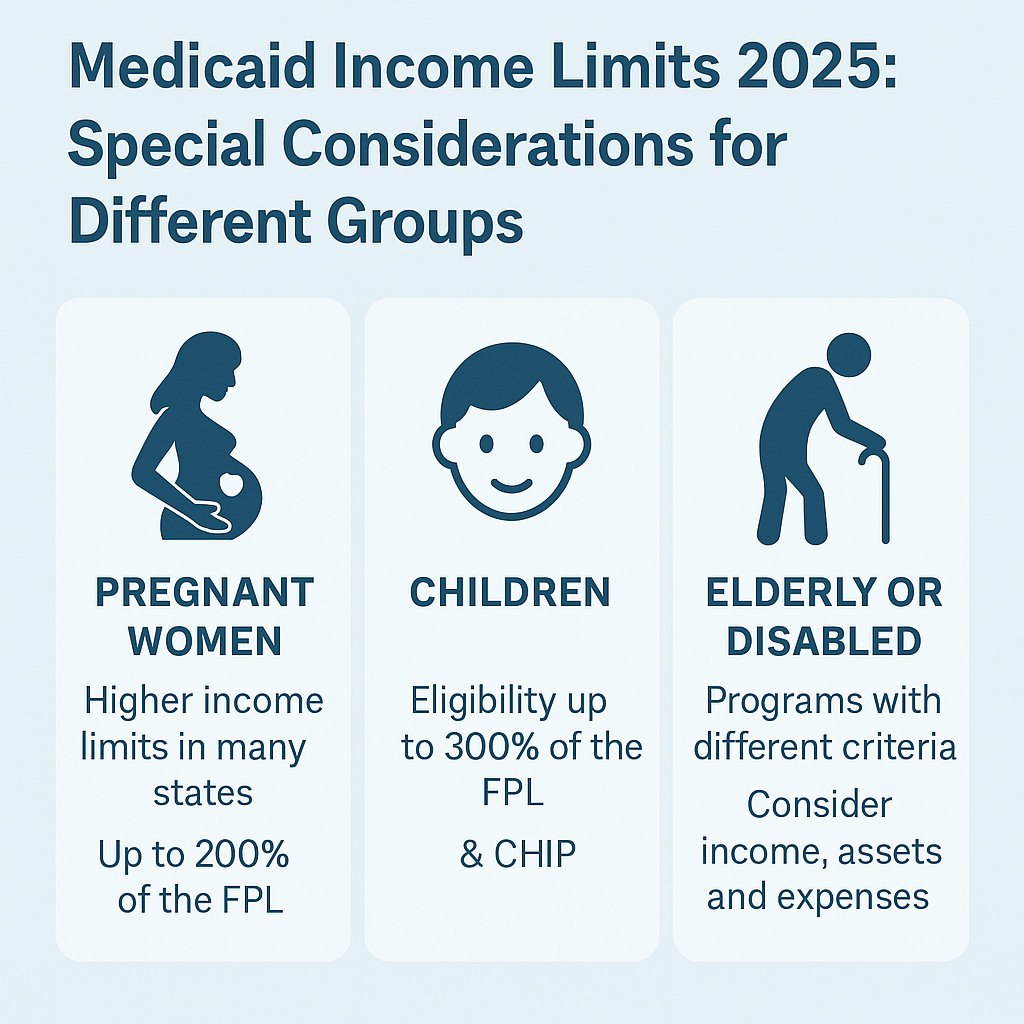
New York uses Modified Adjusted Gross Income as the baseline for most Medicaid eligibility programs. This is important because MAGI includes more than just your salary. It pulls in interest, dividends, capital gains, and certain business income that people often forget about when they're trying to estimate whether they qualify. The state then compares that number against published limits that change every January. For adults expanding under the Affordable Care Act, the limit sits at 138% of the Federal Poverty Level, which comes out to approximately $20,783 for an individual and $35,268 for a family of four. Those are the baseline figures. There are nuances that aren't obvious until you're actually filling out the application. The children's Health Haven Plus program runs higher. Kids up to age 19 can qualify at 264% of FPL for an individual. That's roughly $42,518. Parents and pregnant women fall under separate rules in some cases, and the state treats certain income types differently depending on which program you're applying through.
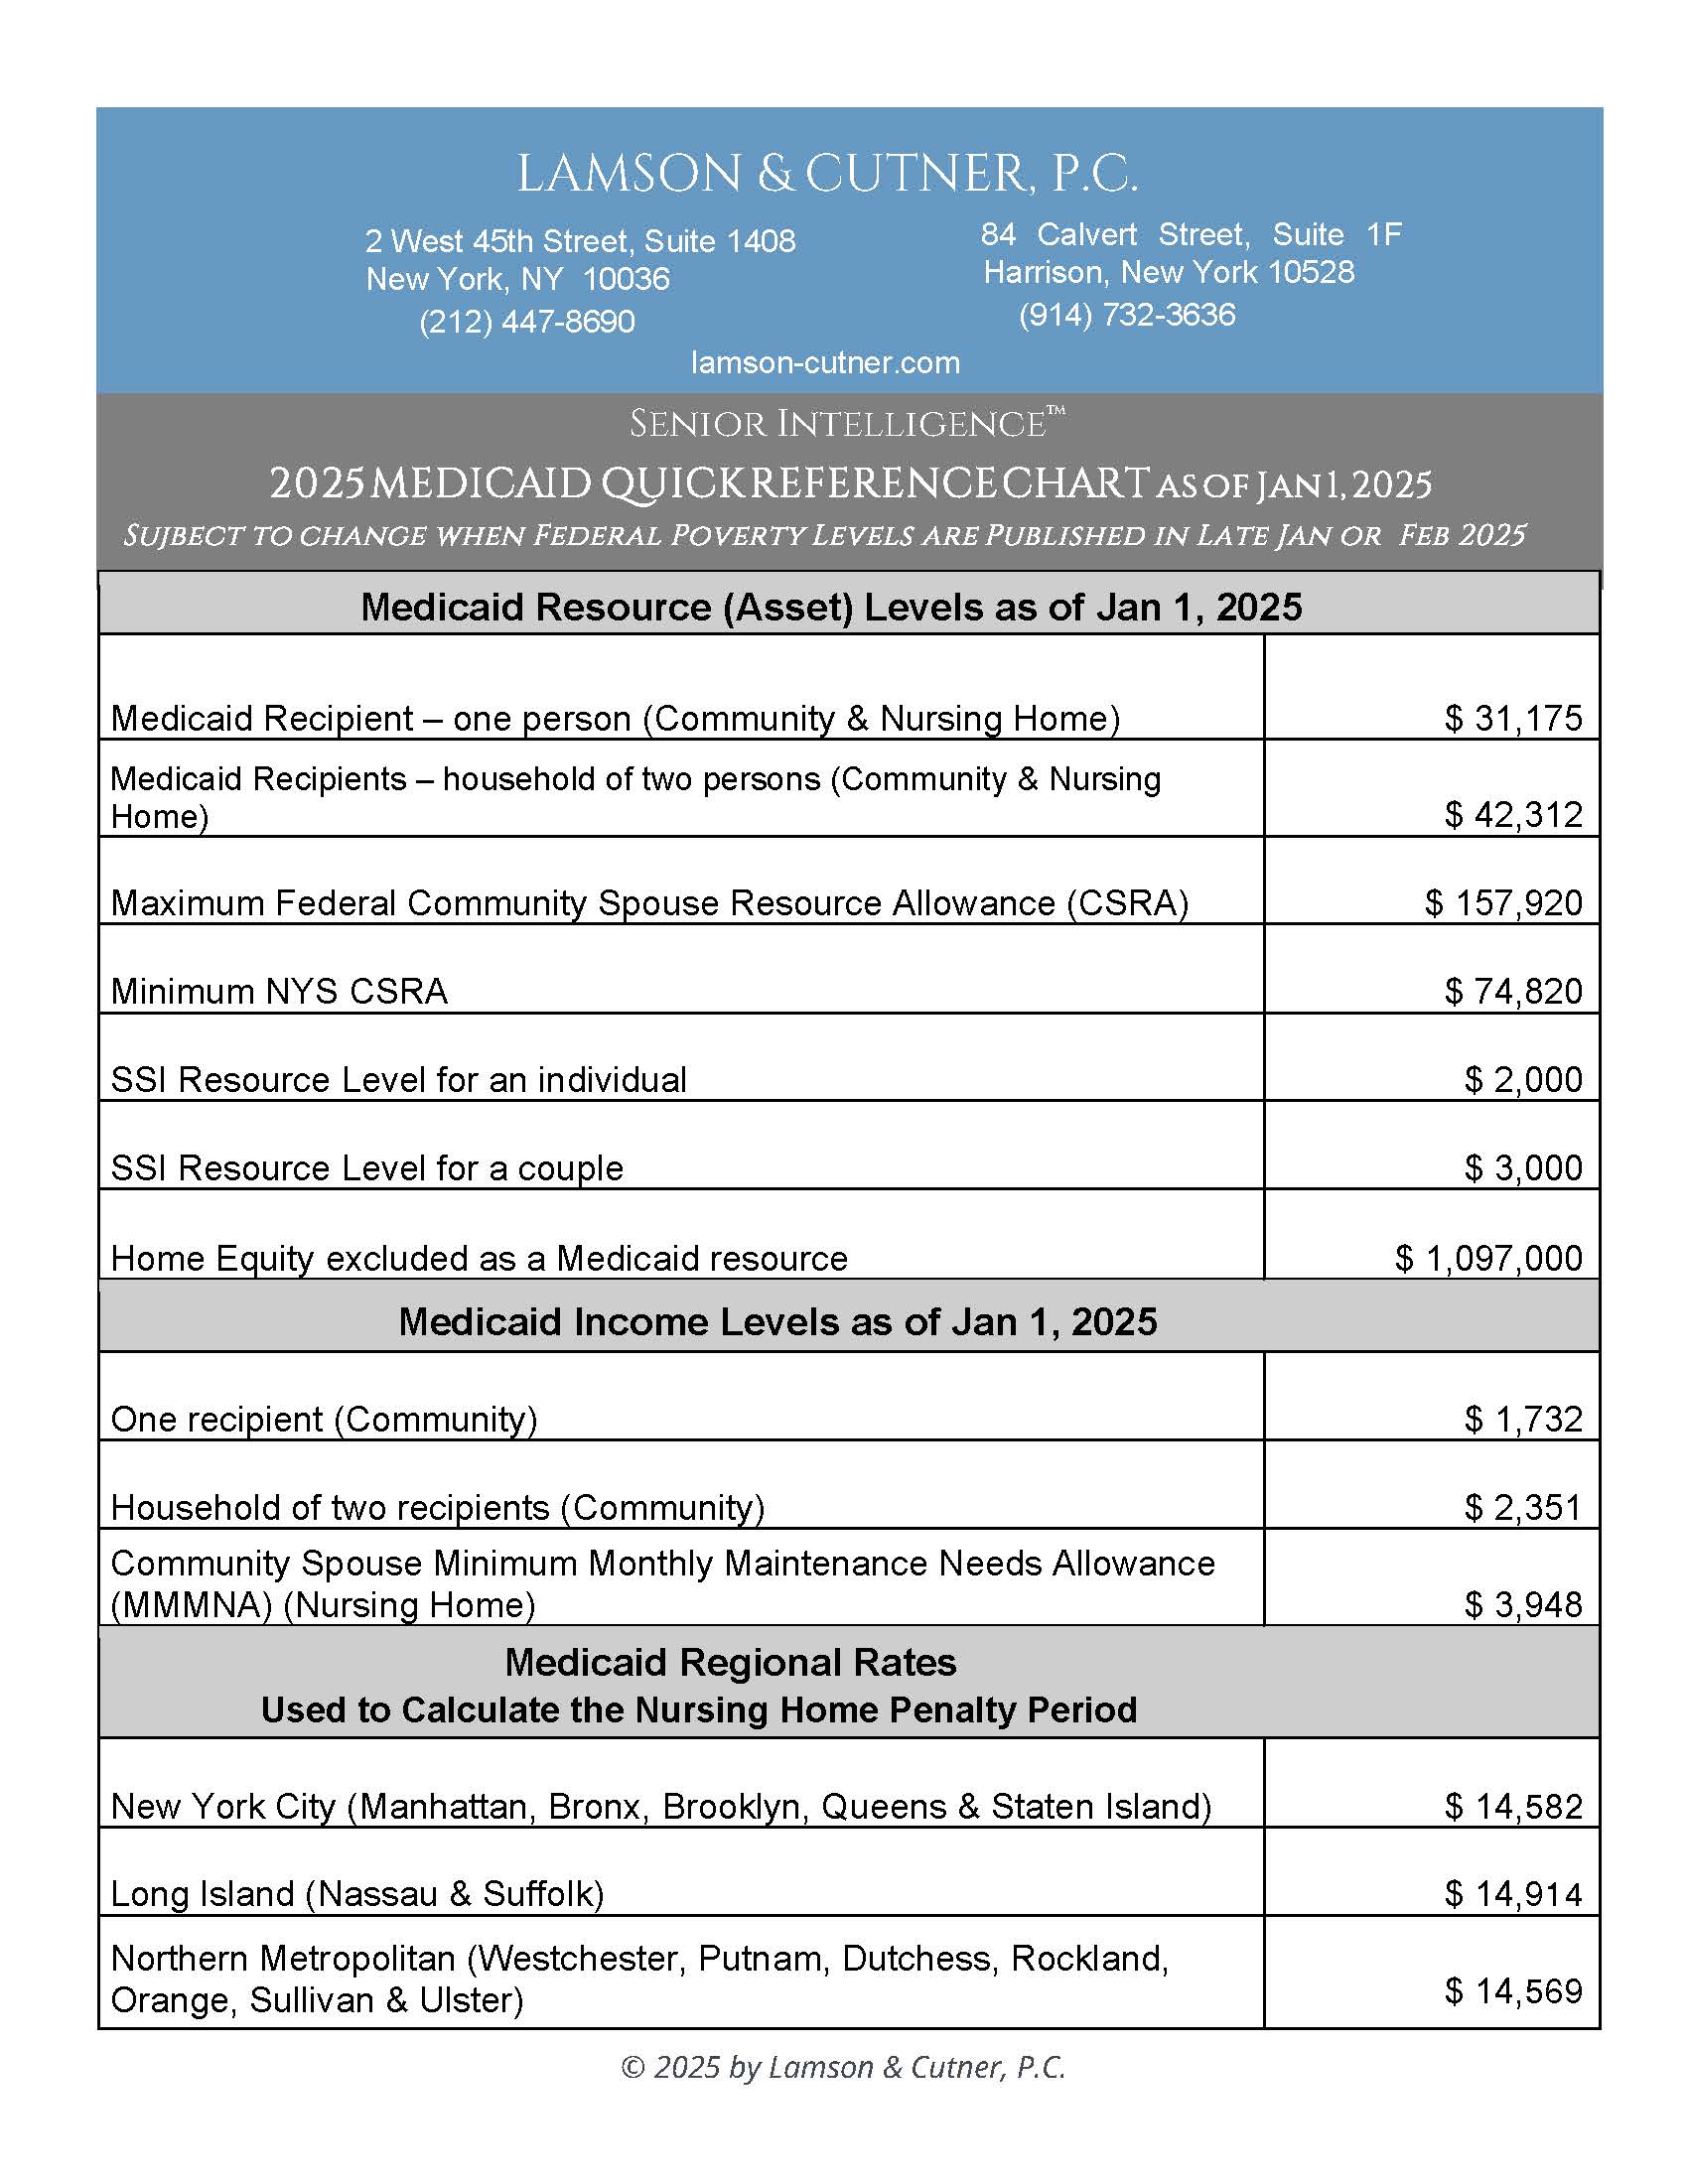
For long-term care Medicaid, which is where things get complicated, the income limits are entirely different. A single applicant can generally earn up to $935 per month in 2025 before it becomes a problem. A married couple where one spouse needs nursing home care has a Combined Monthly Income amount that's higher, but the healthy spouse is entitled to a Minimum Monthly Needs Allowance of roughly $2,740.50. Any income above the single limit gets redirected into a Qualified Income Trust, also called a Miller Trust, to preserve eligibility.
How the Calculation Actually Works in Practice
When someone walks into a county social services office or applies online through the NY State of Health marketplace, the system doesn't just look at last year's tax return. It looks at projected annual income. That means if you had a low-income year in 2024 because you were between jobs, the system may still count your pre-unemployment earnings from earlier in the year. I learned this the hard way with a client who'd switched from full-time employment to contract work partway through the year. Her 2024 W-2 showed strong income, but her actual 2025 monthly take-home was well below the threshold. The automated system initially flagged her for over-income, and we had to submit a statement of projected monthly income along with recent pay stubs to override the presumption. Here's something most people don't realize: New York counts income differently than some other states do for certain programs. The state offers its own supplemental Medicaid pathways that go beyond the federal MAGI rules, particularly for elderly or disabled applicants who aren't part of the expansion population. If you're over 65 or receiving SSI, you're not judged solely by income limits. You also have to meet asset tests, which in 2025 allow roughly $1,000 in countable assets for an individual and $1,500 for a couple in many categories. Another detail that trips people up involves earned versus unearned income. Earned income gets a standard deduction of $65 plus half of the remaining earned income. Unearned income like Social Security benefits or pension payments gets a $20 general deduction first. So two people earning the same gross amount can have very different countable incomes depending on where that money comes from. I had a retiree once who thought he was over the limit because his Social Security check came in above the threshold. Once we applied the deductions properly, his countable income dropped enough to qualify under the Aged/Blind/Disabled pathway instead of the expansion track.
Get the Full Details
Where the System Breaks Down
The biggest issue with Medicaid Income Limits Ny 2025 is that the rules change depending on who you are and what program you're applying for. There is no single number that covers everything. The expansion adult limit, the children's limit, the long-term care limit, and the exempt community spouse rules all operate on different calculations. This fragmentation means a family could have one member qualify under the higher children's threshold while another adult in the same household gets denied because their income exceeds the expansion limit. Asset-based programs like long-term care Medicaid also have a five-year lookback period for transfers. If you gifted money or property to adult children within 60 months of applying, the state imposes a penalty period of ineligibility calculated by dividing the total transferred value by the average monthly cost of nursing home care in your region. In New York, that divisor varies by county but typically falls between $10,000 and $14,000 per month. A $50,000 gift could mean roughly four to five months of denied coverage, which is devastating if the care is needed immediately. The application process itself is another bottleneck. Processing times through the county can stretch from two to eight weeks depending on staffing and how complete your documentation is. If you apply during open enrollment and the system requests additional verification, you can lose coverage retroactively if you don't respond quickly enough. I've seen cases where people were approved but then lost benefits for 30 days because they didn't return a requested bank statement within the window.
What You Can Do About It
If your income is slightly above the threshold, there are legitimate strategies. A Health Savings Account or Flexible Spending Account can reduce your MAGI by allowing pre-tax contributions. For long-term care scenarios, a Qualified Income Trust is the standard tool, though it requires setting up a separate bank account and filing annual accounting statements with the county. Some people use irrevocable trusts for asset protection, but those come with their own legal costs and timing constraints that make them unsuitable for urgent applications. The official resource for current figures is the NY State Department of Health website and the NY State of Health marketplace at nystateofhealth.ny.gov. The federal poverty guidelines published annually by the HHS can be found at hhs.gov. County social services offices handle the non-MAGI programs and long-term care applications directly, so you'll need to contact your specific county rather than relying on a single state-wide portal for those cases. The numbers I've cited reflect the 2025 federal poverty level adjustments and the corresponding New York state adaptations. They are subject to change each year, and individual circumstances can shift your eligibility in ways these general figures don't capture. If your situation involves irregular income, self-employment, or any asset transfers in the past five years, working with a New York elder law attorney or a certified navigator through the health insurance marketplace will save you more time than guessing through the application alone.