How the paperwork actually works when you hit 65
I spent about three years helping people sort through Medicare enrollment after their first hospitalization, and the thing that almost always trips them up is not the medical coverage itself. It is the timing. The social security administration sends you a packet around your 64th birthday with a welcome letter, but reading it straight through without understanding what the boxes mean is like staring at a wiring diagram with no labels. People think they can just wait and figure it out, then realize they missed an eight-week window and have coverage gaps they did not see coming. The original Medicare framework splits into Part A and Part B, with Part A covering inpatient stays and Part B covering outpatient visits and physician services. Part C is what they call Medicare Advantage, which bundles everything through private insurers. Part D is the stand-alone drug coverage piece. That basic shape is in every brochure, but the part most people ignore is the income-related monthly adjustment amount, or IRMAA, which kicks in based on your tax return from two years back. If your modified adjusted gross income pushes past certain thresholds, your Part B premium jumps significantly, and that surcharge stays with you for the entire year regardless of what happens to your income later.
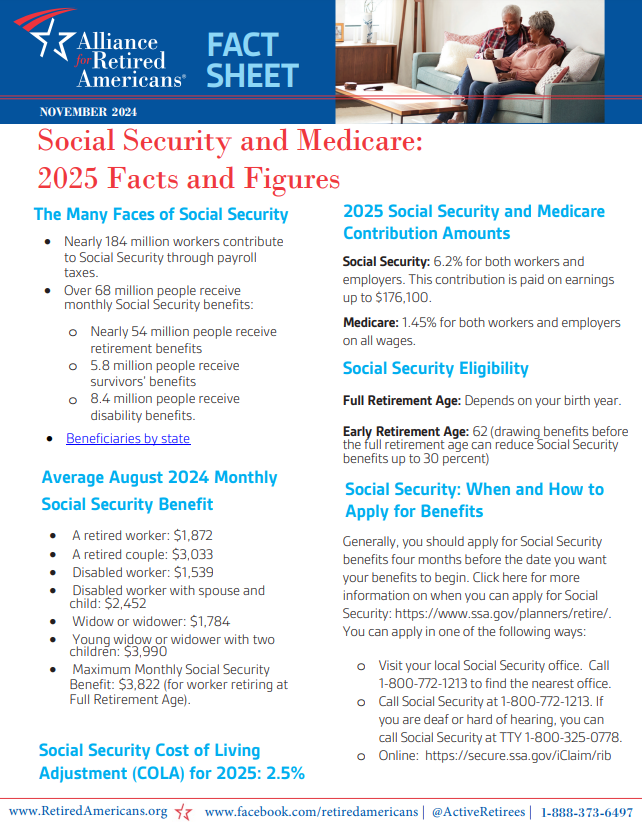
Medicare And Social Security Cheat Sheet
I built this reference after watching the same confusion repeat across dozens of cases, usually when someone needed to coordinate disability conversion with Medicare eligibility. The social security disability program transitions to Medicare after a twenty-four month waiting period, and the clock starts from your established onset date, not from when the award letter arrives. That distinction matters because people often assume the two years runs from approval, when it actually runs from the date disability began, which can shift the entire timeline by months. The cheat sheet below breaks down the enrollment windows, premium ranges, and the most common penalties into a single page so you do not have to flip between four different government sites. I included the 2025 and 2026 premium brackets because the numbers change every year, and relying on last year's figures will cost you if you are estimating out of pocket costs.
General Enrollment Period: January 1 through March 31 each year. Coverage starts the first day of the month after you enroll, with a premium penalty that adds ten percent for each full twelve-month period you were eligible but did not sign up. Initial Enrollment Period: Seven months total, beginning three months before the month you turn 65, including your birthday month and ending three months after. This is the window you want to hit if you are not already receiving social security benefits at that point. Special Enrollment Period: Available if you have credible employer coverage through active employment. You can delay Part B without penalty while you or your spouse is still working and covered by a group health plan. The clock for your SEP starts the month employment ends or the coverage terminates, whichever comes first, and you get eight months to enroll before the general enrollment penalty kicks in.I ran into a case where a retired municipal worker thought his retiree health plan counted as credible coverage. It did not. The SEP only applies to current group health insurance from active employment, not to retiree plans or COBRA. He enrolled during general enrollment by mistake, paid the penalty for eighteen months, and then spent another six months trying to get the penalty waived. The waiver process exists but is not guaranteed, and they look at whether you had a reasonable explanation for missing the window. The social security side of this equation has its own set of traps that are easy to miss if you are focused only on Medicare. The earliest you can claim retirement benefits is age sixty-two, but claiming that early locks you into a reduced amount for life. The reduction calculates to about seven and two-thirds percent per year before full retirement age, so claiming at sixty-two instead of waiting until full retirement age shrinks your monthly benefit by roughly twenty-five percent. Full retirement age depends on your birth year, sitting anywhere between sixty-six and sixty-seven for people born between nineteen thirty-eight and one fifty four. Waiting past full retirement age earns delayed retirement credits of about eight percent per year until age seventy, and those credits do not compound. They are a straight eight percent add-on for each year you delay, capped at seventy. Spousal benefits and survivor benefits follow separate calculation tracks. A spouse who has not worked enough to qualify on their own can still receive up to half of the worker's benefit at full retirement age. Survivor benefits reach one hundred percent of what the deceased was receiving or would have been entitled to, but there is a marriage duration requirement of at least nine months in most cases. The nine month rule has exceptions for accidental death and certain domestic violence situations, but those require documentation that not everyone has on hand.
Get the Full Details

The Medicare And Social Security Cheat Sheet also covers the Medicaid spike strategy, which is not a trick but a legitimate planning method for people with limited assets who face long term care costs. Medicaid eligibility thresholds vary by state, but the asset test usually sits around two thousand dollars for an individual and six thousand for a couple in most jurisdictions. When someone spends down to those limits, they can qualify for Medicaid to cover nursing home costs while preserving a small amount of equity. The look back period for asset transfers is sixty months in most states now, so moving money around without professional guidance within that window triggers penalty periods that delay coverage. I handled a situation where a client transferred a vehicle title to an adult child to get under the asset limit, then found out the county considered the fair market value rather than the purchase price. The car was worth eight thousand, which pushed them well over the threshold. They had to sell it at a documented loss to a salvage dealer and provide the bill of sale showing the reduced value. The process took about three weeks and required three separate forms filed with different offices, which is exactly the kind of friction a cheat sheet helps you anticipate before you hit it. The download link below leads to a printable version formatted for standard letter paper, with the premium tables, enrollment dates, and penalty calculations all on one or two pages so you can actually use it at a kitchen table without scrolling through a phone screen. The PDF includes a section on the social security earnings test, which penalizes you for working while drawing benefits before full retirement age. In twenty twenty five, you can earn up to twenty one thousand six hundred dollars annually without any withholding. Above that limit, social security withholds one dollar for every two dollars you earn. During the year you reach full retirement age, the limit jumps to fifty seven thousand five hundred, and the withholding rate drops to one dollar for every three dollars above that threshold. Once you hit full retirement age, there is no earnings limit at all, and any benefits withheld earlier in the year get recalculated and repaid as a retroactive increase.
The cheat sheet does not cover every edge case because the rules change frequently and some exceptions depend on state specific medicaid programs, tribal status, or military service history. If you are an active duty member enrolling near retirement, or if you live in a territory like Guam or the Virgin Islands where Medicare rules differ slightly, you should cross reference the local social security office guidance before relying solely on these numbers. The base framework holds for the vast majority of people, but the edge cases are where the penalties accumulate fastest.
Download the Medicare And Social Security Cheat Sheet