What This Actually Is
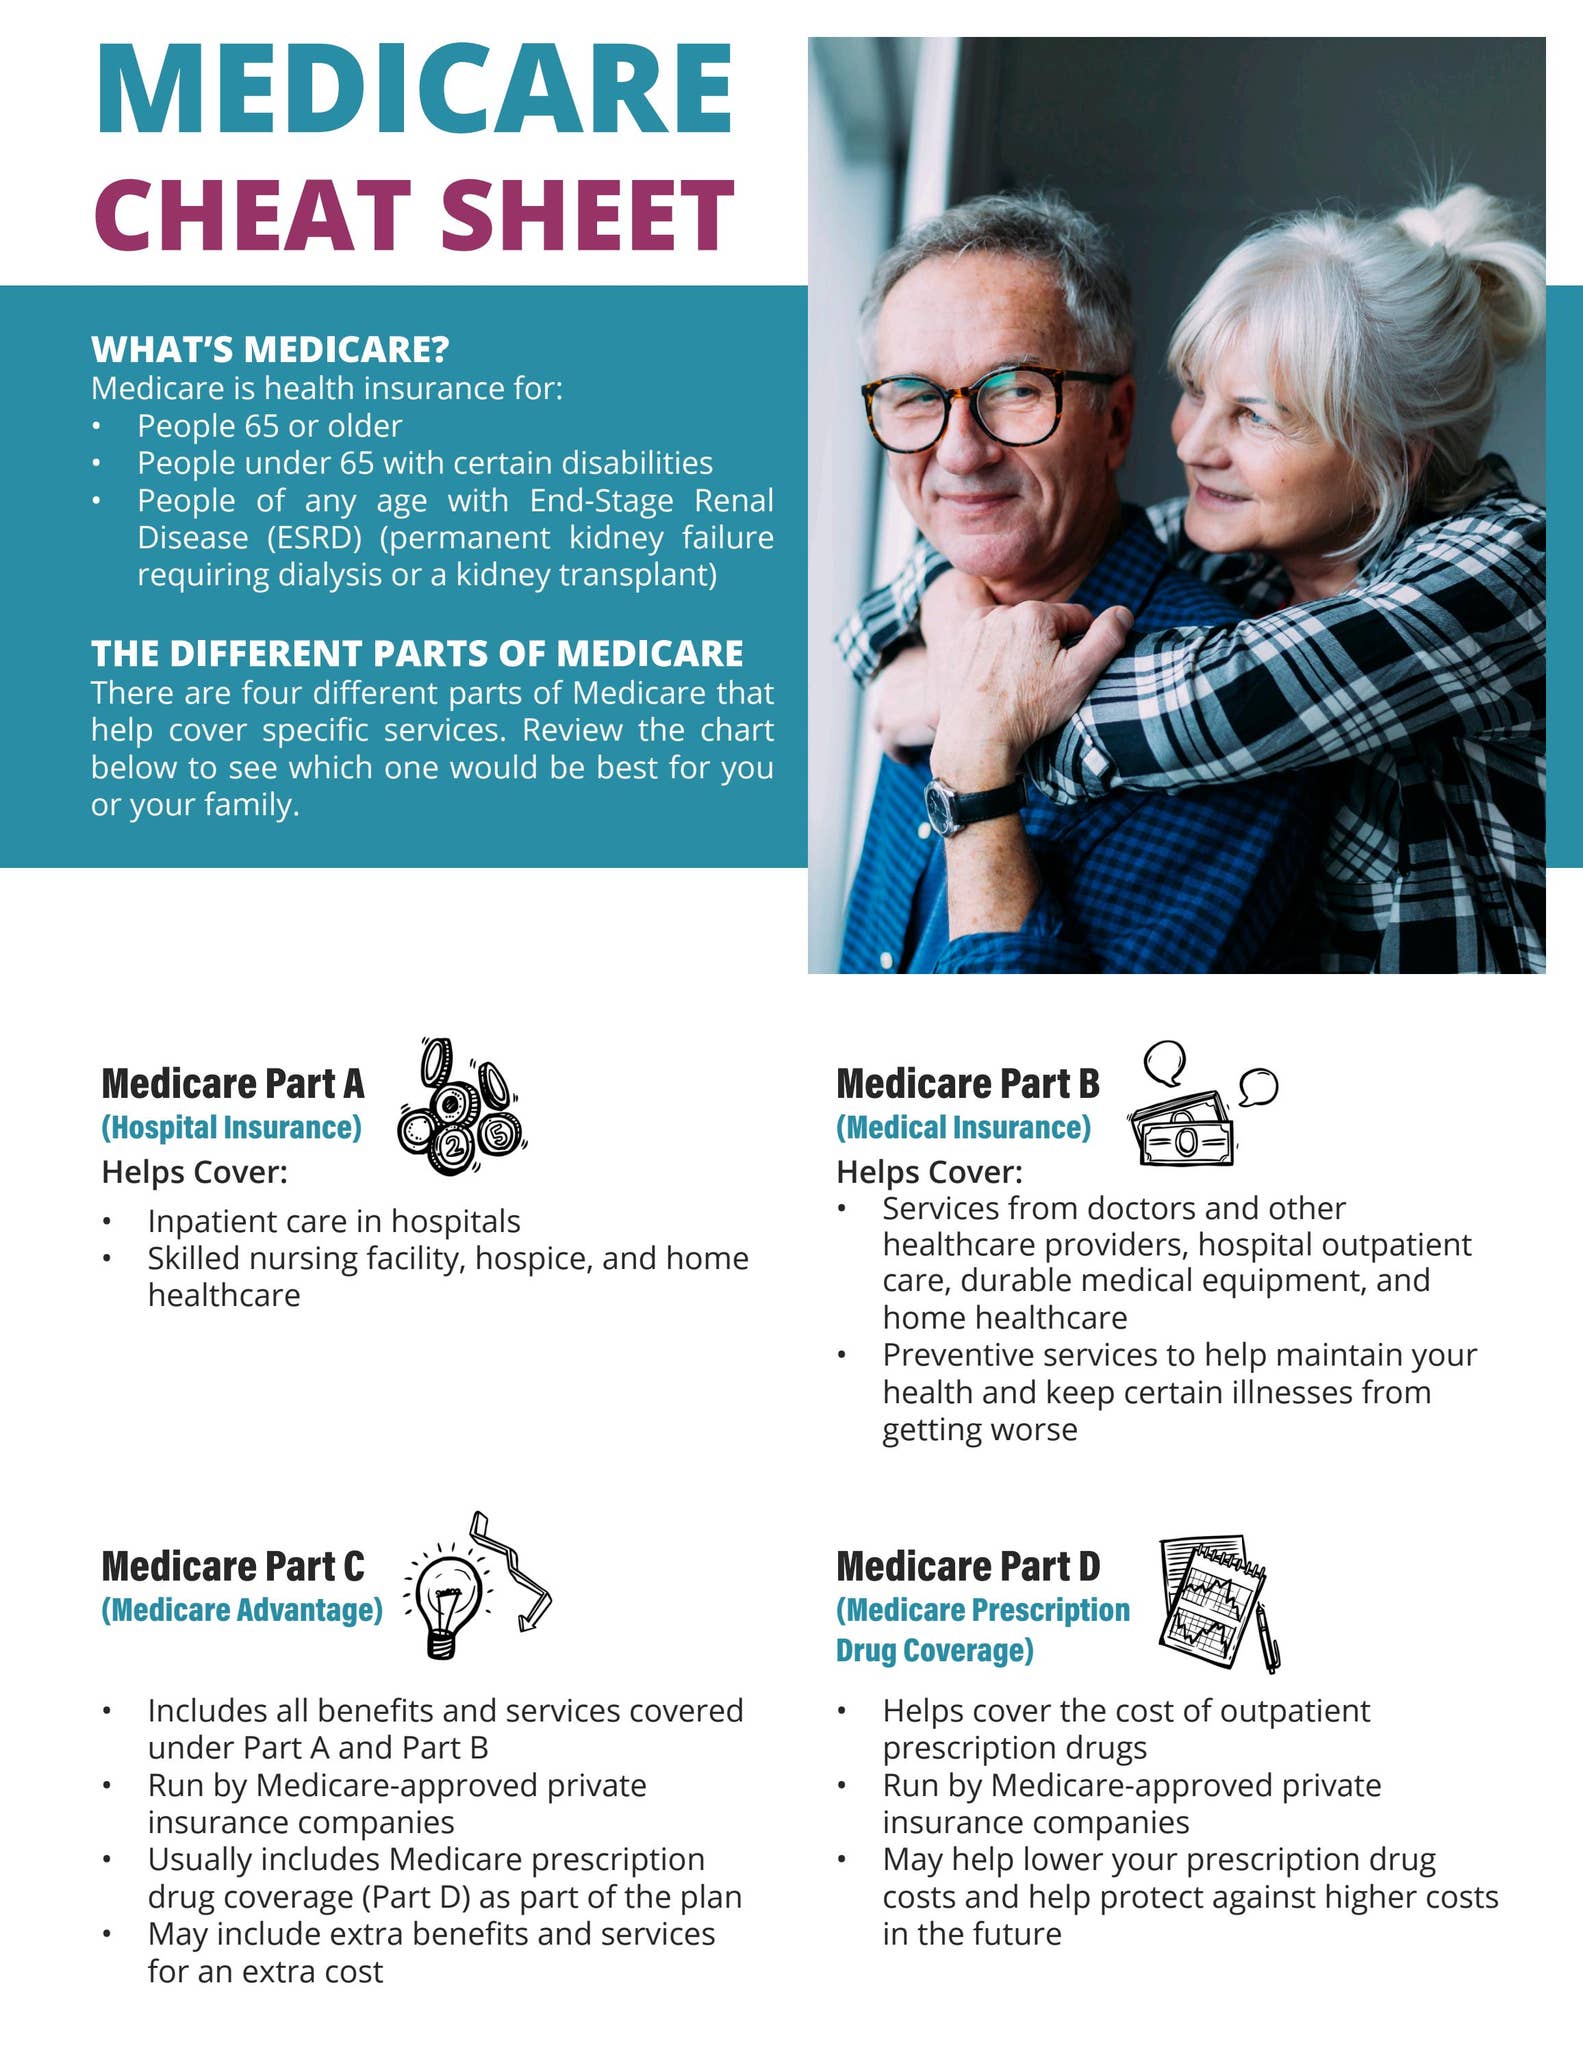
The Medicare For Dummies Cheat Sheet is a condensed reference document that distills the core Medicare concepts into a format you can actually use without reading an entire book. It covers the parts — A, B, C, and D — along with enrollment windows, penalty calculations, and supplemental options. You'll find these as free PDFs on publisher sites and third-party Medicare resource pages. I pulled one down during open enrollment last year. My situation involved a spouse who had just turned 65 and was confused about whether we should take Part B right away or let it ride. The cheat sheet had a clean timeline graphic showing the Initial Enrollment Period, the General Enrollment Period, and the penalties that kick in if you miss the window. That visual alone saved us from what would have been a six-month gap in coverage while we navigated phone trees and hold music.
Using the Medicare For Dummies Cheat Sheet Without Getting Misled
The cheat sheets are helpful as a starting point, but they are not designed to handle edge cases. They generalize. So here is how you actually use one without making mistakes. Start with Part A. If you or your spouse paid Medicare taxes for at least 10 years while working, you likely qualify for premium-free Part A. The cheat sheet will tell you this in bold. But what it will not tell you is that employer coverage can change that calculation entirely. If you are still working at 65 with a group health plan from your own or your spouse's employer, delaying Part B is often the right move — and sometimes delaying Part A too, depending on how the coordination of benefits works. The cheat sheet does not walk you through HRIS systems or COBRA interaction rules. You need to call your plan administrator and ask specifically whether your coverage meets the "creditable" standard for Part D, because that term means something very different in that context than it does for hospital insurance. Part B premiums are where most people get hit unexpectedly. The standard premium changes almost every year. In 2025 it was $174.70 per month, but high-income beneficiaries pay an Income-Related Monthly Adjustment Amount, which is calculated from your tax return from two years prior. The cheat sheet mentions IRMAA in passing. It does not explain that if you miss your IEP and fall into the GEP, you do not just pay the standard premium — you pay the standard premium plus a lifetime penalty that compounds by 10% for each full 12-month period you delayed. I watched a client lose about $38 a month permanently because the agent he talked to on a toll-free line gave him incorrect advice about deferring Part B. The cheat sheet would not have prevented that call, but it would have given him something concrete to verify against.
Medicare Advantage, or Part C, is the part that causes the most confusion. The cheat sheet describes it as an alternative way to receive your Part A and Part B benefits through a private insurer. That is technically correct. What it leaves out is that each Advantage plan has its own formulary, its own prior authorization rules, and its own narrow networks. Two plans in the same county can cover the same prescription drug at completely different tiers. The cheat sheet cannot reflect that because it changes plan by plan, zip code by zip code. The workaround I use is to take the cheat sheet's general framework and then cross-reference everything against the official Medicare Plan Finder tool at medicare.gov. You enter your drugs and your doctors, and it tells you which Advantage plans actually cover them. That tool is free and it updates in real time. The cheat sheet is a static document. For Part D, the cheat sheet correctly identifies the five-enrollment-period structure and the late-enrollment penalty. The counter-intuitive detail most beginners miss is that the Part D late penalty is permanent but calculated differently than Part B's. It is based on how many months you went without creditable prescription drug coverage after your IEP ended, multiplied by the national base beneficiary premium. In 2025 that base premium was $34.70. So if you went 18 months without coverage, your penalty is roughly 18 times a fraction of $34.70. It adds up slower than Part B's penalty, but it never goes away. I learned this the hard way when a beneficiary told me she had dropped Part D because her local pharmacy accepted her old plan's formulary. Six months later she was on a new drug that was not covered, and she had also triggered the late penalty. The cheat sheet did not warn her about the formulary gap risk, and neither did the counselor at the Medicare office she visited. One more thing the cheat sheet gets wrong or at least oversimplifies: the Special Enrollment Period. The document says if you have credible employer coverage, you can enroll in Part B later without penalty. That is true. But the SEPU clock starts when the employment ends or the coverage ends, whichever comes first, and you only have eight months from that date to sign up. I have seen multiple people lose their SEPU because they assumed they had a year. The eight-month window is strict. There is no grace period. If you wait until the ninth month, you fall into the GEP and pay the penalty for the rest of your life.
Get the Full Details

Where the Cheat Sheet Falls Short
The biggest limitation of any For Dummies-style reference is that it cannot account for state-specific variation. Medicaid supplemental programs, known as Extra Help for Part D and Medicare Savings Programs, have income thresholds that vary by state. California's thresholds are different from Texas's. The cheat sheet gives you a general income picture but not the exact numbers for your county. You need to check your state's Medicaid website or call the State Health Insurance Assistance Program at 1-800-431-6067 for localized guidance. Another gap is the interaction between Medicare and workers' compensation or liability insurance. If you were injured on the job and a settlement is pending, Medicare may not pay until the primary payer is exhausted. The cheat sheet does not address this because it is a niche scenario. But if you are in that situation, failing to set up a Medicare Set-Aside can result in Medicare denying your claims entirely until the issue is resolved, which can take months. The document also does not cover Trusteed Medicare for railroad workers, which operates under the Railroad Retirement Board instead of CMS. That is a separate system with different enrollment periods and different premium structures. One page in the cheat sheet might mention it in a footnote. You should not rely on that footnote if you worked in the railroad industry.
How I Actually Use These Resources
I keep one printed copy of the latest Medicare For Dummies Cheat Sheet on my desk, but I use it as a verification tool rather than a primary reference. When a beneficiary brings me a question, I read their situation against the cheat sheet's framework to make sure I am not missing a basic rule. Then I dig into the fine print using CMS publications, the Medicare & You handbook that arrives in mailboxes every September, and the Plan Finder tool. The handbook is freely available online and it is more detailed than any cheat sheet. It also includes the actual appeal rights and timelines, which the cheat sheet barely touches. If you want a download, the Wiley website hosts the cheat sheet for free at wiley.com. You do not need to buy the book. The PDF is typically two to three pages. Third-party sites like medicarehelp.org and the SHIP network also host mirrored copies. Be careful with random Google results, though. Some sites embed ads that redirect you to sell supplements or scam services. The official sources are the publisher's site and government domains ending in .gov. The cheat sheet is useful for orientation. It is not useful for decision-making on complex cases. That requires going to the primary sources and understanding how the rules interact with your specific situation. The penalties are real. The enrollment windows are strict. And the plan landscape changes every year, so anything you read in a static document is already slightly behind the current reality by the time you find it.