How to actually prepare for the Medicare licensing exam without losing your mind
The exam is mostly a memorization slog. You need to know plan types, enrollment windows, commission rules, and the exact sequence of steps when you're presenting to a beneficiary. Most people blow through the material in two weeks and then fail the state-specific portion because they treated it like a textbook instead of a procedural manual. A decent study guide isn't a collection of definitions. It needs to simulate the way you'll actually use this information when a client sits across from you. The best ones I've seen organize around scenarios: here's a 68-year-old on Social Security with a fixed income and three prescription drugs. What plan do you recommend and why? Then they walk through the exact regulatory constraints that eliminate half the options. I spent years using fragmented PDFs from carrier training portals, state module handouts, and random Quizlet decks. It worked, barely. But the breakthrough came when I started treating the study guide like a reference manual I'd flip through during open enrollment, not a one-time reading assignment. That mindset shift changed everything about how I retained the material.
Building a study guide that actually sticks
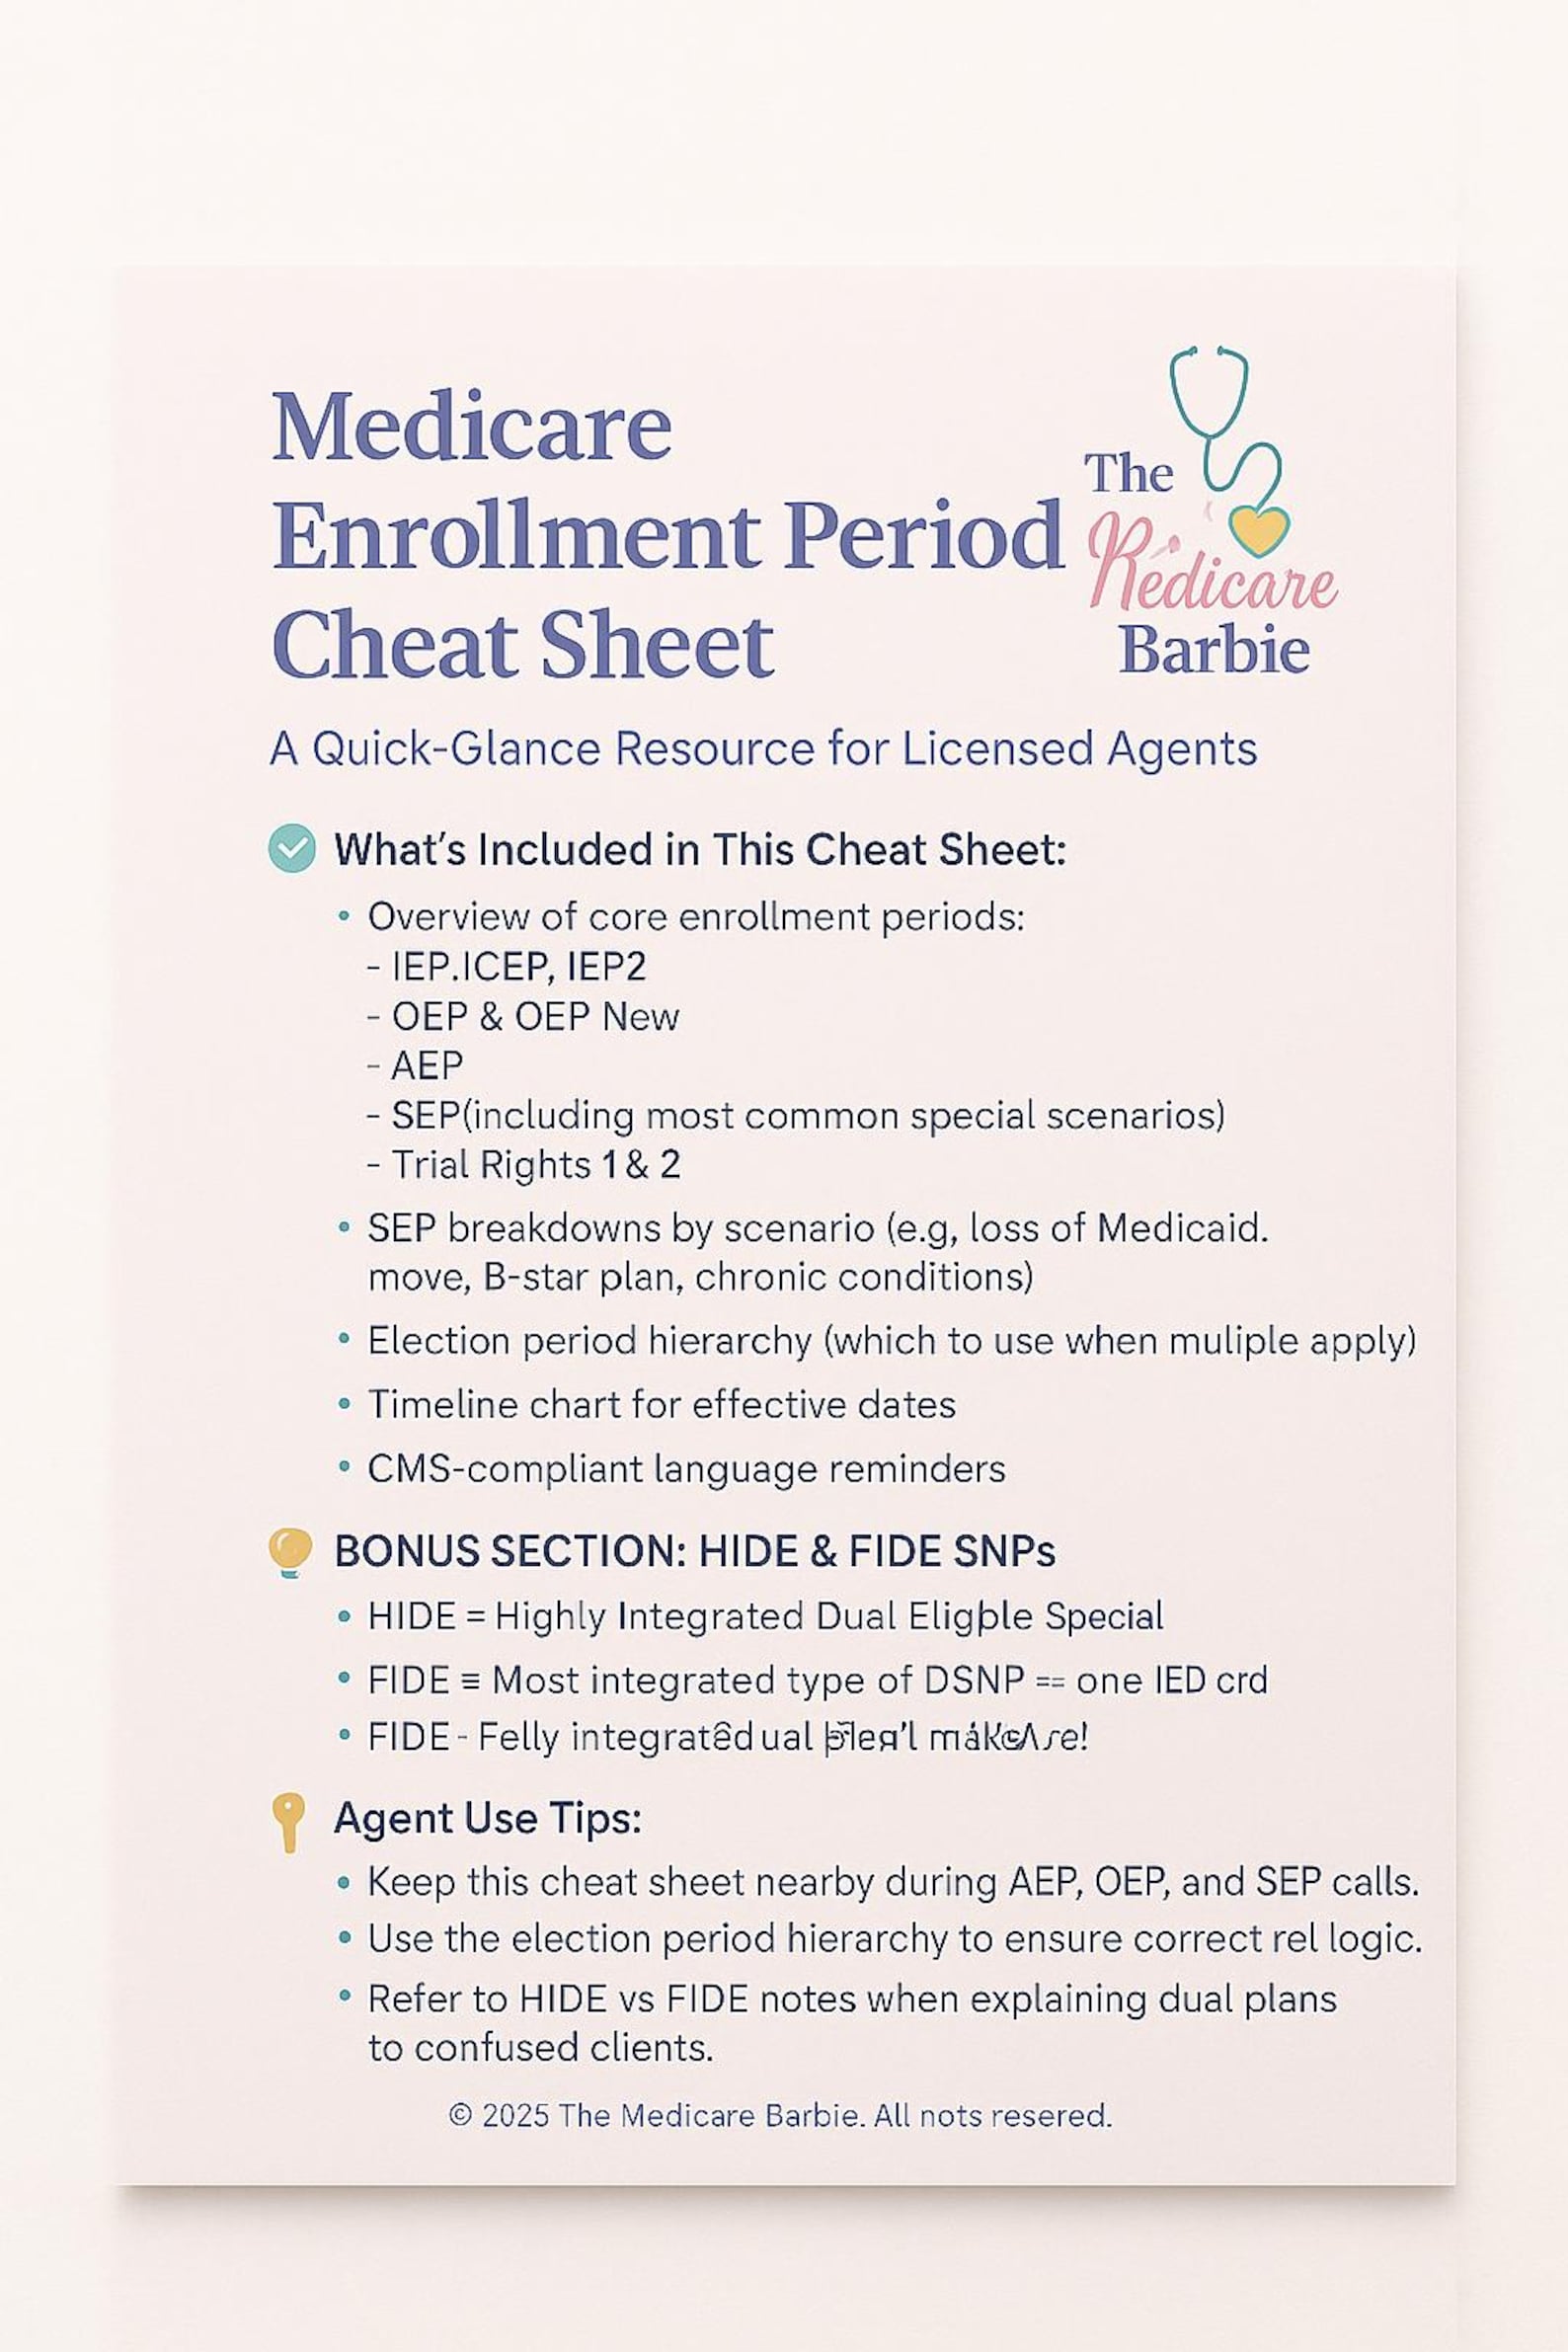
Start with the federal basics. Medicare Advantage, Part A, Part B, Part C, Part D, Medical Savings Accounts, Extra Help, QMB, SLMB, QI — you need to know these acronyms cold and understand exactly what each program pays for and where the boundaries are. The federal framework is relatively stable year to year, so a solid foundation here pays dividends no matter which state you're licensed in. Part A is premium-free for most people who have the work history, but the hospital deductible changes annually. In 2024 it was $1,676 per benefit period. In 2025 it rose to $1,776. Your study guide should flag these numbers and tell you where to find the current year's figures rather than baking them in permanently. That's the single most common mistake in outdated materials. Then move to the enrollment calendars. Initial Enrollment Period, General Enrollment Period, Annual Enrollment, Open Enrollment for MA plans, Special Enrollment Periods. These are the gates that control everything. Miss the timing and the client loses options. The rules are straightforward but there are enough edge cases that you'll confuse yourself if you don't map them out visually.
I always drew timeline diagrams for each enrollment period. Not digital timelines — hand-drawn. The physical act of sketching the dates and overlap windows forced me to actually notice that the IEP doesn't end until three months after the month you turn 65, and that signing up for Part B during your IEP avoids the lifetime penalty. Writing it down made it real.
Get the Full Details
The state-specific layer
This is where most people fall apart. Federal Medicare rules are the floor. Every state adds its own variations — Medicaid tie-ins, supplement rating areas, pre-enrollment requirements, appointment recording mandates, continuing education hours, appointment-to-sale waiting periods. Your study guide needs a dedicated section for your state's rules and it needs to cite the source. If it says something about your state's regulations and doesn't tell you where that information came from, it's probably wrong or outdated. I got burned on this early in my career. I was studying for the California exam and used a guide that claimed you could do unsolicited door-to-door solicitation in certain circumstances. It didn't cite any regulation. I passed the test on that content, then tried to apply it on the job and almost violated a compliance rule. The workaround I use now is simple: every state-specific claim in a study guide gets cross-referenced against the state insurance department's own published materials before I trust it. Takes five extra minutes per claim but it saves you from making expensive mistakes.
Part D and the drug formulary mess
Part D is the area where beginners consistently underprepare. The base benefit structure, the coverage gap, the catastrophic threshold, formulary tiers, PDP versus MA-PD differences — it's a lot and it changes every year. A proper study guide should explain the standard benefit design first, then show you how to read a formulary, then walk through the coverage gap calculation with actual numbers. Here's something most guides don't emphasize enough: the Part D late enrollment penalty is calculated based on the national base beneficiary premium, not the plan's actual premium. So even if a client picks the cheapest plan available, their penalty is still tied to that baseline number. I've had clients argue with me about this for twenty minutes before I pulled out a calculator and walked through the math. Having that worked-out example in your study guide would save everyone time.
Commission and compliance rules you can't afford to skip
Medicare study materials frequently skim over the compliance piece because it's not testable in some states. That's a mistake. The appointment scheduling rules, the recording requirements, the no-gifts policy, the 48-hour cooling-off period in certain states, the documentation standards — these are the things that get agents audited and sanctioned. A good guide treats compliance with the same weight as product knowledge. I keep a compliance cheat sheet separate from my product study guide. It's one page for my state and it covers: do I need to record the appointment, do I need to give a comparison sheet, when can I follow up after a presentation, what disclosures are mandatory at the point of sale. When I walk into a client meeting, that sheet is on my desk. Studying it separately from the clinical product content keeps the two categories from blurring together in your head.
Where to actually find good study material
Carrier training portals are free and usually accurate for their own products but they're designed to sell you, not to give you balanced education. The CMS site has official publications — the Medicare & You handbook, the Medicare Benefit Policy Manual, the Medicare Managed Care Manual. These are dry, thick, and completely reliable. I printed the key sections and highlighted them. It took three weekends but it was more efficient than any paid course I've ever bought. Third-party study guides vary wildly in quality. Some are excellent and rigorously updated. Others are repackaged CMS PDFs with a few quizzes tacked on. The test is simple: pick one claim about a specific enrollment rule and verify it against the official CMS source. If the guide can't be verified, it's not worth your time.
Medicare Study Guide For Agents: what to look for and what to avoid
Look for guides that include current-year numbers with source citations, state-specific sections that name the regulating authority, scenario-based questions rather than pure definition dumps, and compliance checklists. Avoid guides that are more than a year old without a clear update log, that only cover one plan type, that don't address the coverage gap calculations, or that present opinion as regulation. No study guide will prepare you for the variability of real client conversations. You can memorize every enrollment period and still freeze when a client asks about their specific drug formulary on the spot. The workarounds are practical: keep a formulary lookup tool bookmarked, practice explaining plan differences out loud until it stops sounding like you're reading, and accept that you'll need to look things up during actual appointments. That's normal. It's better than guessing. Also, study guides can't replace a mentor for the nuance parts. How you present a plan to someone who's nervous about losing their current doctor is different from how you present it to someone shopping purely on price. That's learned through experience, not reading. The guide gets you licensed. The rest comes from doing the work.