Getting Your Foot in the Door With Medicare Insurance
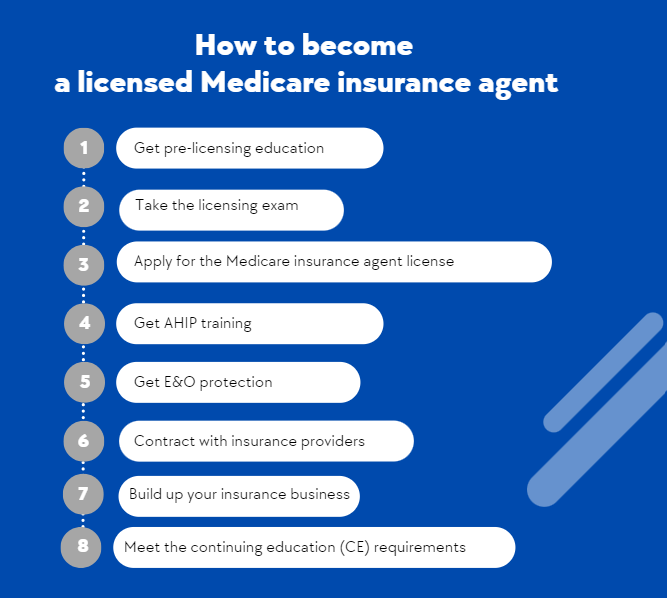
I spent six years doing nothing but Medicare sales. By the time I was done, I'd seen every training format available and a few that shouldn't be. The landscape has shifted since the CMS rules tightened around 2020, and most people entering the field are either jumping through hoops blindly or wasting money on programs that don't actually qualify them for anything. The first thing you need to understand is that there is no single federal certification called "Medicare Agent License." Each state issues its own license, and Medicare training requirements vary by state. Some states require a dedicated health insurance course before you can even sit for the exam. Others let you take a general property casualty license and pivot to Medicare later. Florida requires 8 hours of continuing education specifically on Medicare. Texas requires a 4-hour pre-licensing course focused on insurance principles, then you add the Medicare endorsement. Pennsylvania doesn't have a separate Medicare endorsement at all—you just sell Medicare after getting your standard health license. The training that actually matters comes after your state license. That's where Medicare Training For Insurance Agents becomes relevant, because these programs teach you the product knowledge you need to actually navigate the parts, plans, and penalties without losing your mind.
What Medicare Training For Insurance Agents Actually Covers
A proper program breaks down Part A, B, C, and D clearly enough that you can explain the difference between a Medicare Advantage plan and a Supplement plan to a confused 68-year-old in terms that don't make them more confused. It covers the Annual Enrollment Period, the Initial Enrollment Period, Special Enrollment Periods, and the October-to-December chaos that defines Medicare sales season. It walks through income-adjusted premium adjustments, the late enrollment penalties that can permanently increase someone's cost, and the trust fund solvency questions that keep showing up in every policyholder meeting. Most affordable programs run between 20 and 40 hours of content. You can find free modules through the CMS website and through state insurance departments, but they're fragmented and rarely organized for someone who needs to pass a state exam or build a book of business. Paid courses from carriers like UnitedHealthcare, Humana, and Kaiser offer training to their appointed agents, but those usually require you to already have an active contract with them. Independent training platforms charge anywhere from $150 to $600 for a complete curriculum that includes practice exams and update materials.
The Practical Problem Most People Don't See Coming
Here's the thing nobody tells you during enrollment. A client can qualify for a Special Enrollment Period based on losing employer coverage, but the timeline is narrower than you think. I had a prospect in Arizona whose employer plan ended mid-month because of a company restructuring. He called me three weeks later because his former agent wasn't responding to his messages. We spent two hours on the phone sorting out what SEPs applied to his situation. The employer coverage had ended on the 15th, not the 1st, which meant his SEP window started the following month, not immediately. He had to choose between a gap in Part B coverage or enrolling late and eating a permanent 10 percent penalty per year without coverage. That's the kind of edge case that doesn't show up in any training module until you've lived through it twice or three times. The workaround is simple if you know it in advance: always verify the exact termination date on the employer's side, not just the month. Call the benefits administrator directly. Get the date in writing. Then cross-reference it with the CMS enrollment period charts before you do anything else. Most agents skip this step and assume a general "I lost my job" qualifies for an immediate SEP window. It usually does, but the specifics of when that window opens and closes depend on the exact date and whether they had credible prescription drug coverage.
Get the Full Details
Counter-Intuitive Things Beginners Miss
The biggest misconception is that Medicare Advantage plans are universally better than Supplement plans. They're not. A healthy 65-year-old with no chronic conditions and a manageable income might save thousands by sticking with Original Medicare plus a Part D plan and a Medigap policy. MA plans have networks and prior authorization requirements that can become serious problems if someone gets sick and moves or travels frequently. The trade-off is lower monthly premiums and extra benefits like dental and vision, which sound attractive until a $400 specialist visit requires three phone calls and two weeks of authorization. Another thing nobody emphasizes enough is that Part B premiums aren't fixed. They're income-based. Someone who made $300,000 a year in 2022 might see their Part B premium jump significantly in 2024 based on that prior tax return. Training programs rarely spend time on the IRMAA brackets because they're boring, but they're where clients get surprised every year. If you don't proactively explain this, you'll have angry calls in January when their premium statement arrives.
Where to Find Legitimate Training Resources
The Centers for Medicare and Medicaid Services maintains a free resource center at cms.gov with pamphlets, enrollment calendars, and plan finder tools. State insurance departments often have their own free training modules aligned to state-specific licensing requirements. The National Association of Insurance Commissioners publishes model regulations that many states adopt. For paid comprehensive programs,look into the American Health Insurance Plans association materials, the Medicheck Training Institute, or carrier-specific onboarding programs if you have contracts in place. Be cautious of programs that promise "certification" without clarifying that no such federal certification exists. You will never get a government-issued Medicare certificate. What you get is state licensure plus any continuing education credits required by your state or by the carriers you work with. Any program selling a certificate that implies federal authorization is misleading you. There are also state-mandated continuing education hours—usually 24 credits every two years for health insurance agents in most states, with some of those hours required to be Medicare-specific. Missing those deadlines means your license lapses and you can't sell anything until you catch up. The training itself is straightforward once you understand the structure. It's the—the dates, the penalties, the income thresholds, the enrollment windows—that eats up your time and determines whether your clients stay or switch away from you. Focus on the details.