What Actually Happens at Each Visit
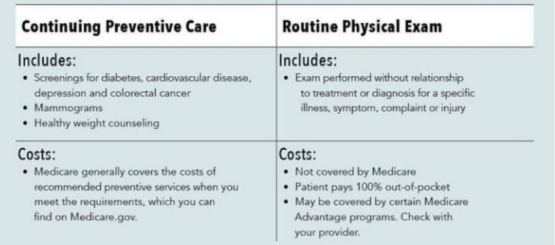
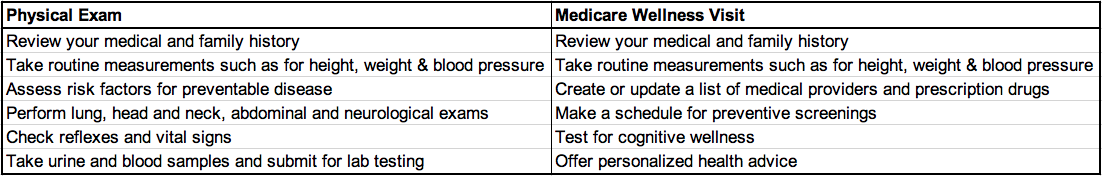
A Medicare Wellness Visit is primarily a planning session. The doctor or nurse practitioner goes through a health risk assessment, reviews your medical and family history, checks for cognitive concerns, screens for depression and certain other conditions, and then creates a personalized prevention plan. It is not a hands-on exam in most cases. You will likely sit in a standard exam room, fill out some paperwork, and talk. Sometimes a nurse measures your vitals. But the visiting provider is generally not listening to your heart, checking your lungs, or doing a comprehensive physical assessment. A physical exam is different. You are getting evaluated. Blood pressure, heart rhythm, lung sounds, abdominal palpation, thyroid check, neurological screening, foot exams for diabetics, prostate checks for men over a certain age. This is the kind of visit where you lie back and the provider actually looks at your body. It costs more. It takes longer. Billing codes are entirely separate from the wellness visit codes.
Medicare Wellness Visit Vs Physical Exam: Knowing the Difference Matters
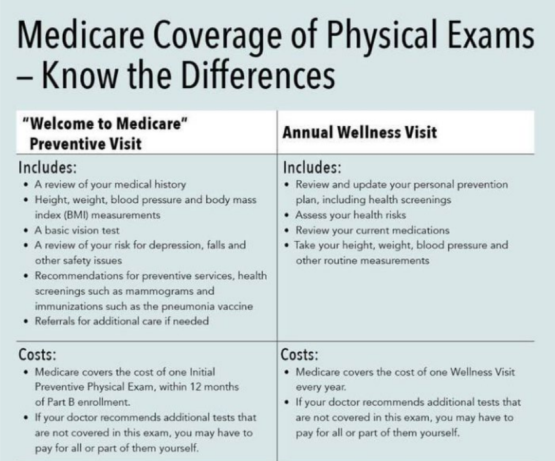
I have watched people show up expecting their annual checkup during a wellness visit and then get turned away or rushed out because the provider was only authorized to do what Medicare covers under that benefit. One patient told me she brought her list of current medications and expected them to be reconciled on paper. They were. But she also mentioned her knee had been bothering her, and the provider said that was not covered under the visit and would need to be billed separately or addressed at a different appointment. She was frustrated. I understood her frustration, but the billing structure is what it is. The Annual Wellness Visit is covered once every 12 months with no copay under Part B. That is the main draw. The Problem-Oriented or Comprehensive Physical Exam has a 20% coinsurance after the Part B deductible is met. If your deductible is not yet met for the year, you pay full price until you hit the threshold. This is important because some people go in during January and assume everything is free. It is not. The wellness visit is free. The physical exam is not. Here is something most people do not realize: you can have both visits in the same calendar year. In fact, you should. The wellness visit and the physical exam serve completely different purposes. Doing them in separate months gives your provider a chance to catch things that only show up during an actual hands-on evaluation. I recommend scheduling the wellness visit early in the year and the physical exam later, ideally when you have specific concerns to discuss. If you schedule them back-to-back, some practices will combine them into a single longer appointment and bill accordingly. That can work, but it depends on your provider and how they handle the coding.
One edge case I ran into repeatedly involves supplemental insurance. Some Medigap plans cover the 20% coinsurance for the physical exam, but not all of them do. A lot of people assume their supplemental plan fills every gap. It does not. Plan G covers the deductible and coinsurance for most Part B services, which would include the physical exam. Plan N requires a small copay for office visits, which carries over to the physical exam. If you have a Medicare Advantage plan, the cost-sharing structure is entirely different and depends on your specific plan details. Before you schedule anything, call your insurance and ask what your out-of-pocket cost will be for CPT code 99387 or 99397 (the comprehensive exam codes) versus the G0438 or G0439 codes used for the wellness visit. Do not assume. The numbers on your card do not tell you which codes apply. Another practical detail: the wellness visit requires you to have had a initial preventive physical examination or the first wellness visit sometime after you enrolled in Part B. There is a one-time benefit called the "Welcome to Medicare" visit that you can only use within the first 12 months of enrolling in Part B. After that, it becomes the Annual Wellness Visit. These are separate benefits. I have seen people who enrolled in Part B at 65 and never scheduled the Welcome to Medicare visit, then assumed they had already used it when they showed up for their first wellness visit three years later. It does not roll over. It is gone. If you are in that situation, call your Medicare and confirm what you have and have not used before you show up at the clinic. There is also a common misconception about what the wellness visit includes. It does not include lab work beyond basic screening questions. Fasting glucose, lipid panels, A1C, PSA testing, mammograms, colon cancer screening, flu shots, pneumonia vaccines — none of that is part of the wellness visit itself. Some of those screenings are covered under Medicare at no cost if they meet certain criteria, but they are not performed during the wellness visit. You will likely be given a schedule for recommended screenings based on your age and risk factors, but you need to make separate appointments or request separate orders for most of them. I have worked with patients who left the wellness visit thinking everything was handled and then got surprise bills for blood draws that were ordered but not completed during the appointment. Request that all screening orders be placed and any necessary lab work be scheduled before you leave the office.
Get the Full Details
The physical exam side has its own complications. Some providers refuse to bill Medicare for a comprehensive preventive physical exam because the reimbursement is low and the time investment is high. This is not unusual. A lot of primary care practices have stopped offering the old "mini-checkup" that used to come with annual visits. If your provider does not offer a covered preventive physical exam, you may need to seek one elsewhere or negotiate what is actually available within your existing practice. It is worth asking directly: does your provider bill for preventive physical exams under Medicare, and if so, what is the out-of-pocket cost with my specific plan? If you want something concrete to take with you, here is a simple approach that works in practice. Call your provider's office and ask which visit they recommend for your current needs. If you have no new symptoms and your chronic conditions are stable, the wellness visit is the right choice and costs you nothing. If you have a new complaint, an unexplained symptom, or it has been more than a year since your last hands-on exam, request the physical exam. Bring a written list of all medications, supplements, and any changes in your health since your last visit. Ask for copies of any lab orders before you leave. Confirm with your insurance exactly what you will owe before the appointment. This takes about five minutes on the phone and saves you from showing up confused and potentially facing unexpected bills. The reality is that Medicare coverage for these visits is functional but fragmented. The system rewards people who know how to navigate it and penalizes those who assume everything is included. The wellness visit is a valuable tool if you use it correctly as a planning session. The physical exam is necessary if you want actual clinical evaluation. They are not interchangeable. Most people benefit from both, scheduled at different times of the year, with prior confirmation of what their insurance will actually cover.