Working Through the Pension System Without Losing Your Mind
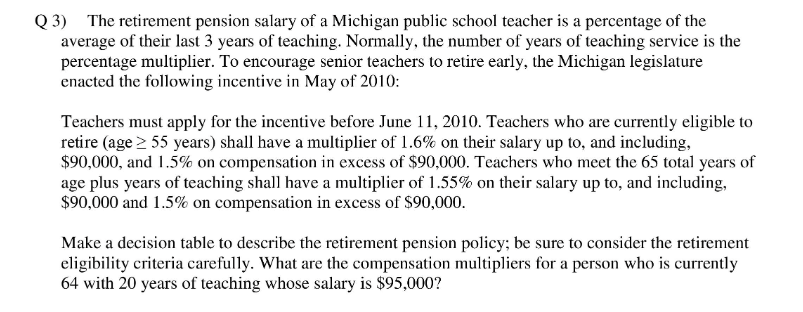
The Michigan public school retirement system is basically a defined benefit pension plus a 401(a) defined contribution component, administered through the Michigan State Employees' Retirement System (MSERS) for most public school districts. It is not a single unified teachers' plan the way some states operate. That structural quirk matters because your actual benefits depend entirely on which employer you worked for and when you joined. If you're spending time googling Michigan Teacher Retirement Questions, you probably already noticed the website navigation is not intuitive. I have spent more afternoons than I'd like to admit navigating a portal that treats mid-career switchers like they are starting from scratch. Most people hitting this system for the first time are trying to figure out two things: how much they will get paid after they stop working, and what happens if they leave mid-career for a job in another state or sector. The immediate answer to both questions is fragmented because Michigan's system splits retirement administration across three different funds depending on your employer type. MSERS covers employees of public schools, community colleges, and many state agencies. The Michigan Municipal Employees' Retirement System handles city and township employees, while the Michigan Public School Employees' Retirement System used to be a standalone entity but was merged into MSERS back in 2013 under Public Act 316. You will still see references to the old system on older documents and forum threads, which adds a layer of confusion that does not serve anyone well. Your benefit calculation for the defined pension portion uses a formula that multiplies your final average salary by a years-of-service multiplier, then applies an age adjustment factor if you retire before reaching the plan's normal retirement age. For MSERS members who entered before October 1, 2012, the multiplier is 1.5 percent per year of creditable service. For those who entered on or after that date, the multiplier drops to 1.25 percent. This is one of those details that sounds minor but will cost you tens of thousands of dollars over a typical career if you are not aware of which bracket you fall into. I learned this the hard way for a colleague who assumed both she and her husband were in the same tier when they were actually separated by a single enrollment date at the district level.
The defined contribution piece attached to the pension is a separate calculation. Most Michigan public school employers contribute a set percentage of your salary into a 401(a) retirement account, and you generally do not make voluntary contributions to that specific account yourself. The money grows tax-deferred and you can roll it into an IRA or your new employer's plan when you leave. This is the part of the system that functions relatively smoothly. The pension calculation side is where things tend to get sticky. A specific edge case that keeps coming up involves employees who work in multiple Michigan school districts over their career. Say you spend six years in District A, then five years in District B, then come back to District A. Each district reports your service and earnings to MSERS independently, and MSERS combines them automatically for the pension calculation, but the final average salary calculation requires all of your service periods to align properly. In my experience, the most common error here is a gap year where you took a leave without pay or worked a season as a substitute without proper crediting. MSERS will not count that year toward your final average salary, and it will not count it toward your years of service unless it was reported correctly by the employing district. I had to push a dispute for a former student who had three semesters of substitute teaching that the system had completely dropped from her record. The workaround was filing a formal service credit correction request with MSERS, attaching payroll verification from each short-term employer, and waiting approximately forty-five business days for the manual review. Most people just accept the lower benefit number because the alternative feels like too much effort. Another thing people rarely plan for is the impact of Social Security offsets. If your Michigan teaching position is covered by Social Security, which some non-tenure-track roles and certain charter school arrangements are, your MSERS pension benefit may be reduced by the amount of your Social Security benefit. This is not automatic and it depends on whether your employer participated in Social Security during the years you were credited. I have seen this bite educators who transitioned from public district teaching into private school or higher education administration without realizing that their combined benefit picture changed dramatically.
Retirement application timing is another area where small mistakes create big delays. MSERS recommends filing your application at least ninety days before your intended retirement date. If you file late, your first payment gets pushed out, and you can lose a full month of benefits simply because you misread the calendar. The online portal allows you to submit an intent-to-retire notice first, which locks in your processing queue while you gather the remaining documentation. Use that feature. It is easy to overlook but worth the fifteen minutes it takes. There are legitimate downsides to how this system is structured. The portal interface has not kept pace with what people expect from government services, and getting a human representative on the phone usually requires holding for an extended period during business hours. Benefit estimates provided by the system are approximations based on your current salary trajectory and will not reflect future merit increases, district salary schedule changes, or adjustments to the multiplier. If you try to plan your retirement using only the online estimate tool, you are likely to be off by a meaningful margin. The only reliable way to get a personalized projection is to request a formal benefit statement from MSERS, which they mail out annually to active members, or to contact them directly for a one-time projection. Those statements use your actual credited earnings history, not your current pay stub. For people considering early retirement under the Rule of 80 or age sixty-two provisions, there is an additional nuance worth noting. The early reduction factor applies to the pension portion only, not to the defined contribution account. Some retirees assume both parts get penalized and then passively accept a lower number without verifying whether the reduction was applied correctly. I have reviewed several cases where the actuarial reduction was overstated in the initial notice, usually due to a data entry glitch around the claimed retirement date. Requesting a recalculation is straightforward and typically resolves within thirty days.
Get the Full Details
If you need to access your account, the MSERS member portal is the primary entry point. From there you can view your service history, request benefit estimates, and submit retirement applications. There is no dedicated standalone platform for Michigan Teacher Retirement Questions specifically. Everything funnels through the same system regardless of whether you are a classroom teacher, an administrator, or a support staff member who qualifies under the same retirement framework. The documentation is consistent but dense, and the search function within the site is not particularly helpful. Bookmarking the specific sections you need tends to save more time than repeatedly searching the portal. The broader takeaway is that this system works adequately if you track your own records independently rather than relying on the system to flag discrepancies. Keep copies of every employment verification form, every salary schedule, and every contribution statement. When you eventually sit down to plan your exit, having that paper trail means you can resolve issues quickly instead of spending months chasing corrections. Most of the friction around Michigan Teacher Retirement Questions comes down to people discovering problems at retirement time rather than catching them throughout their career.