Understanding Market Structures in Microeconomics
Micro Economics Unit 3: Market Structures and Firm Behavior
Unit 3 is where things actually get useful. You move past supply and demand curves and start looking at how real markets behave when you factor in the number of sellers, the nature of the product, and what stops new companies from walking in off the street. I used to hand out pages of formulas at the start of this unit, but students just memorized them and forgot everything by the midterms. The trick is to think about it as a spectrum. The four market structures — perfect competition, monopolistic competition, oligopoly, and pure monopoly — exist on a line based on two things: how many firms are competing and how differentiated their products are. Perfect competition sits at one end with hundreds of identical sellers. Monopoly sits at the other with a single seller and no close substitutes. Everything else falls somewhere in between. This framework matters because it determines pricing power, efficiency, and what happens to consumers over time.
Perfect Competition and the Efficiency Illusion
Perfect competition is the baseline model. Price takers. Homogeneous products. Free entry and exit. Zero barriers. In this structure, firms maximize profit where marginal revenue equals marginal cost, and in the long run, they make zero economic profit because any positive profit attracts new entrants until the price gets bid down to the minimum of average total cost. That outcome is allocatively efficient — price equals marginal cost — and productively efficient too since firms produce at the lowest point on their ATC curve. The problem is that perfect competition basically doesn't exist in the real world. I had a student once try to apply it to local agriculture, arguing that wheat farmers were perfect competitors. They weren't even close. Government subsidies, transportation costs, crop insurance, and land ownership patterns all distort the model. Even if two farmers grow identical corn, one has better soil, newer equipment, and lower delivery costs. The model is a benchmark, not a description. Treat it as a tool for asking whether a real market is closer to efficiency or not, rather than trying to fit reality into it. The long-run adjustment process is what students consistently mess up on exams. They confuse zero economic profit with zero accounting profit. Zero economic profit means the firm is earning exactly its opportunity cost — the owner is making as much as they would in their next best alternative. Accounting profit can be positive and large. This distinction shows up on every test I've ever given, and roughly two-thirds of students still get it wrong. Write it down somewhere permanent.
Monopolistic Competition: The Real World Default
Monopolistic competition is probably the most common structure in practice. Many firms. Differentiated products. Low barriers to entry. Restaurants, clothing brands, hair salons, coffee shops — these all fit. Each firm faces a downward-sloping demand curve because their product isn't identical to the competitor's. That gives them some pricing power, but not much, because substitution is easy. In the short run, firms can earn positive economic profits or suffer losses. In the long run, entry and exit drive profits to zero, but here's the key difference from perfect competition: the zero-profit point doesn't occur at minimum average total cost. The firm produces on the downward-sloping portion of its ATC curve. This is called excess capacity. The firm could produce more and lower its per-unit cost, but it doesn't, because raising output would require lowering price on all units, and marginal revenue falls faster than price. I've seen students write that monopolistic competition is inefficient so it must be bad. That's an oversimplification. The inefficiency comes from two sources. Deadweight loss exists because price exceeds marginal cost. And excess capacity means society isn't producing at the lowest possible cost per unit. But you're paying for product variety. If every restaurant sold the same food at the same price, you'd save money but lose everything that makes dining out useful. The tradeoff between variety and efficiency is the central tension here, and it's the kind of thing that separates a decent answer from a great one on an AP exam.
Get the Full Details

Oligopoly and the Problem of Predictability
Oligopoly changes everything because strategic interdependence enters the picture. When there are only a few firms, each one's decisions directly affect the others. You can't just plug numbers into a formula and get an answer. You have to think about what your competitor will do, and what they think you'll do, and what they think you think they'll do. Game theory becomes relevant here, and that's usually where students hit a wall. The Cournot model assumes firms compete on quantity simultaneously. The Bertrand model assumes they compete on price simultaneously. The Stackelberg model introduces a leader-follower dynamic where one firm moves first. Each produces different predictions about price, output, and profit. Real markets rarely match any single model perfectly. Airlines come close to Bertrand behavior on route pairs, while the automobile industry looks more like Cournot with capacity commitments. Cartels and collusion are the oligopoly version of the perfect competition ideal — maximize joint profits by acting like a monopoly. But they're unstable. Every member has an incentive to cheat and produce more than the agreement allows. The prisoner's dilemma illustrates this clearly. Two firms face a choice: cooperate or cheat. Both cooperating yields the best joint outcome. But individually, cheating always dominates. The Nash equilibrium is both cheating, and both end up worse off. I've had students argue that OPEC proves cartels work. They do, but only because OPEC isn't a one-shot game. It's repeated indefinitely, and reputation matters. The model changes when firms interact repeatedly rather than once.
Monopoly: Barriers and the Welfare Cost
A monopoly exists when a single firm controls the entire market and faces no close substitutes. The barriers to entry are what matter — legal barriers like patents and licenses, control of essential resources, economies of scale that make competition irrational, or network effects that reward concentration. The firm maximizes profit where MR equals MC, but unlike perfect competition, MR is below price because the demand curve is downward sloping. The firm sets price by reading off the demand curve at the profit-maximizing quantity. The deadweight loss from monopoly is straightforward to calculate if you know your curves. It's the triangle between the demand curve, the marginal cost curve, and the quantity produced under monopoly versus the competitive quantity. This is a standard exam question and worth more points than students usually spend preparing for it. Draw the graph. Label every curve. Show the welfare loss clearly. That alone puts you in the top tier of answers. Price discrimination is where monopolies get interesting. First-degree discrimination charges each consumer their maximum willingness to pay — perfect extraction of consumer surplus. Second-degree discrimination offers different prices based on quantity or version, like bulk pricing or software tiers. Third-degree discrimination segments markets by observable characteristics like age or location. Airlines practice all three. Business class vs. economy is second-degree. Student discounts are third-degree. Dynamic pricing based on booking date is another form of third-degree.
I ran into a practical problem with a homework set last year where students had to calculate the welfare effects of third-degree price discrimination between two markets with different elasticities. The textbook assumed constant marginal cost, which is convenient. Real firms rarely have flat MC curves. When MC is rising, the optimal output split between markets changes because producing an additional unit in the high-elasticity market costs less in terms of forgone profit than producing it in the low-elasticity market. The rule still holds — MR must equal MC in each market and equal the common MC — but the arithmetic gets messier and the intuition harder to hold in your head. I recommend sketching the two markets side by side with separate MR curves and a common MC curve intersecting both. The visual clarity makes the algebra almost irrelevant.
Common Pitfalls Across All Structures
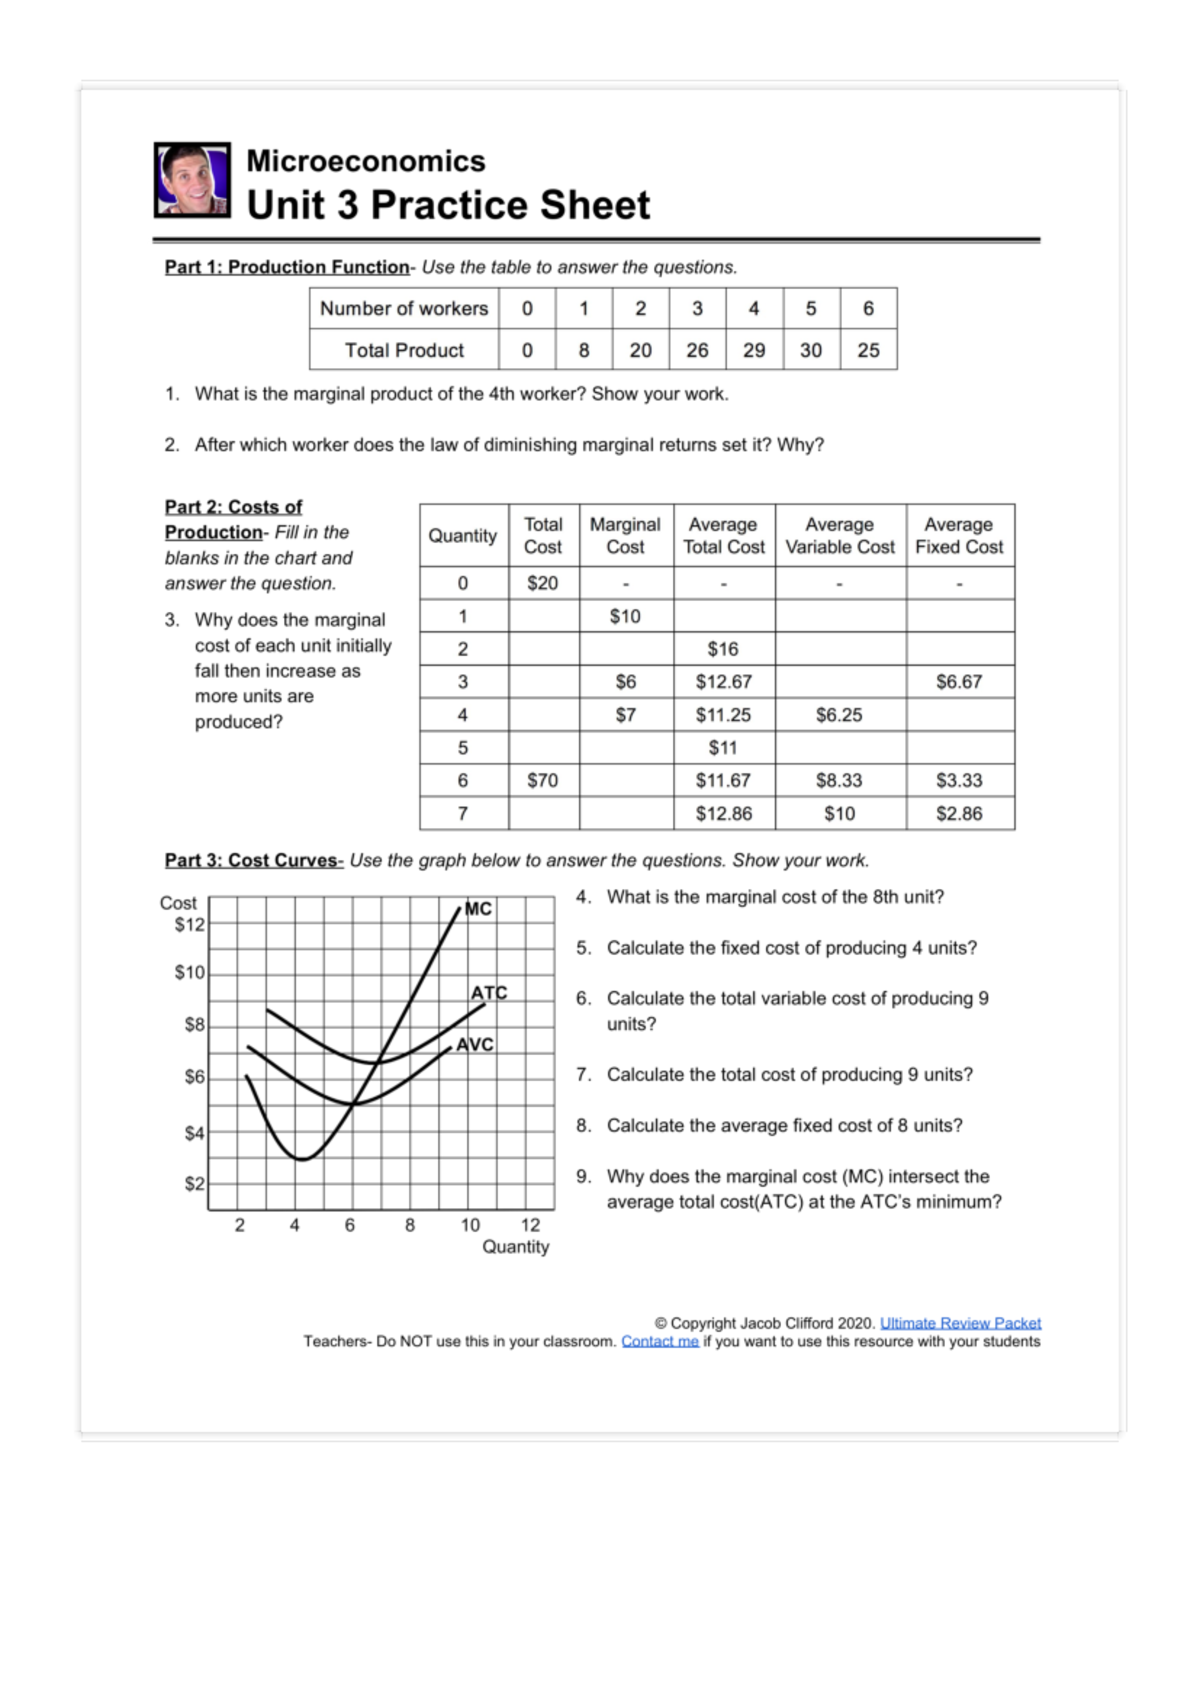
There are three patterns where students consistently lose points. The first is confusing shutdown with exit. A firm shuts down in the short run when price falls below average variable cost. It exits in the long run when price falls below average total cost. These are different timeframes with different cost considerations. The second is misidentifying the profit-maximizing rule. MR equals MC applies to every market structure, not just perfect competition. Students often write that perfect competition uses P equals MC while other structures use MR equals MC. That's wrong. P equals MC is a consequence of MR equaling P under perfect competition, not a separate rule. The underlying principle is always MR equals MC. The third pattern is drawing graphs incorrectly. Demand curves for monopolistic competitors and monopolies slope downward. Marginal revenue curves lie below them and slope downward twice as steeply under linear demand. Average total cost curves are U-shaped. Marginal cost curves cut through the minimum point of ATC. If your graph shows MR above demand, or MC parallel to ATC without intersecting at the minimum, you've made a structural error and the rest of your answer doesn't matter. I spend the first week of Unit 3 having students draw these graphs by hand every single day until they can do them from memory without looking at a reference. It sounds excessive. It isn't. Graph literacy determines whether you score a 3 or a 5 on the AP exam.
What This Unit Actually Tests
The AP Microeconomics exam doesn't ask you to define four market structures and move on. It asks you to analyze a scenario, identify which structure applies, draw the correct graphs, calculate deadweight loss or consumer surplus, and explain the long-run adjustment process. The free-response questions combine concepts from multiple units. A monopoly question might ask about externalities in the same paragraph. A perfect competition question might reference a tariff or a price ceiling from Unit 2. Practice with released FRQs from College Board. They're available for free and they show you exactly what kind of reasoning earns points. The rubrics are strict but predictable. Each question breaks into identifiable parts, and each part awards one or two points for specific elements like showing the correct graph, stating the right rule, or explaining the direction of change. If you can map your answer to those rubric items, you'll score well even if your explanation isn't elegant. The opposite is also true — a beautifully written paragraph that misses the required technical element gets nothing.