Why most real estate agents are flying blind with their commission math
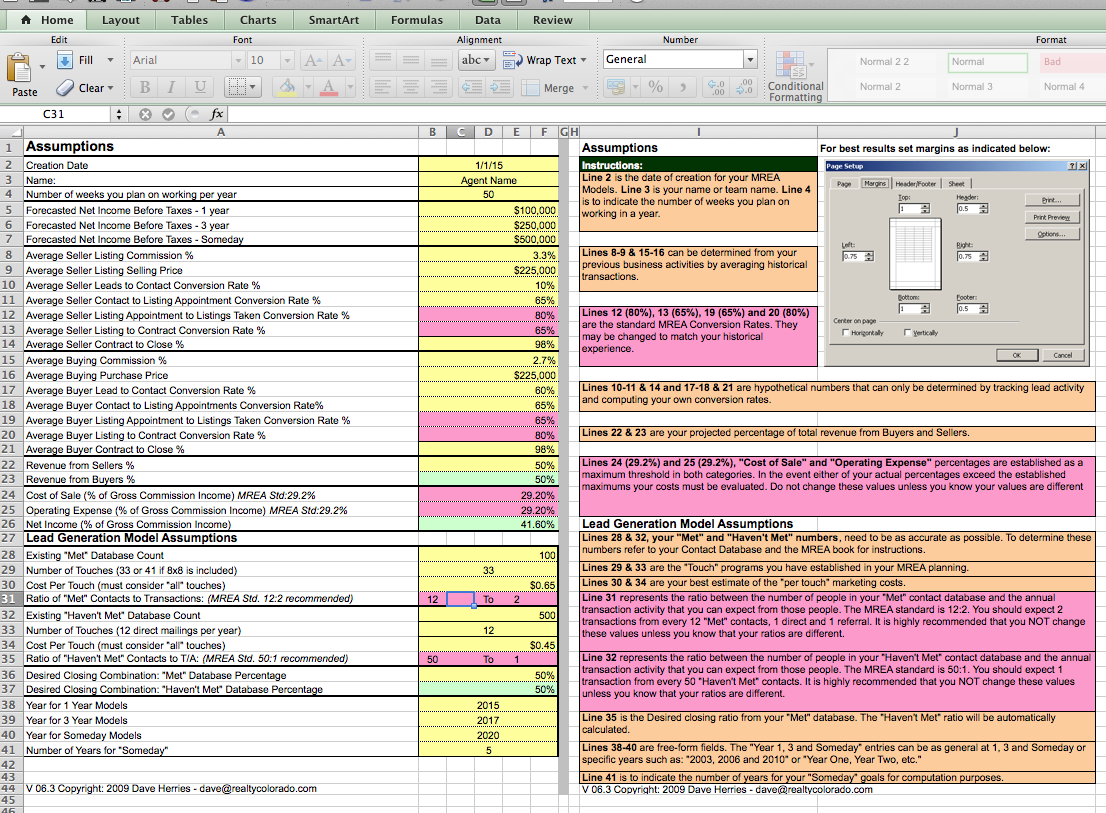
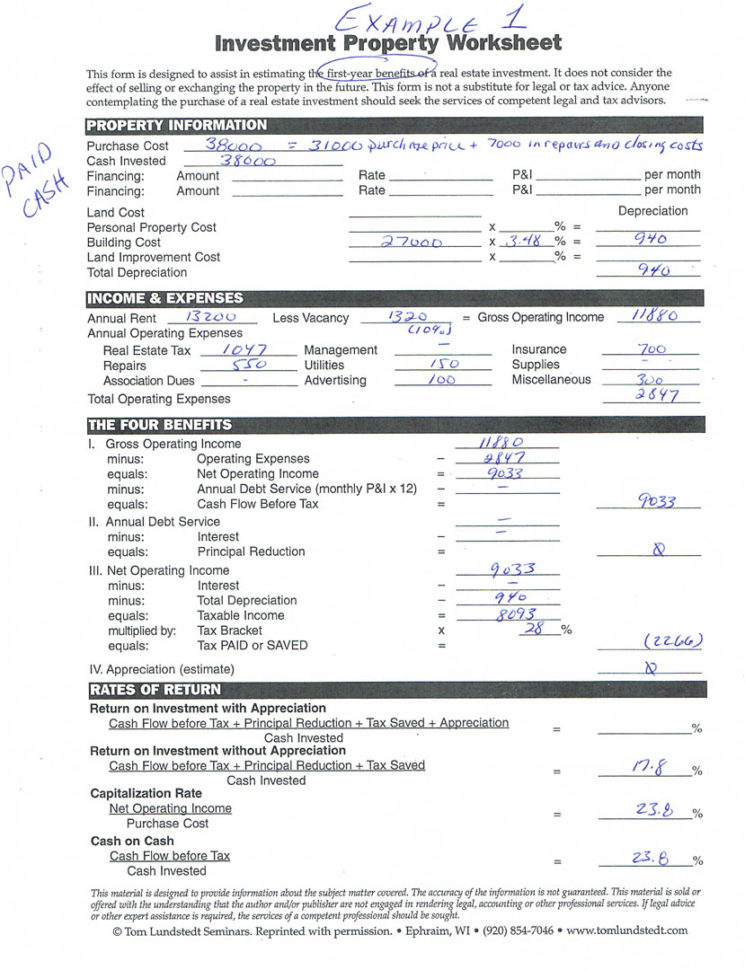
I spent six years on the sales floor before I ever bothered to build a proper worksheet system. Made plenty of rookie mistakes along the way — underquoting commissions, eating closing cost overruns out of my own margin, the whole thing. What changed was getting serious about the actual numbers instead of eyeballing them from memory. That's when Millionaire Real Estate Agent Worksheets became essential for me. The concept is straightforward enough. You're tracking every financial variable across a transaction — commission splits, broker fees, advertising spend, transaction coordination charges, title and escrow pass-throughs, referral payouts if applicable. Most agents operate on gut feel and basic percentage multiplication. The worksheets force you to model every line item before you list a property or make an offer on behalf of a client. It takes about an hour to set up properly the first time, then minutes per transaction after that.
Millionaire Real Estate Agent Worksheets
Here's how the system actually works in practice. I use a multi-sheet structure. Sheet one handles the listing side — gross commission rate, split ratio with the listing broker, inside co-broke percentage, advertising budget allocation, staging costs if any. Sheet two covers the buyer agent side — commission offer to cooperating brokers, any buyer concession handling, and net proceeds projections for my client. Sheet three is the reconciliation tab where I cross-reference all incoming and outgoing funds against the actual settlement statement after closing. The first version I built was just a flat spreadsheet with hardcoded rates. That broke immediately when I picked up a transaction in a county with nonstandard fee structures — attorney review periods, county transfer taxes that varied by property value tiers, municipal surcharges that some agents completely forget about. I had to rework the template to include configurable fee schedules per jurisdiction. Now I maintain a separate lookup table for each market I operate in, and the main worksheet pulls rates dynamically instead of hardcoding them. A detail most people miss: the co-broke offer is not the same as your actual commission income. If you list at 2.5 percent and offer 2.0 percent to the selling side, your gross is 0.5 percent unless your broker has a different split structure. I've seen agents quote clients based on the total commission without accounting for their broker cut, which makes a high-volume agent look profitable on paper while actually losing money on every deal. The worksheet makes this math impossible to gloss over.
Another counter-intuitive thing I learned the hard way. Higher commission rates don't always mean higher net income. In markets where the competition drives co-broke offers up to 2.8 or 3.0 percent, your effective retention drops below 10 percent of the gross even at a standard 3 percent listing rate. Some agents in those markets switch to flat-fee structures or reduced-rate models precisely because the traditional percentage approach erodes into thin margins at volume. The worksheet helps you see that inflection point before you commit to a pricing strategy. Here's the edge case I ran into last year that nearly cost me a client relationship. I was modeling a luxury listing where the seller agreed to a 3 percent commission but the property was in an HOA district with special assessment fees that typically run $4,000 to $8,000 per transaction. I hadn't built those into the original projection. The closing disclosure came in $6,200 higher than my net proceeds estimate, which made the seller's anticipated take-home significantly lower than what I'd discussed upfront. I owned the mistake immediately, revised the worksheet to include HOA special assessment as a configurable line item, and provided the seller with a corrected projection within 24 hours. Nothing rebuilds trust faster than admitting the error and fixing it without being asked. The workaround I adopted after that was creating a jurisdiction checklist that runs before any transaction gets entered into the main worksheet. It captures HOA status, special assessment history, municipal transfer tax brackets, attorney-required states, and any local surcharge programs. Once that data is populated, the underlying calculation engine applies it automatically. It added about twenty minutes to my pre-listing workflow but eliminated three separate classes of cost overruns that used to hit me unpredictably.
Get the Full Details
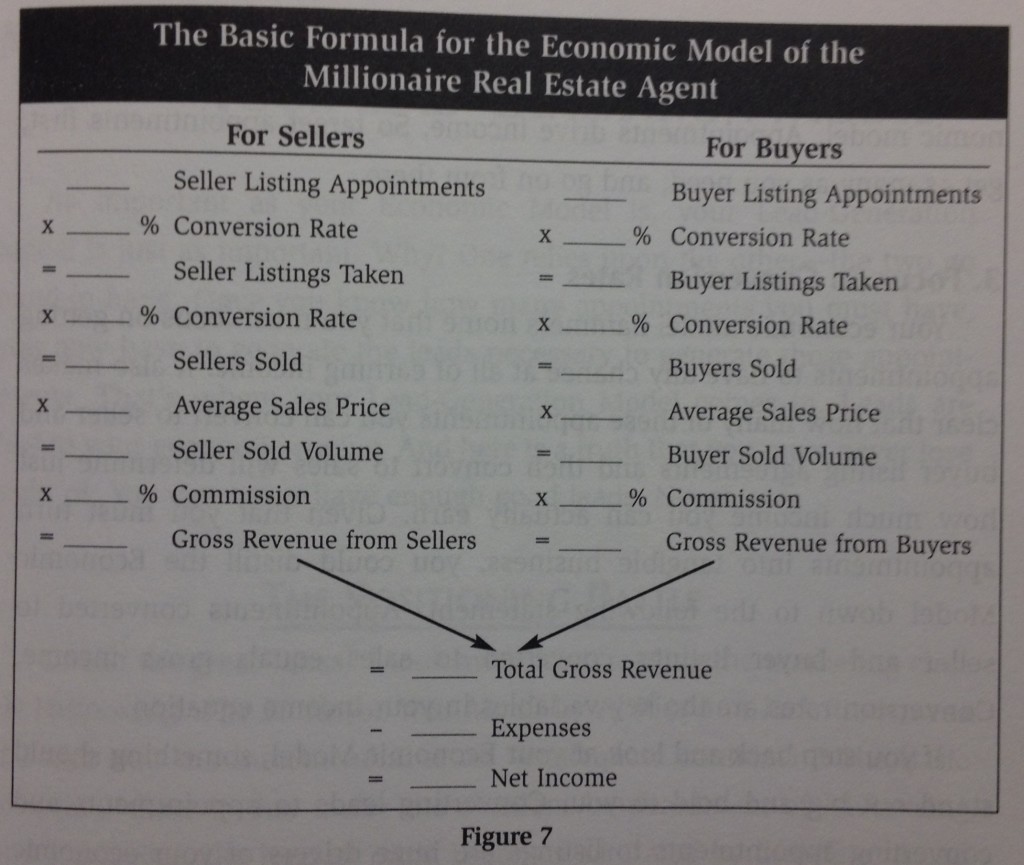
For anyone looking to download or build their own version, the simplest approach starts with a blank spreadsheet and five columns: line item, description, rate or fixed amount, calculated value, and notes. Build rows for gross commission, broker split, co-broke offer, advertising, transaction coordinator, marketing photography, lockbox and showaService fees, title company charges, escrow fees, referral payouts, and net to agent. That alone covers roughly 80 percent of what a working agent needs. Anything beyond that depends on your local market quirks and the types of transactions you handle. There are legitimate limitations to this system. It requires honest input — if you enter optimistic closing timelines or skip including certain fees because they feel insignificant, the projections become unreliable. A worksheet is only as good as the data going into it. It also doesn't account for market shifts mid-transaction, like a rate change that happens between listing and closing, or a buyer financing fall-through that resets your timeline entirely. I keep a revision log in the notes column so I can track when assumptions change and why. If spreadsheets aren't your thing, several IDX platforms and CRM systems now include commission modeling features built in. They're less flexible than a custom worksheet but handle the basic math automatically. I'd recommend starting with either a simple spreadsheet template or the built-in tool from whatever platform you already use, then migrating to a more detailed custom version once you've identified which line items consistently surprise you in your specific market.
The bottom line is that transaction math is the single highest-leverage skill most agents never formally develop. You can close twenty deals a year and still not know your actual net income per transaction if you're estimating everything. A proper worksheet system — whether downloaded or self-built — closes that knowledge gap in about ten minutes per deal once it's set up. That's enough time savings over a career to meaningfully impact earning potential, regardless of whether you're tracking down a free template or paying for a premium version. I keep mine updated quarterly because fee structures shift, broker policies change, and new local charges appear without much warning. The habit of reviewing and adjusting the template itself takes maybe thirty minutes a year but prevents dozens of small discrepancies from accumulating into significant errors over time.