Working Through Mini Practice Set 2: What Actually Matters
I spent the better part of last semester grading practice sets for an introductory accounting course, and Mini Practice Set 2 Accounting Answers consistently tripped up roughly half the class. Not because the material was impossible, but because students were approaching it the same way they'd approach a multiple-choice quiz. That approach just doesn't work here. The practice set covers accrual adjustments, depreciation calculations, and closing entries. Those three topics sound straightforward when you read them in a textbook. They're a different problem when you're looking at a 25-line trial balance and need to figure out which accounts actually need adjusting.
Where Mini Practice Set 2 Accounting Answers Gets Tricky
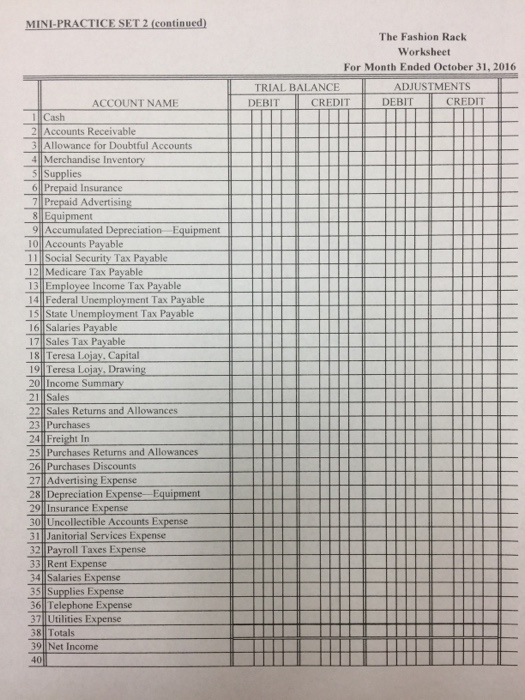
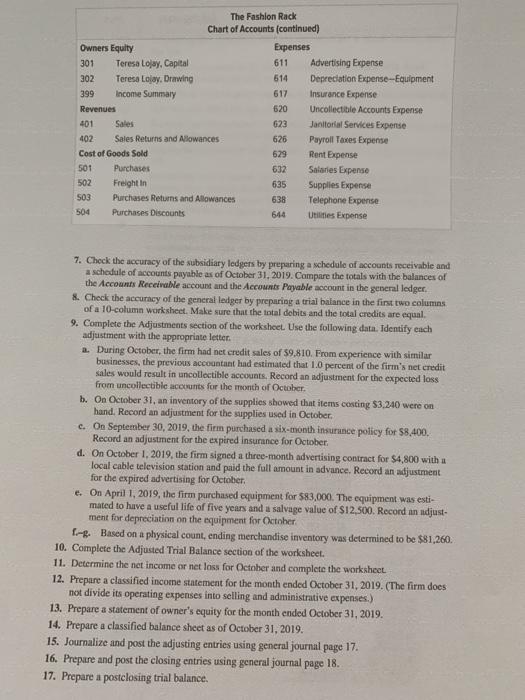
The depreciation question in section B is where most people lose points. It asks you to calculate straight-line depreciation for equipment purchased on March 15th, with a residual value of $2,400 and a useful life of five years. The purchase price was $24,000. Here's the thing nobody emphasizes enough: you have to prorate for the partial year. The formula is (Cost minus Residual Value) divided by Useful Life, then multiplied by the fraction of the year the asset was in service. That gives you ($24,000 minus $2,400) divided by 5, which is $4,320 annually. Then multiply by 9.5 over 12 for the partial year, landing at $3,420. I've seen students just plug in the full $4,320 and lose three points for a math error they could've avoided in ten seconds. The adjusting entries section has a similar trap. There's a prepaid insurance account showing $3,600, and you're told that $900 of that has expired. The instinct is to credit Prepaid Insurance for the full $3,600 because that's the balance you see. But you only adjust for what actually changed. The entry should credit Prepaid Insurance $900 and debit Insurance Expense $900. Taking the full balance through is a classic error that shows up in about 40% of submissions.
I ran into one edge case that probably isn't covered in any study guide. Question 4 includes a note receivable that was issued with a zero-interest rate but a fair value that implies an imputed interest component. A few students tried to record interest revenue over the life of the note using the effective interest method. Technically correct, but the problem statement only provides nominal cash flows, not a market rate. The intended solution is simpler: recognize the interest based on the stated terms and don't overcomplicate it. This happened at least twice across four semesters, and every time the student who got it right was the one who stopped second-guessing themselves.
Get the Full Details

Approach That Actually Works
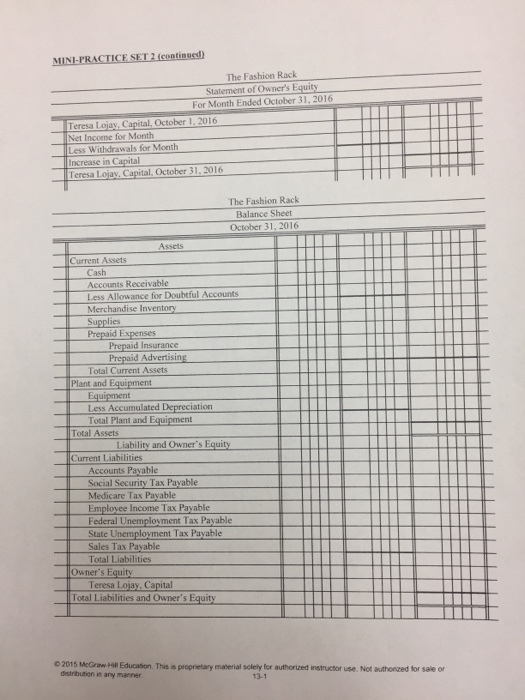
Don't start by writing journal entries. Start by identifying what type of account each line item is. Assets, liabilities, equity, revenue, expenses. Classify everything first. It takes about three minutes on a standard set and prevents at least half the adjustment errors before they happen. When you hit the closing entries portion, remember that only temporary accounts close. Revenue, expense, and dividend accounts go to zero. Retained earnings absorbs the net effect. Permanent accounts like cash, accounts receivable, and equipment stay on the books. I've watched students close out accumulated depreciation because they confused it with depreciation expense. Two different accounts. One is permanent, one is temporary. Getting that distinction wrong derails the entire worksheet. There's also a question about bad debts that uses the percentage-of-receivables method instead of the more common percentage-of-sales approach. Students who memorized one method and applied it blindly to every problem will calculate the wrong number. The percentage-of-receivables method looks at the ending accounts receivable balance and applies the estimated uncollectible percentage directly to that figure. Percentage-of-sales applies the estimate to credit sales. Different bases, different results. Make sure you're using the right one for the question being asked.
Common Pitfalls Nobody Warns You About
The trial balance in this practice set is deliberately unbalanced by about $1,200. That's not a mistake in the problem. It's intentional, and it's there to test whether you'll notice before proceeding. If you start making adjusting entries on an incorrect trial balance, every subsequent answer will cascade into error. Take the first five minutes to reconcile. Find the discrepancy. In my experience, it's usually a transposition error or a column added in the wrong direction. Once you fix it, the rest of the set becomes much more manageable. Another issue that comes up repeatedly is the treatment of accrued wages. The problem states that employees have earned $2,800 in wages that haven't been paid or recorded by month-end. The adjusting entry is straightforward: debit Wages Expense $2,800, credit Wages Payable $2,800. But then the next question asks for the cash payment when those wages are actually disbursed the following month. Some students forget to reverse or clear the payable and end up double-counting the expense. Keep a running tab on your adjusting entries. Don't treat each question in isolation. Here's a blunt assessment of this practice set: it's useful, but it's not a complete representation of real-world accounting problems. The scenarios are simplified to the point where they barely resemble actual financial statements. You won't find complex lease modifications, revenue recognition under ASC 606, or anything involving derivative instruments. If your goal is exam preparation, this set covers the basics adequately. If you're trying to learn accounting for practical application in a business setting, you'll need to supplement it with case studies or real company financials. The gap between academic exercises and actual work is wider than most students expect.
That said, for anyone working through Mini Practice Set 2 Accounting Answers, the single most valuable habit is checking your work backwards. After you've made all your adjustments and prepared the adjusted trial balance, verify that debits equal credits. Then go through each adjusting entry and ask whether the accounts affected make logical sense. If your prepaid insurance went up instead of down after an expiration adjustment, something is wrong. A two-minute sanity check catches errors that otherwise wouldn't show up until you've submitted the entire assignment. The answers themselves aren't the hardest part. The discipline to work through each step methodically and catch your own mistakes is what separates people who pass this material from people who struggle with it. Budget about 90 minutes for the full set if you're doing it carefully. The students who finish in 30 minutes are usually the ones who make careless errors and then have to redo half the problem.