Setting Up a Minimalist Finance Journal Notebook
I first tried the Minimalist Finance Journal Notebook two years ago after burning through three complicated budgeting apps. Most of them ended up becoming cluttered dashboards I barely looked at. What worked was stripping everything down to a single ledger, one page per month, and writing transactions by hand. Not tracking spending, not analyzing it in real time, just recording it. That discipline is what makes the notebook actually useful instead of another forgotten tool. The setup takes about twenty minutes total. You grab a blank notebook with unlined or lightly lined pages. Open it to the first page. Write the month and year across the top. Draw two vertical columns. On the left side, list your income sources — salary, freelance work, any recurring deposits. On the right side, list your expense categories. Keep them simple: rent, utilities, groceries, transport, subscriptions, entertainment, miscellaneous. That is it. No subcategories. No color coding. No tags.
How the Minimalist Finance Journal Notebook Actually Works
Every day, you write one line per transaction. Date, category, amount, and a note if needed. When a bill arrives, you record it the same day. When you buy something small, you write it in. The process usually takes between three and five minutes daily once you are settled. The entire method collapses under its own weight if you skip days for more than a week, which happened to me around month three when I got busy with a project deadline. My first workaround was to set a phone reminder at 9 PM every night to log that day's transactions before bed. It felt annoying at first but within two weeks it became automatic. One thing most people miss about this approach is the reverse entry method. Instead of recording expenses as negative numbers and calculating balances constantly, you write all entries as positive values and compute the month-end surplus or deficit manually. This sounds trivial but it changes how you read the page. You are scanning columns of spending, not doing subtraction on every line. It speeds things up noticeably and reduces the temptation to avoid the notebook because the math feels tedious. There is a specific edge case that catches people out, and I ran into it myself. I had a gym membership that billed quarterly rather than monthly, along with a car insurance payment that arrived on a non-standard date. Both entries disrupted my category totals for whichever month they landed in. The fix was to create a separate row at the bottom of each monthly page labeled "recurring annual items" and log those separately instead of mixing them into the main expense categories. That kept the monthly view clean and made annual planning easier later. It took me about four months to realize that was the right approach instead of trying to force irregular payments into standard buckets.
Another nuance beginners overlook is the running balance column. Some templates include one, some do not. I stopped using it after the first month because it required constant updating and introduced more opportunities for errors than it prevented. Without a running balance, you simply total income and expenses at month's end and compare them. The difference tells you whether you saved money or overspent. The calculation takes about thirty seconds. The notebook also has real limitations that are worth stating plainly. It does not integrate with any bank or app, which means you are entirely responsible for data entry accuracy. If you lose the notebook, your financial records go with it unless you photograph each page. It is also poorly suited for complex households where multiple income streams and shared accounts make single-column tracking insufficient. In those cases, a split-approach notebook or a basic spreadsheet with two sheets per person works better. The minimalist finance journal notebook assumes you have one primary account to track and straightforward income patterns. For people who want something digital, the main alternative is a plain text file tracked in a notes app. It serves the same purpose but sacrifices the tactile experience that keeps most people consistent with manual tracking. The physical act of writing something down increases recall and attention to detail compared to tapping entries into a phone screen. That difference matters more than most users expect.
Get the Full Details
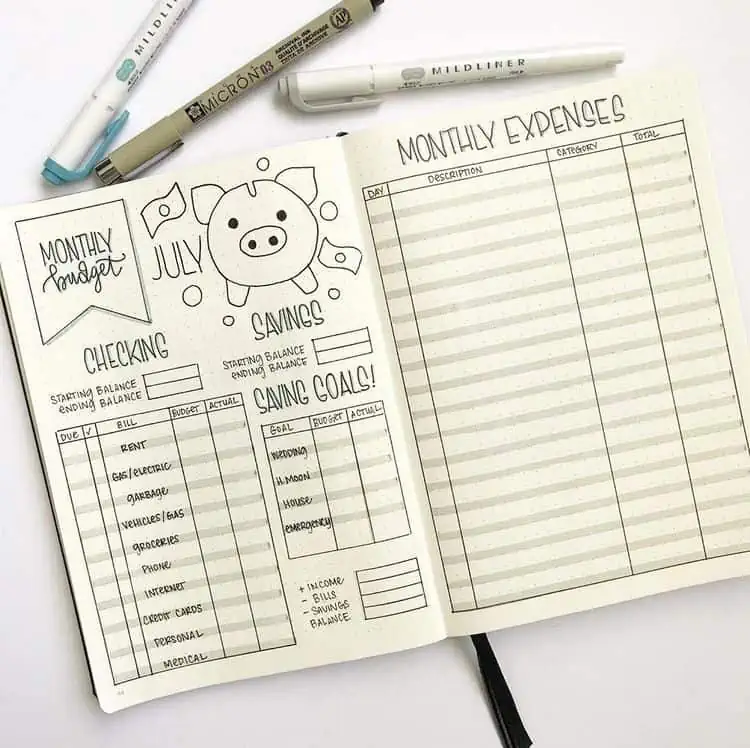
If you want to create your own version of a Minimalist Finance Journal Notebook, start with a fresh notebook and divide the first page exactly as described. Do not add features you think might be helpful later. Extra columns and sections tend to accumulate over three to six months and then get abandoned. The method only works when it stays small enough to maintain without thinking about it. A downloadable template exists from a few independent creators on personal finance forums, but making your own takes less time than downloading and adjusting someone else's layout. The essential structure is two columns and one entry per transaction. Anything beyond that is decoration. The real test of whether this works for you comes after three months. By then you either have a consistent habit or you have discovered that the manual entry requirement does not fit your lifestyle. Both outcomes are useful information, even if the answer is that you should switch to a different system entirely. The notebook itself is neutral about the result.