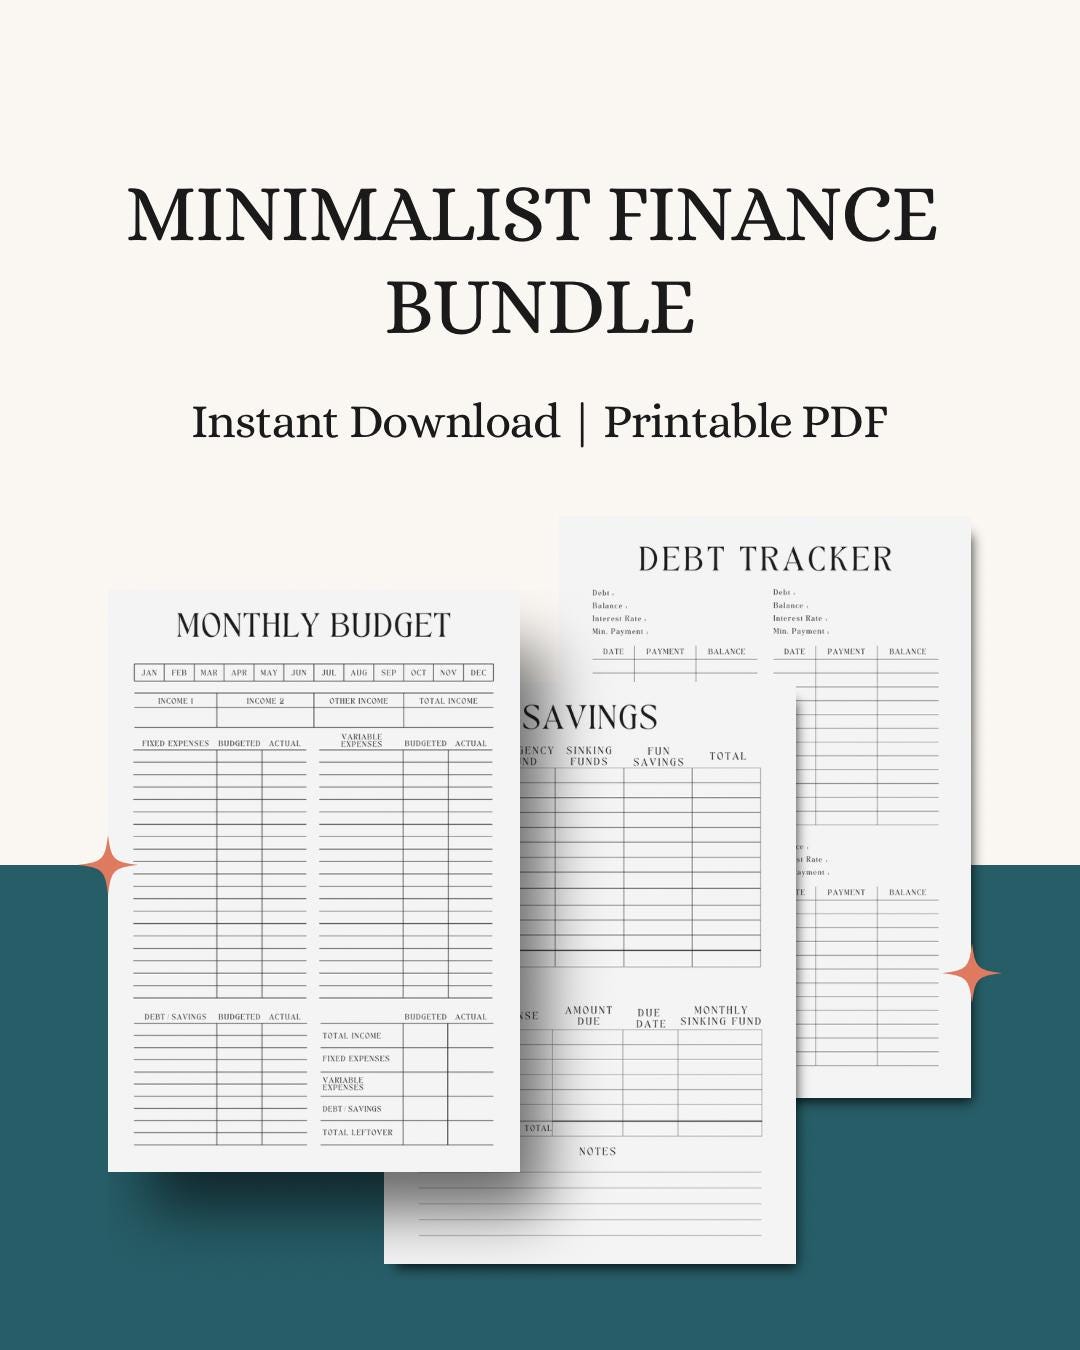
What You Actually Get When You Download a Minimalist Finance Pdf
The concept is straightforward enough. You strip your financial life down to a single tracking sheet. No budgeting apps with a hundred toggles and notifications. No subscription services to manage. Just income, fixed expenses, variable spending, and savings targets on one page. The reason people keep coming back to this approach isn't because it's clever. It's because every other system adds so much friction that they eventually quit. When I first built my own version of this back in 2018, I spent three days tweaking categories until the spreadsheet looked right. Then I used it for exactly two weeks before going back to nothing. The problem wasn't the method. The problem was that I'd made it too detailed. I had separate rows for coffee, groceries, gas, streaming subscriptions, phone bill, gym membership, internet, and twelve other line items. By Tuesday I was already tired of entering data. That's a common trap beginners hit. They confuse comprehensive with useful. The actual mechanism works like this. You set a monthly income ceiling. You allocate fixed costs first. Whatever remains gets split between variable spending and savings. That's it. The formula takes about five minutes to write out. Here's the structure:
Income minus Fixed Obligations equals Discretionary Pool. Discretionary Pool times your savings percentage goes to savings. Whatever is left is your spending allowance. I learned the hard way that this only works if your fixed obligations are actually fixed. The first time I ran into a real snag was with health insurance premiums that changed mid-year when my employer switched carriers. My spreadsheet had them locked at $340 a month. They jumped to $412. I'd already committed my discretionary pool based on the old number, which meant I was suddenly underwater by the third week of the month. The workaround was simple but annoying. I created a separate reserve row called "Premium Adjustment" that I checked once a quarter instead of every month. Quarterly is enough for most people. Most premiums don't fluctuate that wildly. Here's something most guides don't mention. The minimalist approach actually breaks down in two specific scenarios. The first is when you have highly irregular income. Freelancers, commission workers, seasonal employees. If your income jumps from $4,200 one month to $11,000 the next, a flat allocation system either leaves you overtrapped in some months or scrambling in others. The fix is to use a trailing average. Calculate your discretionary pool based on your lowest month of the year, not your average. Your high months become pure buffer instead of wasted capacity.
The second failure point is debt with variable interest rates. A minimalist Finance Pdf template usually treats your credit card minimum payments as fixed. But if you're carrying a balance and the rate moves, your minimum payment shifts. That silently eats into your discretionary pool without any alert. I didn't catch this until a 3 percent rate hike cost me an extra $18 a month that vanished into the black hole of payments I hadn't accounted for. The solution is to recalculate fixed obligations every six months, not just when rates change randomly. The real advantage of this system becomes obvious once you stop treating it like a budget and start treating it like a ceiling. A budget tells you where every dollar went. A ceiling tells you how much you're allowed to touch. The difference matters. Budgets require constant monitoring. Ceilings only require one check per month. Most people who stick with minimalist finance do it because they can close the spreadsheet and actually live their life instead of feeling guilty about every latte. If you want to build your own, start with four rows. Income. Fixed costs. Variable spending. Savings. That's it. Don't add more until you've used it for ninety days. Ninety days is the threshold where most people figure out whether they actually need more detail or just wanted to feel productive. Your spreadsheet will sit there looking impressive and do nothing for your actual financial behavior.
Get the Full Details
For the download itself, there isn't one universal version. The format varies enough that you'll need to adjust the columns to match your actual numbers. The core logic is identical across every template I've seen. Look for one with a single summary row at the top showing your discretionary pool. That row is what matters. Everything else is decoration.