Why Most Budget Spreadsheets Fail Before February
I built my first finance workbook around 2014, back when I was still doing this seriously enough to care about getting every decimal right. It had eight sheets, fifteen conditional formatting rules, and an auto-calc macro that broke every time I rearranged columns. It took me forty-five minutes each week to update and another twenty to reconcile. I used it for eleven months. Then I abandoned it for something far less impressive. The problem isn't the math. The problem is friction. Any tool that requires more than five minutes of weekly attention to maintain will lose you before the quarter ends. That's not philosophy. That's just what happens when you track your spending manually across six different categories while also keeping your actual life going.
What a Minimalist Finance Workbook Actually Does
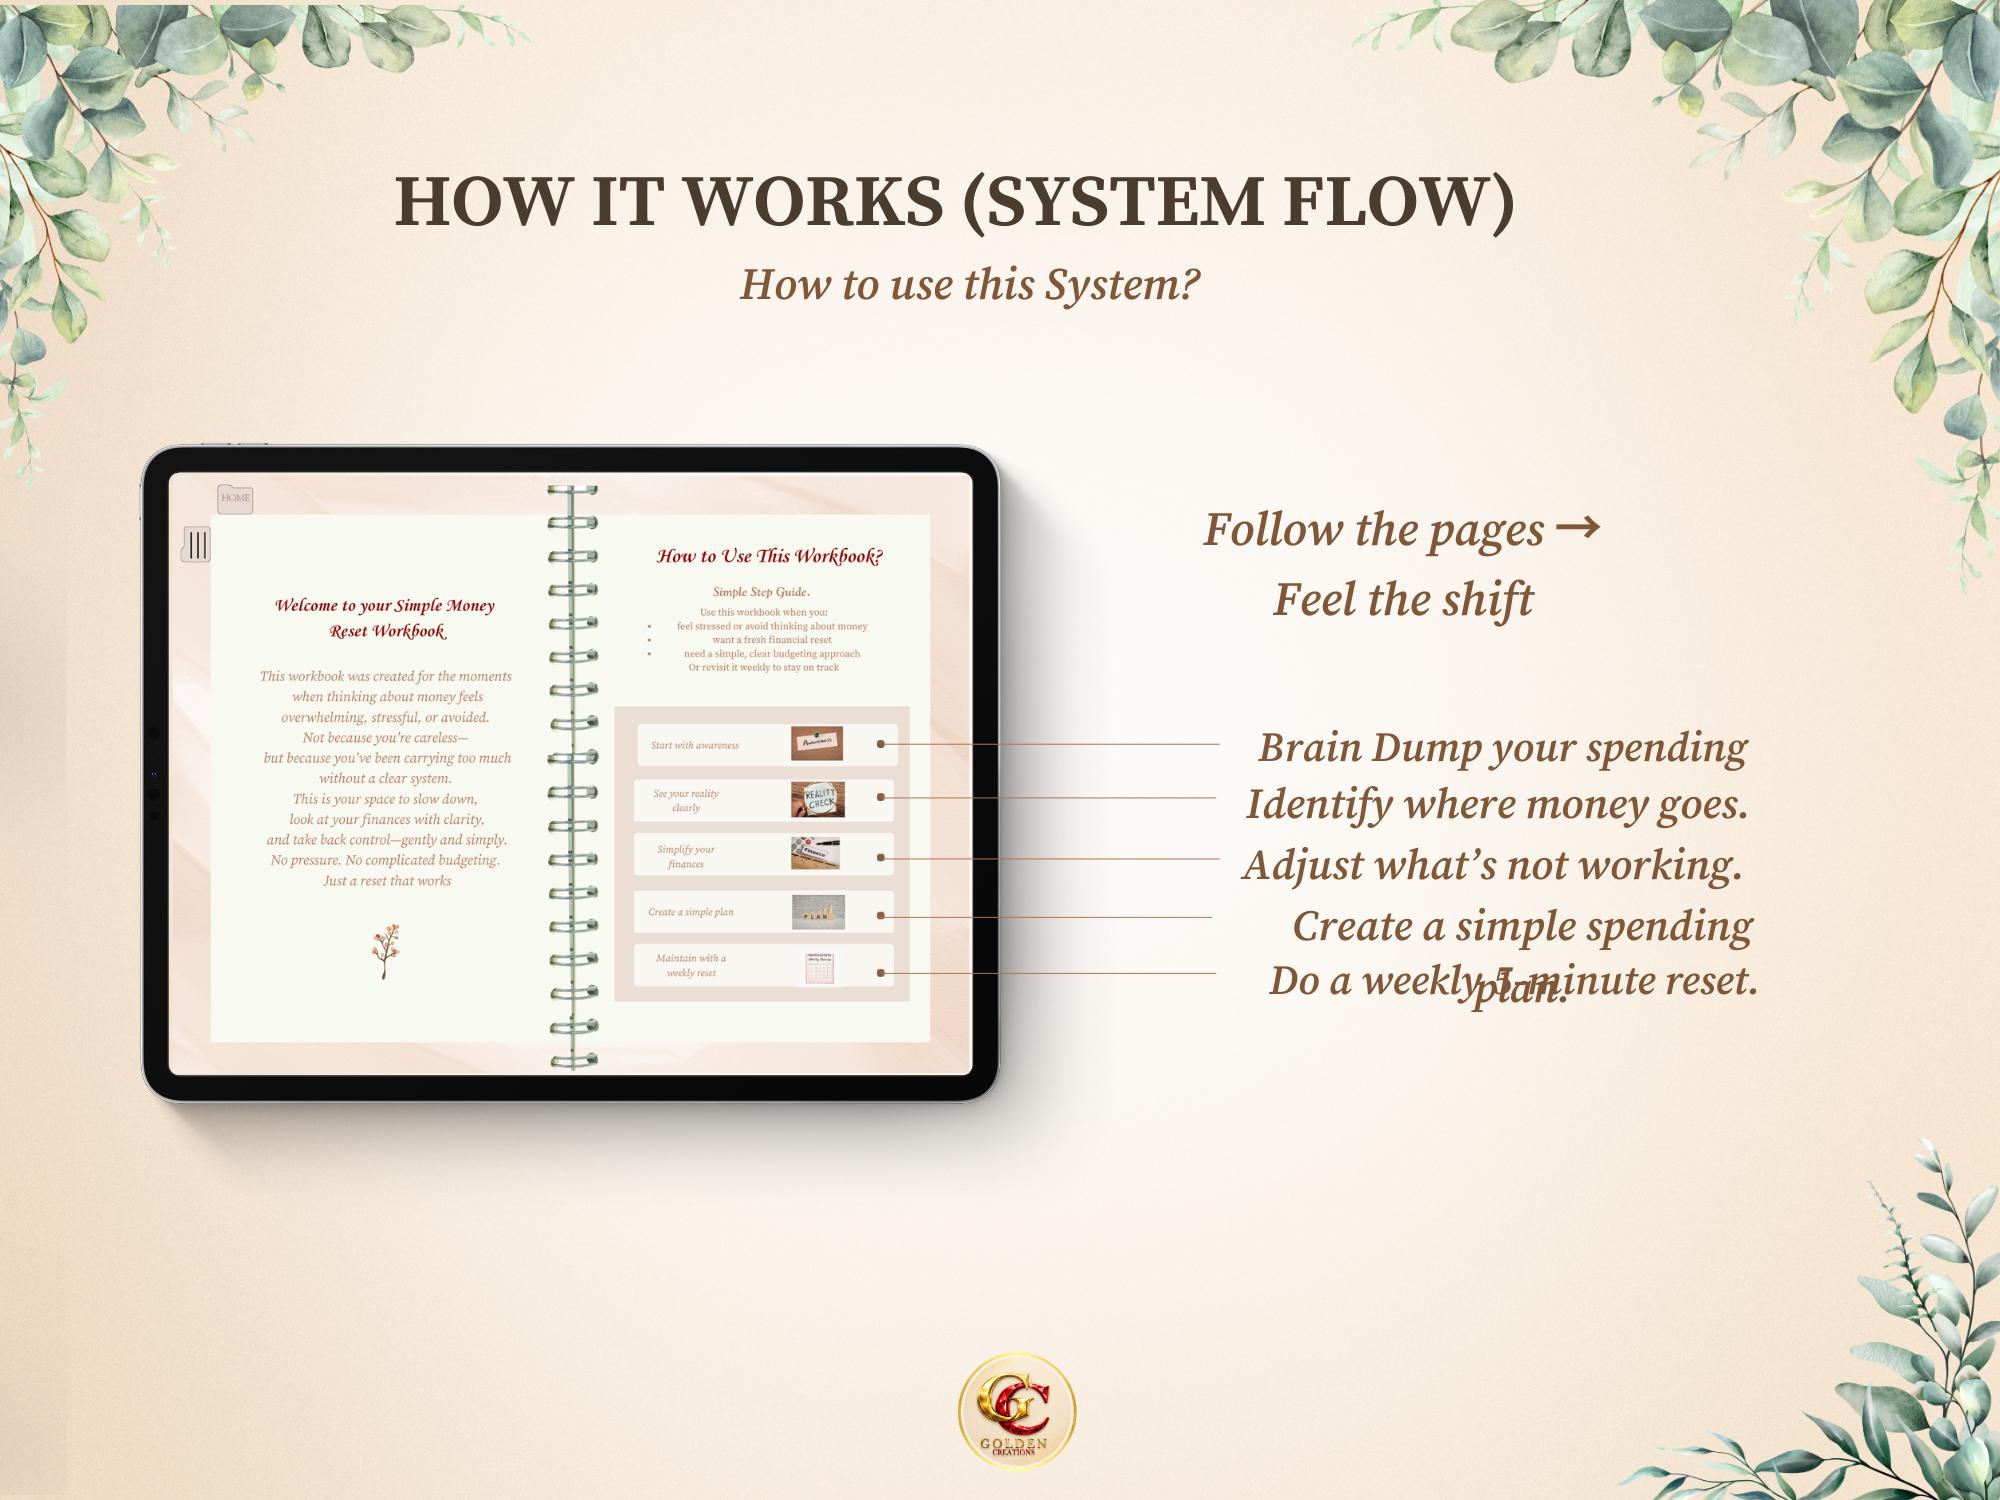
A Minimalist Finance Workbook strips away everything that doesn't directly answer three questions: how much money came in, how much went out, and where is it now. Everything else is optional. The core sheets you need are income, expenses, balances, and a monthly summary. That's it. The income sheet logs your paycheck amounts and dates. The expense sheet logs transactions. The balance sheet shows your current position at any given point. The summary consolidates the numbers into something you can read in thirty seconds. I keep mine in Google Sheets because it syncs across devices and auto-saves, but the same structure works in Excel, Numbers, or any spreadsheet program. The format matters less than the discipline of actually opening it.
Building One From Scratch
Create four sheets and name them plainly. Income, Expenses, Balances, Summary. Do not overthink the naming convention. You will be looking at these labels daily for years. In the Income sheet, set up columns for Date, Source, Amount, and Category. That is four columns. Nothing else. When a check hits your account, log it. If you get paid biweekly, that is twenty-six entries per year. It should take roughly three minutes total per month to enter everything. In the Expenses sheet, use columns for Date, Description, Amount, Category, and Account. The Account column is what most people skip and immediately regret. Without it, you cannot distinguish between money you have available and money already committed to a separate account. I learned this the hard way when I had a checking account balance showing $2,400 on paper but only $612 in reality because $1,788 was sitting in a savings account I hadn't accounted for in the workbook.
Get the Full Details
The Balances sheet should pull from your transactions using simple SUMIF formulas. Each row represents one of your accounts, and the formula sums all expense and income entries tied to that account label. Keep the formulas short and readable. You will need to debug them in six months when something looks wrong. The Summary sheet is where you aggregate everything. Monthly income, monthly expenses, net change, and current total balance across all accounts. Use SUMIFS with date range criteria so each month updates automatically as you add transactions.
The Setup That Actually Sticks
The biggest mistake I see people make is building elaborate categorization systems upfront. You do not need twelve subcategories for dining. You need one row labeled "Food" and maybe one for "Transportation." The categorization complexity scales inversely with how often you actually use the tool. The fewer categories you create, the more often you will open the file. Set your expense sheet to sort by date descending so your most recent entries appear at the top. This saves time because you are always looking at the bottom of your transaction list, and sorting ascending means scrolling past thirty rows every time you want to add a new entry. It is a small thing but it compounds across hundreds of transactions. Lock the header rows. I use the freeze panes feature in Sheets or the freeze top row option in Excel. You will not notice this matters until you are scrolling through fifty entries and lose sight of which column is which.
Minimalist Finance Workbook Template Structure
If you want a reference layout, here is exactly what I use. Income sheet: columns A through D. Expenses sheet: columns A through E. Balances sheet: columns A through C with SUMIF formulas pulling from the Expenses and Income sheets by account name. Summary sheet: columns A through D with monthly aggregation formulas using SUMIFS date filters. No merged cells. No data validation dropdowns that slow down entry. Conditional formatting is limited to highlighting negative net income in red. That single conditional format rule replaced twelve others I had in previous versions. I also set a named range called "AllExpenses" covering the entire Expenses column C (the Amount column). This lets me reference it cleanly in formulas without writing clunky ranges like Expenses!$C$2:$C$500. Named ranges look professional and save time when you are writing the same formula across multiple cells.
Common Pitfalls I Still See People Hit
The first pitfall is reconciling too frequently. Beginners tend to reconcile their workbook against bank statements every single day. This is unnecessary unless you are actively hunting for fraud or discrepancies. Once a month is sufficient for the vast majority of people. Weekly is fine if you have irregular cash flow or are trying to nail down spending patterns in the first few months. Daily reconciliation is almost always a sign that something else is wrong with your system, not that you need more frequent checks. The second pitfall is mixing personal and shared expenses without clear markers. I once had a client who tracked both household and personal expenses in the same expense sheet without distinguishing them. Three months in, he could not tell whether his $3,200 monthly spend was his individual spending or our combined household budget. The fix was simple: add a column for "Payer" and filter by it on the Summary sheet. I added this to my own workbook afterward because it is easy to forget which transactions belong to whom when you are not paying attention. The third pitfall is relying on bank import features without verifying the data. Most spreadsheet programs can import bank CSV files, but the date formats, description fields, and categorization from your bank are often messy. A $47.32 grocery store charge might show up as "STORE #4829 GRO" in your bank export. If you import blindly, you end up with fifty rows of unrecognizable descriptions that you then spend twenty minutes decoding instead of ten minutes entering by hand. I recommend entering transactions manually for the first month to build the habit, then switching to import once you trust your categories are consistent. Even then, I verify imported data against my bank statements within forty-eight hours of each import. The time savings from import is real but only if you catch the errors quickly.
When This Approach Fails
Minimalist workbook tracking does not work well for people who have more than five income sources or eight linked accounts. At that level of complexity, you start hitting the ceiling of what a flat spreadsheet can handle efficiently. You will find yourself creating workarounds for things that dedicated software handles natively, like automated bank feeds or multi-currency support. If you are a freelancer with irregular income from multiple clients, the basic workbook structure still works but you will need to add a "Project" column to your expense sheet so you can allocate costs to specific jobs. This adds one column and ten minutes per transaction but gives you the profitability data you need without importing a full accounting system. For most people with a primary checking account, one savings account, and a couple of credit cards, this structure handles everything adequately. The workbook should take you between five and fifteen minutes per week to maintain depending on transaction volume. If it is taking longer, you have added unnecessary complexity somewhere. Go back and remove a category or two.
Where to Get a Working Template
I host a clean version of the workbook I described at minimalistfinanceworkbook.com/template. It is the same structure I outlined above. Four sheets, no macros, no external dependencies. You can copy it into your own Google Drive or download it as an Excel file. There is nothing behind a login wall and no email required. If you want to modify it, go ahead. The only thing I ask is that you do not resell it or strip the attribution from the footer. The template includes pre-built SUMIF and SUMIFS formulas for the Balances and Summary sheets. It also has a sample transaction row in each sheet so you can see the expected format before you start entering your own data. I added these examples because the first time someone opens a blank spreadsheet like this, they often hesitate about where to begin and end up spending more time figuring out the structure than actually tracking their money.