Understanding How Minnesota Calculates and Charges Medicare Supplement Premiums
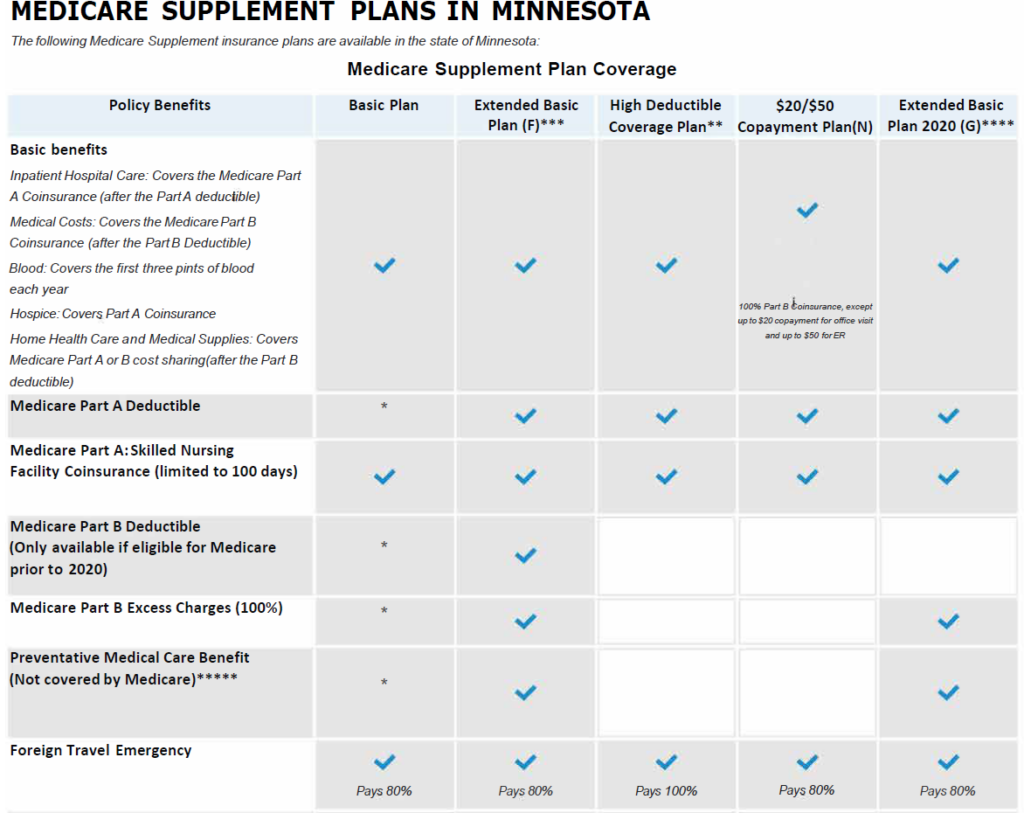
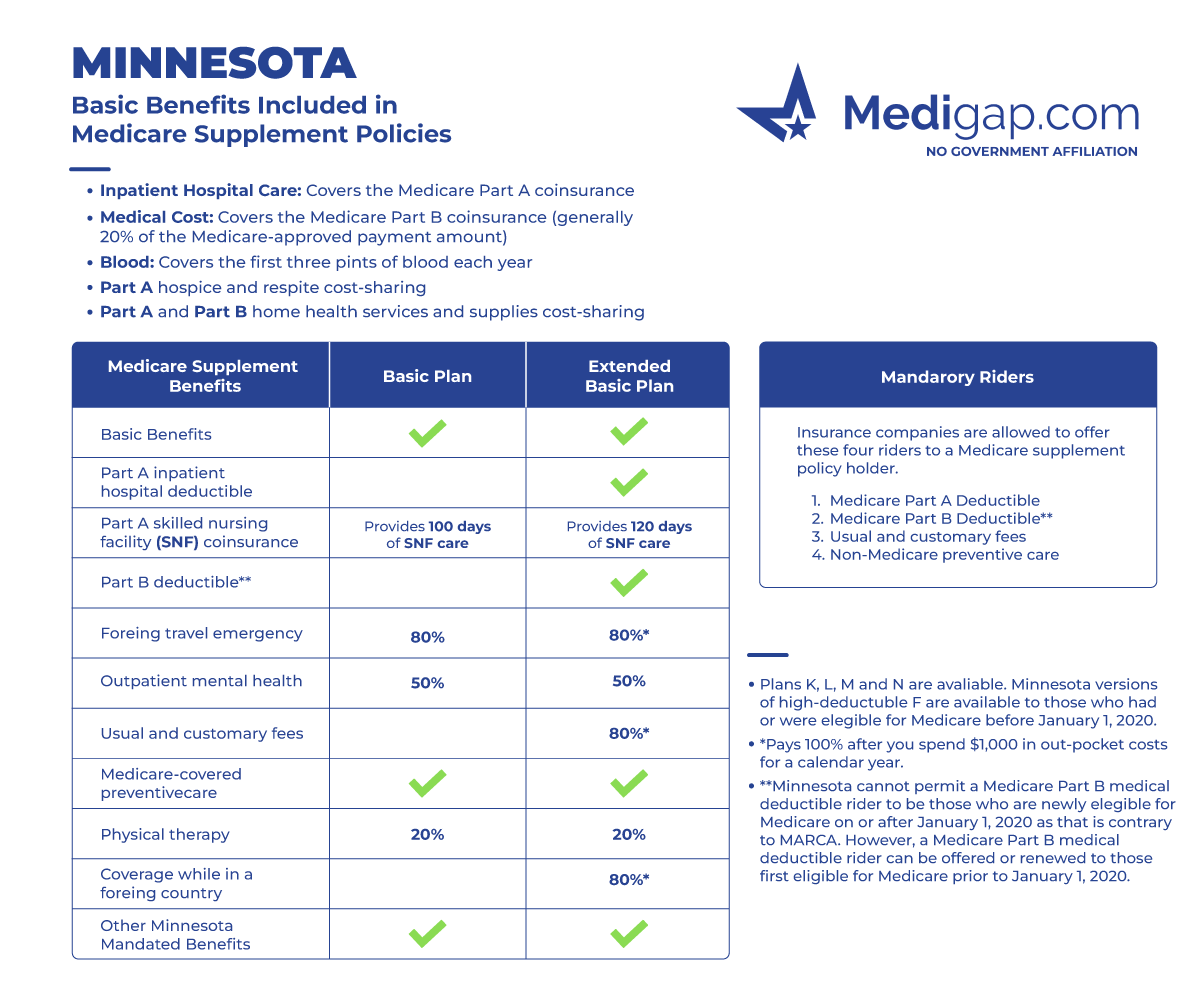
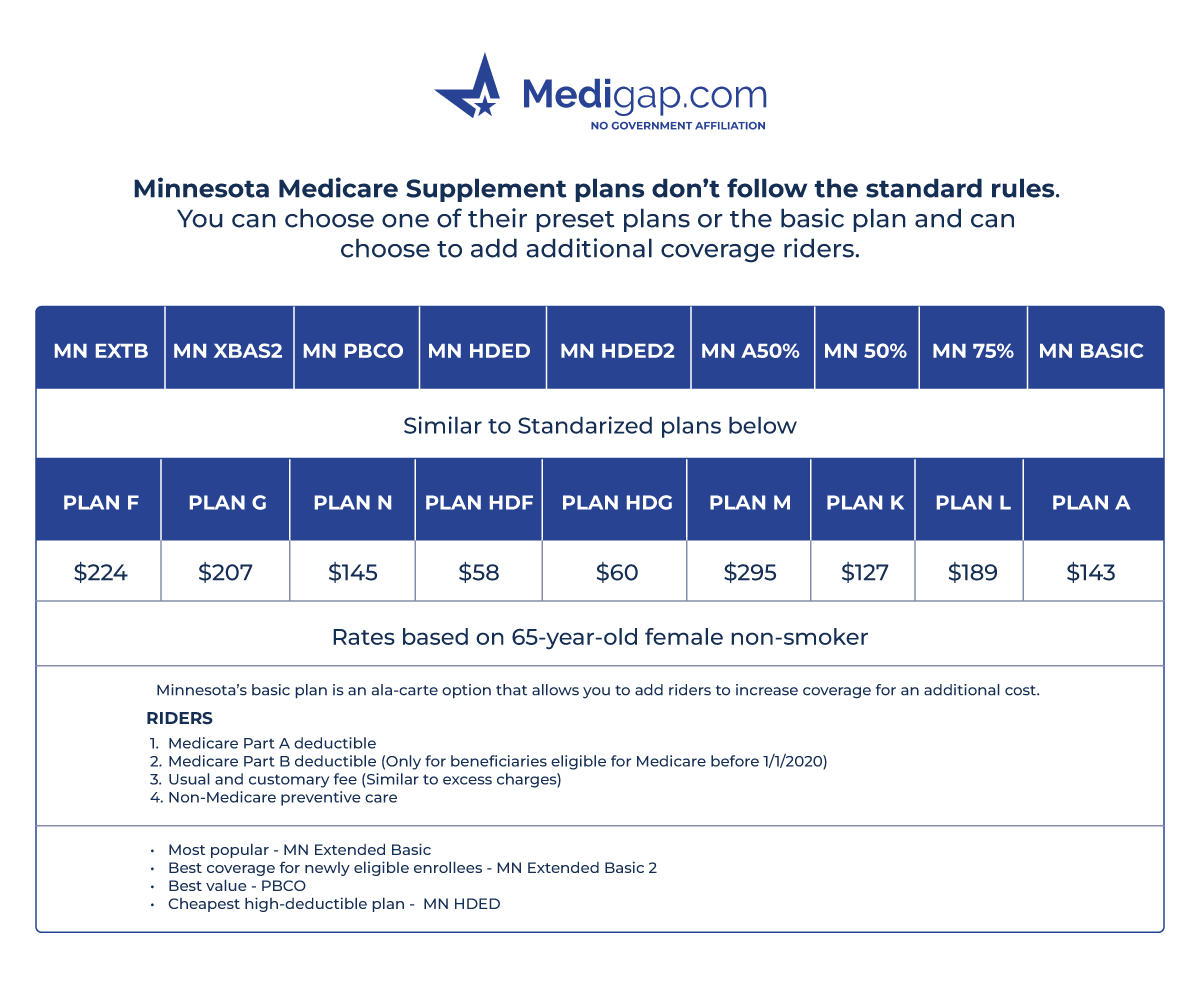
Minnesota runs a different Medigap market than most states. The rating methods, the pricing curves, and the discount structures you find here won't match what your neighbor in Wisconsin or Iowa is paying even for the same MetLife or UnitedHealthcare policy. That disconnect is the first thing you need to clear up before you start comparing numbers. The Minnesota Medicare Supplement Monthly Premium Guide reflects this reality by organizing information around state-specific pricing rather than generic national averages. If you're trying to budget for Part A and Part B alongside your supplement premium, you need to understand what drives the cost and what parts of it are actually within your control. Medigap premiums in Minnesota are primarily shaped by three rating approaches: issue-age rated, attained-age rated, and community rated. About sixty to seventy percent of policies sold in the state fall into the attained-age category, which means your premium goes up every year as you get older regardless of claims experience or inflation adjustments alone. Issue-age rated policies lock in at the age you buy, and the premium is calculated from that starting point forward. Community rated is the flattest curve, though it still adjusts for inflation. Knowing which rating method your specific policy uses is the single most important factor in predicting whether your premium will climb ten percent over five years or stay within three percent of your initial rate. The actual dollar amounts vary so widely between carriers and plan letters that listing specific premiums here would be misleading within a month. What matters more is the mechanism. Every carrier in Minnesota files premiums with the Department of Commerce, and the filing methodology allows for substantial differentiation on identical plan designs. Plan G from one company might run two hundred and forty dollars monthly while another company's Plan G is one hundred ninety-five. The benefits are identically regulated by federal and state law. The difference comes down to actuarial assumptions and target demographics, not coverage quality.
I ran into a concrete problem last year with a client who had enrolled in an attained-age rated Policy A in 2019 at age sixty-four. By 2024 her premium had crept up to one hundred eighty-two dollars monthly. She was frustrated because she'd assumed a sixty-five birthday rate. The workaround was straightforward but required digging into her actual policy documents rather than relying on the brochure she'd received during enrollment. Her policy carried a pre-65 surcharge clause that inflated the base premium by roughly twelve percent until she hit sixty-five, after which it adjusted downward but not back to the standard issue-age rate. The solution was switching to an issue-age rated Plan G during the next valid enrollment window. The premium dropped to approximately one hundred forty-eight dollars and stayed there without age-related escalations. It saved her about four hundred thirty dollars annually and eliminated future rate shock. Minnesota also has a unique discount structure worth understanding. Several carriers offer household discounts when two Medigap policies are on the same policyholder's name, typically reducing each premium by five to eight percent. Some companies extend that to spouse discounts, though the terms vary. This isn't universally available across all plan types and some carriers have eliminated these programs entirely in recent years. Checking current discount eligibility before renewing or switching policies matters more than most people realize. Here's something most people miss about Minnesota Medigap pricing: the guarantee-issue windows interact with premium cost in ways that aren't obvious. If you miss your initial enrollment period and develop a health condition, your guaranteed-issue rights protect you from medical underwriting but they do not protect you from higher premiums. You might qualify for a Plan G during a guarantee-issue period, but the carrier will price it based on your attained age at that moment, which could be significantly higher than if you'd enrolled earlier. The tradeoff between waiting for open enrollment and locking in a lower issue-age rate is real and quantifiable. A sixty-seven-year-old enrolling during a special enrollment period might pay thirty to fifty percent more over the life of the policy compared to enrolling at sixty-five, even accounting for two years of premiums already paid.
The Minnesota Department of Commerce publishes annual premium summaries and allows complaint filings, but their data tends to lag by several months and covers only participating carriers. Independent comparisons using current carrier websites tend to be more accurate for pricing purposes. The department's resources are better suited for verifying carrier legitimacy and checking disciplinary history than for real-time premium shopping. Another counter-intuitive point: having both a Medigap policy and a Medicare Advantage plan simultaneously is illegal and voids both coverages. Some people try this arrangement thinking they can combine the flexibility of supplement coverage with the managed care benefits of an advantage plan. It doesn't work. Carriers audit this, and the Minnesota Department of Commerce actively investigates dual-enrollment violations. The fines and premium repayment consequences are manageable if caught early but expensive enough to avoid entirely. What Minnesota Medicare Supplement Monthly Premium Guide gets right is organizing information around the state's specific regulatory environment. What it misses or omits is often the practical stuff like how quickly premium changes propagate through billing cycles, whether your carrier uses calendar-year or policy-year adjustments, and how often carriers in Minnesota file for rate increases compared to neighboring states. Minnesota has historically been more conservative with rate hikes than many states, averaging around four to six percent annually on attained-age policies over the past decade, but that trend isn't guaranteed to continue.
Get the Full Details

If you're looking to get actual current premium numbers, the most efficient approach is to request quotes from at least three carriers offering the same plan letter and explicitly ask for their rating method and historical rate increase data for that plan in your county. Most agents will provide this if you ask directly. It takes roughly twenty minutes and gives you enough information to make a decision without waiting for annual filing data to catch up. The main limitation of any guide or tool in this space is that premium data expires quickly. A quote from January is often inaccurate by April. Carriers adjust filing schedules unpredictably, and new plan options appear each year. The underlying principles of rating methods and enrollment windows stay constant, but the dollar amounts shift. Budget for that variability rather than treating any single number as fixed.