What the Minnesota Property And Casualty Insurance Exam Actually Looks Like
The Minnesota Property And Casualty Insurance Exam is your gateway to becoming licensed as an insurance producer in the state. It covers both property and casualty lines of authority, which means you get tested on a wider range of topics than you would for a single-line exam. The exam is administered by Pearson VUE on behalf of the Minnesota Department of Commerce, and it is computer-based. You walk into a testing center, sit at a station, and answer between 150 and 175 multiple-choice questions depending on the current test blueprint. You have two hours to finish it. You need a score of 75 percent or higher to pass. The exam splits into two main domains. The first domain is property coverage, which includes things like homeowners policies, dwelling forms, commercial property forms, and the various endorsements that modify standard coverage. The second domain is casualty coverage, which covers general liability, commercial general liability, auto liability, workers compensation, and umbrella/excess liability. There is also a smaller section dedicated to Minnesota-specific insurance law and regulations, plus some ethical and procedural content that applies to all producers. What most people do not realize is that the questions are not just testing whether you know a definition. They are testing whether you can apply that definition in a scenario. A typical question will describe a situation involving a policyholder's claim and ask you to determine which coverage applies, which exclusion triggers, or what the correct procedure is under Minnesota law. You have to read carefully. The answer choices are designed to look plausible if you skim.
I spent years helping people prepare for this exam and the number one mistake I see is candidates studying flashcards and definitions without doing enough applied questions. Memorizing that ISO means "Insurance Services Office" is not the same as knowing when an ISO form gets adopted by a state and what that adoption looks like in practice. You need to be comfortable with both.
How to Actually Prepare Without Wasting Months
The practical approach is to use a combination of a structured study guide, a question bank, and at least a couple of practice exams. The study guide gives you the framework. The question bank trains you for the way questions are phrased. The practice exams simulate the timing and pressure of the real thing. Do not take practice exams until you feel reasonably solid on the material, or you are just reinforcing gaps instead of finding them. Here is the specific workflow I recommend. Spend about two to three weeks studying if you are working full-time. That means roughly one to two hours a day. Start with property, then move to casualty. Minnesota-specific law is a smaller portion, maybe ten to fifteen percent of the exam, so do not neglect it but do not over-index on it either. After you complete the first pass of your study guide, start the question bank. Aim for 500 to 800 practice questions total. Review every answer you miss thoroughly. When you hit a wrong answer, do not just move on and note the right answer. Figure out why the wrong answer was wrong, because that is where the trap is. The exam writers put wrong answers there for a reason. Once you have done a solid run through the material, take two full-length timed practice exams back to back. If you are scoring 80 percent or higher consistently on those, you are likely ready. If you are scoring below 70 percent, you need more time before booking the actual exam. There is no benefit in burning a fee and sitting down stressed because you were premature.
Get the Full Details
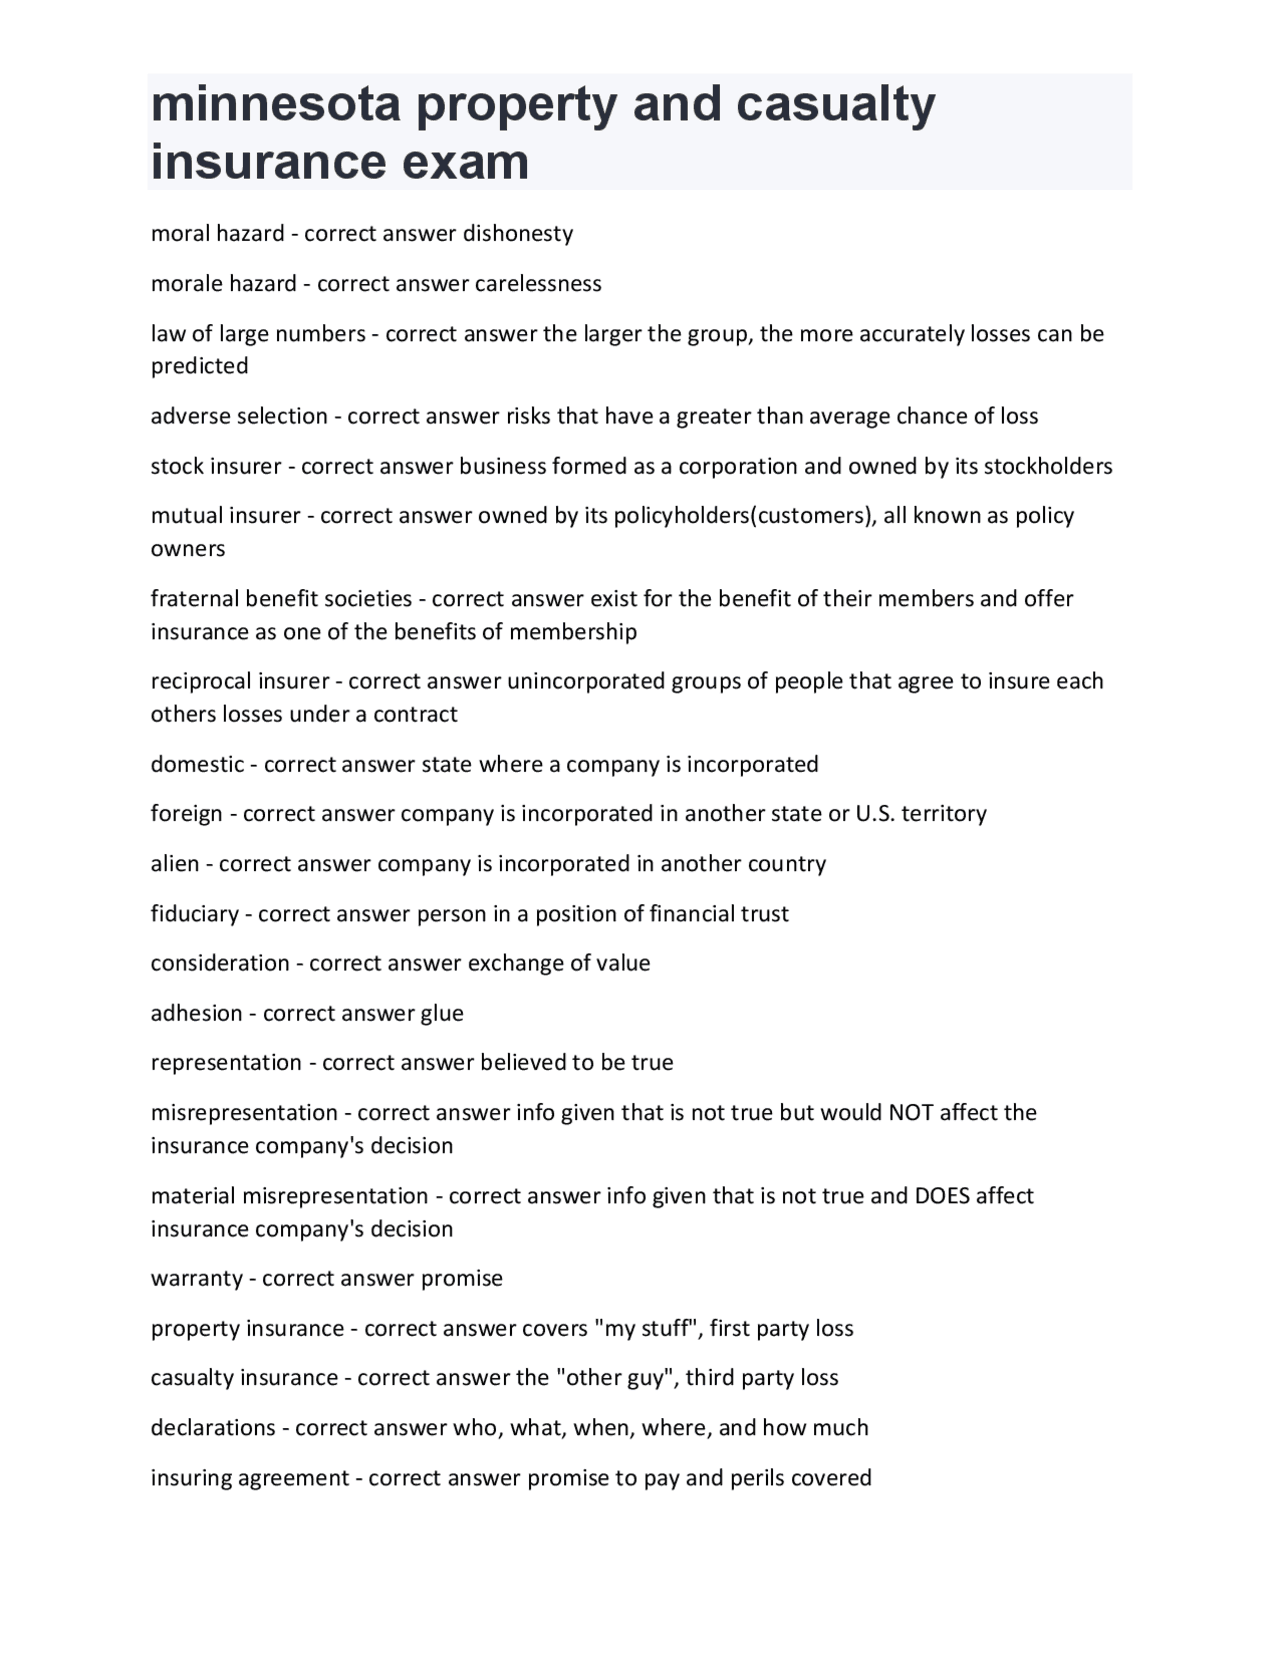
Common Pitfalls and What Most Guides Skip
One thing that does not get enough attention is the wording around "best answer" questions. In many cases, two of the four choices are technically correct statements, but only one is the best answer for the scenario presented. This is especially common in the casualty section when questions involve concurrent causes of loss or layered coverage. You have to pick the single most accurate answer, not the one that sounds right from memory. Another pitfall is the Minnesota insurance code sections. The department publishes the relevant statutes and administrative rules online, and they do appear on the exam. But they do not appear as straight recall questions. They appear as situational questions where you need to know the correct procedure, filing requirement, or timeline. For example, knowing that a insurer must respond to a completed proof of loss within thirty days under Minnesota law is useful, but you also need to know what happens if they do not comply and what the policyholder's remedies are. I remember one candidate who was doing well on practice tests but kept missing questions related to the Minnesota insurance fraud provisions. He had not read the actual statute language and was relying on generic ethics training that did not match the state-specific penalties and reporting requirements. He ended up going back to the Commerce website, pulling the relevant sections, and doing a focused review. He passed on his next attempt. That told me exactly what the exam is weighing more heavily than anything a prep book will say.
What Happens Before and After the Exam
Before you sit for the Minnesota Property And Casualty Insurance Exam, you need to complete the background check and fingerprinting through the Bureau of Criminal Apprehension. You also need to submit your application through the Minnesota Department of Commerce's portal and pay the exam fee. The background check can take a few weeks, so do not wait until the last minute. If you are already pre-licensed through another state, you may be eligible for a reciprocity path, but Minnesota has its own specific requirements and you still need to pass the state exam unless you meet exemption criteria. After you pass, your license goes through an approval process. It typically takes a couple of weeks for the Commerce to process the result and issue your license, assuming there are no issues with your background check. You can verify your license status online once it is active. If you mess up the application or forget a required document, you will get a delay notification and you will be back to waiting.
Bottom Line
The exam is manageable if you treat it like a real commitment rather than something to rush through. Two to three weeks of consistent study, heavy focus on applied questions, and at least two full practice exams under timed conditions will put most people in a passing position. The ones who struggle are usually the ones who skip the practice questions or ignore the Minnesota-specific sections because they assume general insurance knowledge is enough. It is not. The state law component is small but decisive, and the applied scenario questions require practice to develop the right reading habits. Book the exam only when your practice scores are consistently solid, not when you feel ready. Those are different feelings.