How to Actually Get Your Missouri Insurance License
The path to getting licensed in Missouri isn't particularly complicated, but it's easy to botch if you don't know where the traps are. I've helped people through this process more times than I can count, and the same mistakes keep showing up every single cycle. You need to complete a pre-licensing education course, pass the state exam, and then go through the appointment process with an insurer. The whole thing usually takes 4 to 8 weeks if you don't stall out on the exam attempt. I've seen people drag it to 6 months because they failed the test twice and didn't know they had to wait 30 days between attempts. The pre-licensing requirement depends on which line of authority you're pursuing. Life and health requires 40 clock hours. Property and casualty is the same. If you want both combined, some providers offer an 80-hour bundle that covers everything. I recommend the bundle even if you only plan to write one line initially, because adding the second line later just means another course and another exam fee.
Here's something most study guides won't tell you: the exam questions are far more procedural than conceptual. They test whether you know what to do in a specific compliance scenario, not whether you understand the theory behind insurance. I remember working with a producer who had memorized every formula and definition but froze on questions about prompt payment of claims timelines. She'd never actually processed a claim in her life, so the regulatory timeframes meant nothing to her. I told her to stop studying from the textbook and start looking at actual Missouri insurance statutes. It cut her confusion down significantly.
The Exam Itself
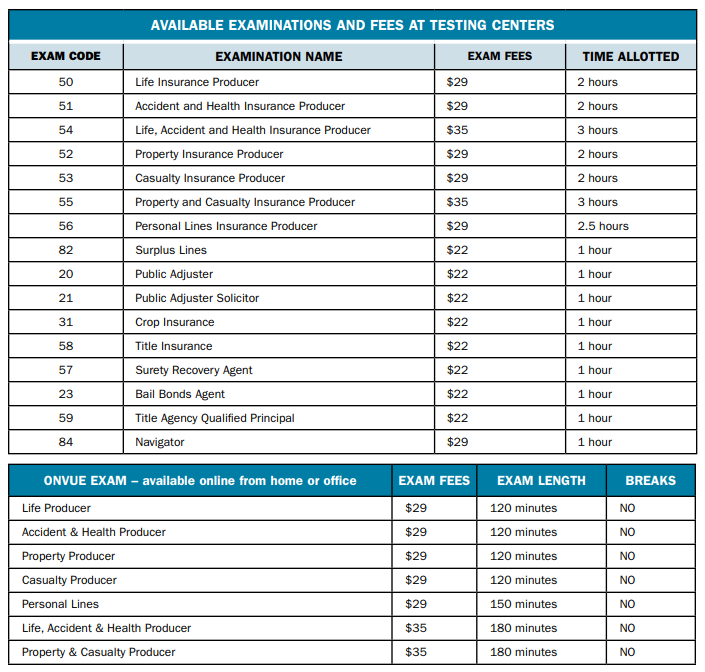
administered by Pearson VUE. You schedule through their website, show up with two forms of ID, and take a computer-based test. Life and health has 100 scored questions plus 10 pretest items you won't know about. The passing score is 63 percent. That number surprises people because it sounds low, but the pretest questions inflate the denominator without helping your score, so you actually need to get roughly 70 percent of the scored questions right to hit 63 overall. Property and casualty follows the same format with 100 scored questions and the same passing threshold. Adjustments for disability income or Medicare lines add separate sub-exams that you take at the same sitting. One edge case I ran into recently involved someone who took the exam at a mobile testing location instead of a fixed Pearson VUE center. The proctor there misread the candidate's second ID as insufficient and initially refused to let them in. This happened because the second ID was a credit card with a photo, which some proctors incorrectly reject. The candidate was on their last allowed attempt and nearly missed the window. What worked was calling Pearson VUE's test-taker support line directly while still at the center. They escalated it to the state's licensing coordinator, who confirmed the ID was valid under Missouri rules. The proctor eventually relented, but it cost the candidate forty-five minutes of stress. If you ever face this, don't negotiate with the proctor. Call the support line immediately and have your appointment confirmation number ready.
Get the Full Details
Study Strategy That Actually Works
Most people study wrong. They read the textbook cover to cover and assume retention will follow. It doesn't. The exam rewards pattern recognition, not comprehensive knowledge. You need to do practice questions until you can identify the trap answers without reading the full question. Here's a specific technique: take a practice exam, grade it, and then spend twenty minutes reviewing only the questions you got wrong. Don't review the ones you got right. Your brain will reinforce the gaps, and that's what matters. Repeat this cycle three or four times with different question banks and you'll cover the same material faster than anyone who reads passively. The biggest pitfall I see is people relying on a single study resource. The official pre-licensing course materials don't always align perfectly with the exam's question style. I've noticed that some questions on the actual exam reference Missouri-specific statutes that the national textbooks gloss over. You should supplement with the Missouri Department of Insurance' own study guides and at least one third-party question bank. ProPlus Exam Prep and preplanned.com both have solid options, though neither is perfect. The real answer is using two or three sources and comparing how they explain the same concept.
After You Pass
Passing the exam is only half the work. You need to apply for your license through the Missouri Department of Insurance, Financial Institutions, and Professional Registration. This is done online via the Missouri Electronic Systems for Online Licensing. You'll need your Social Security number, proof of pre-licensing completion, and a sponsoring insurer willing to appoint you. Here's where people get stuck: the appointment process. An insurer has to appoint you before your license becomes active. Some smaller carriers move slowly on this. I've seen appointments sit in queue for three to four weeks while the applicant assumes they're already licensed and starts contacting prospects. They're not. The license shows as pending until the appointment posts. Check your status in the online system regularly. Don't assume silence means progress. There's also the background check component. Missouri runs a fingerprint-based criminal history check. If you have any prior convictions, even minor ones from decades ago, disclose them upfront. Hiding them is worse than the underlying issue. I've watched people get their licenses denied because they omitted a traffic-related misdemeanor from twenty years back, and the fingerprint match triggered a review that exposed the omission. The original offense wouldn't have been a problem on its own.
Costs and Timelines
Expect to spend roughly 400 to 800 dollars total depending on your choices. Pre-licensing courses run 150 to 400 dollars. The exam fee is about 55 dollars per line. The state application fee is around 100 dollars. Appointment processing through an insurer is typically free. Fingerprinting adds another 30 to 50 dollars if your carrier doesn't cover it. Turnaround time from enrollment to active license is usually 4 to 10 weeks. Delays come from three places: slow course completion, failing the exam and waiting out the 30-day retake window, and delayed appointments. If you're in a rush, pick a course with a 30-day guarantee and a refund policy if you don't finish in time. Not all providers offer this, so check before you pay.

When This Path Won't Work For You
If you have an active felony conviction or a license suspension in another state, Missouri will likely deny your application regardless of exam performance. The department reviews criminal history and prior disciplinary action during the background check phase. There's no appeal process that overrides a statutory disqualification. In those cases, the only route is waiting out the eligibility period or consulting a licensing attorney before investing time and money. Similarly, if you're trying to get licensed as an adjuster rather than an agent, the requirements shift significantly. Adjuster licensing in Missouri doesn't always require pre-licensing education, but it does require passing a different exam and meeting experience thresholds that vary by employer. The path I've described above applies to producing lines only.