What the Mn Life Insurance Practice Exam Actually Covers
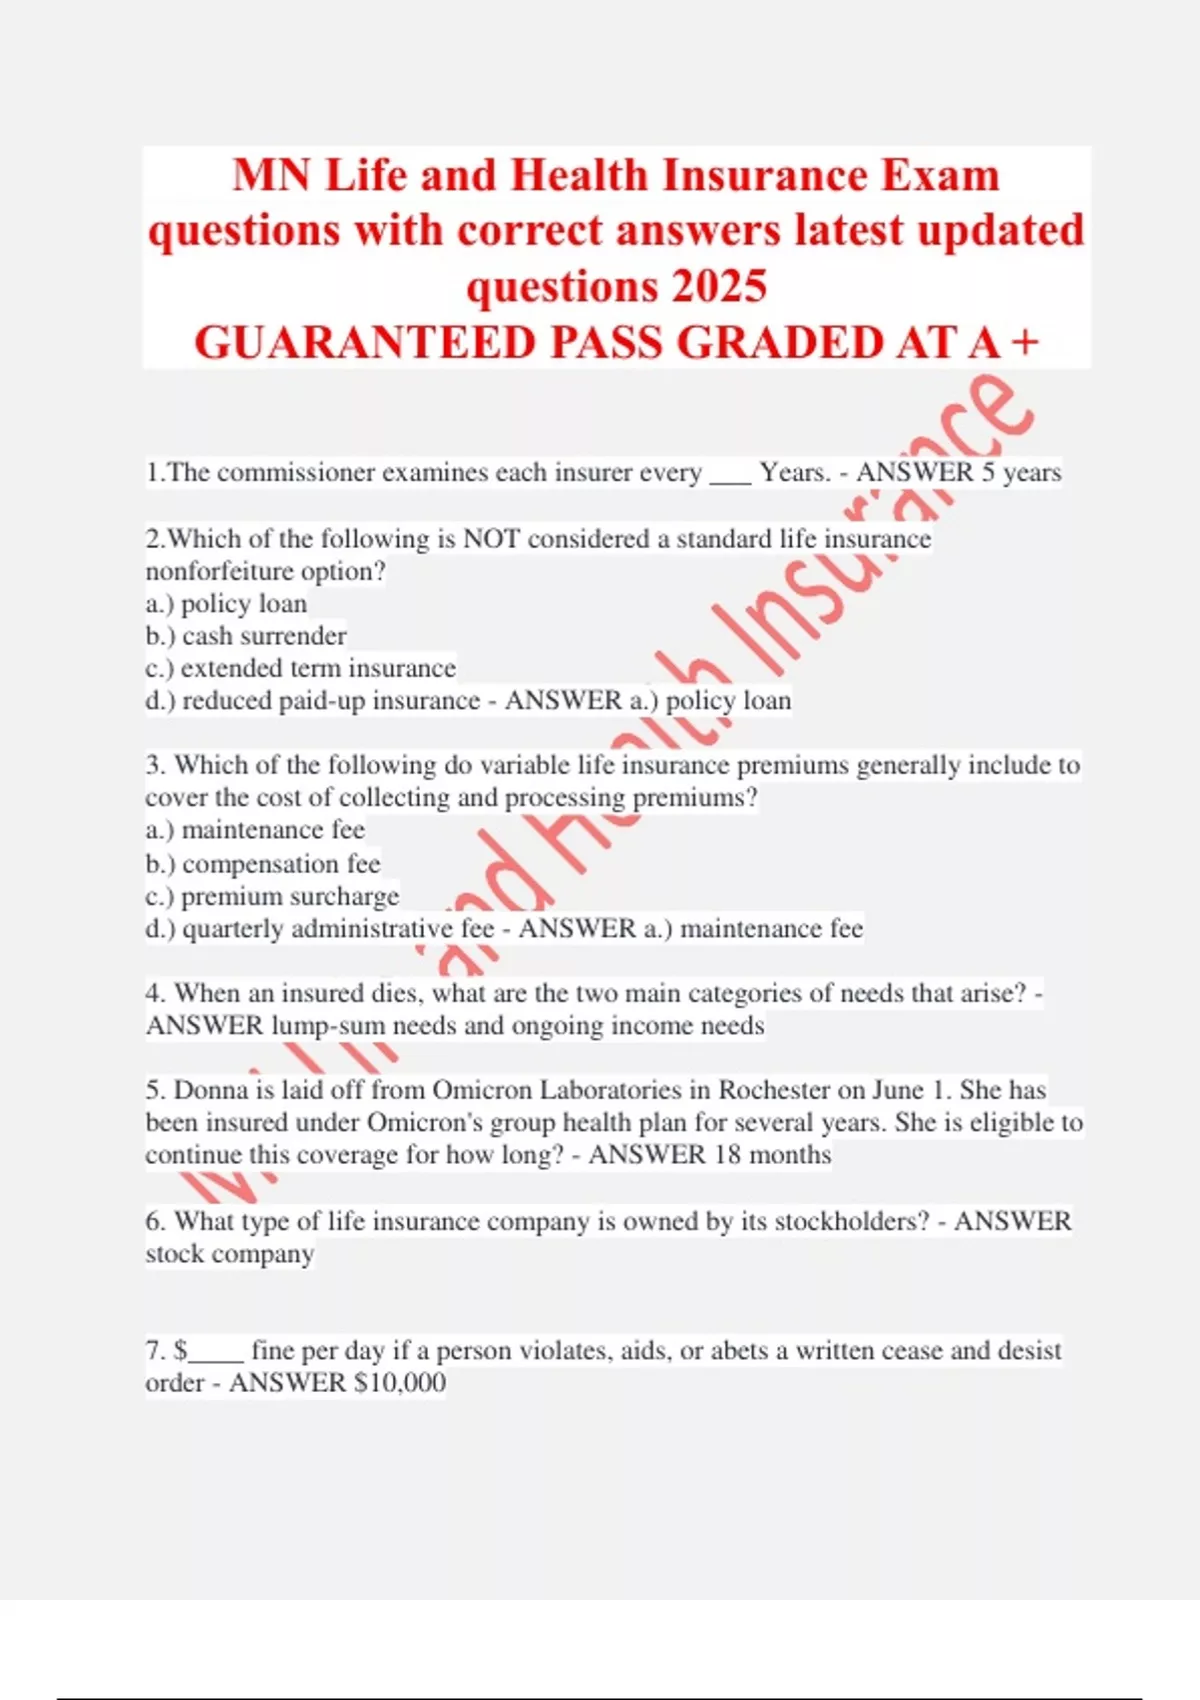
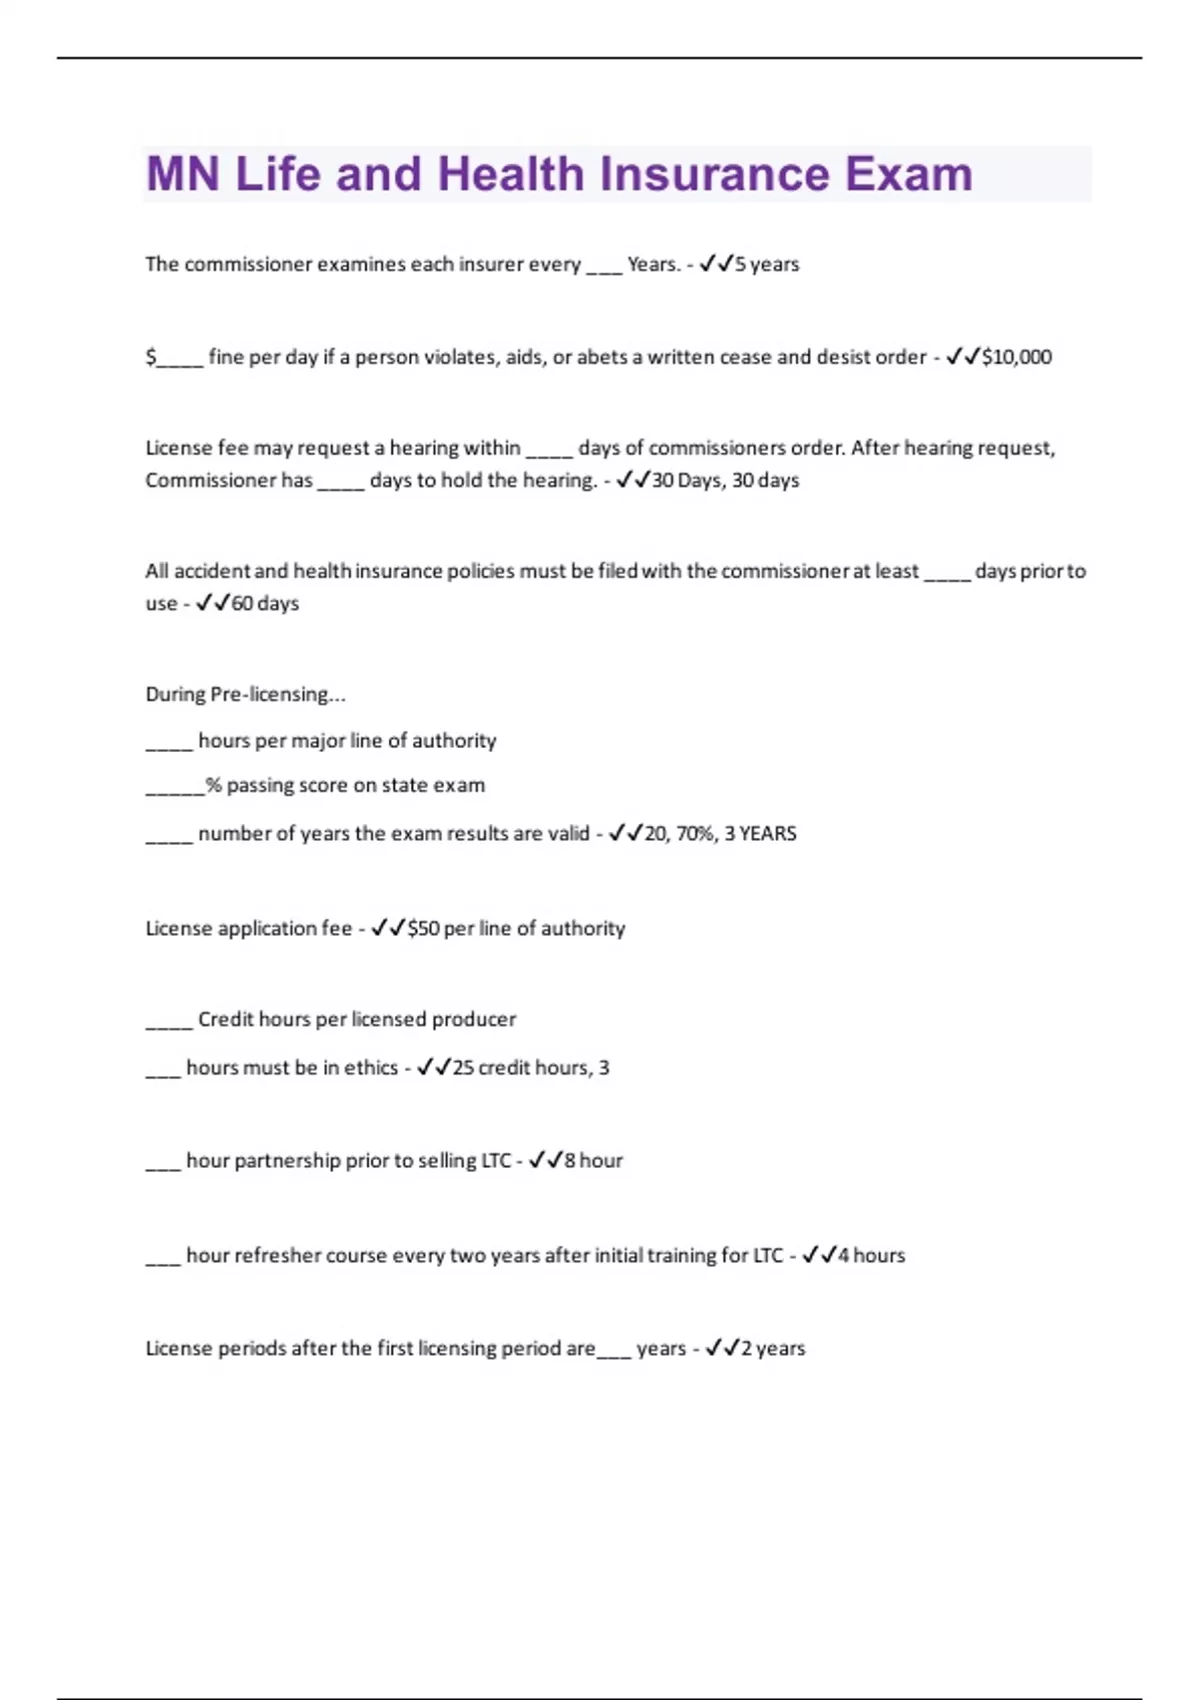
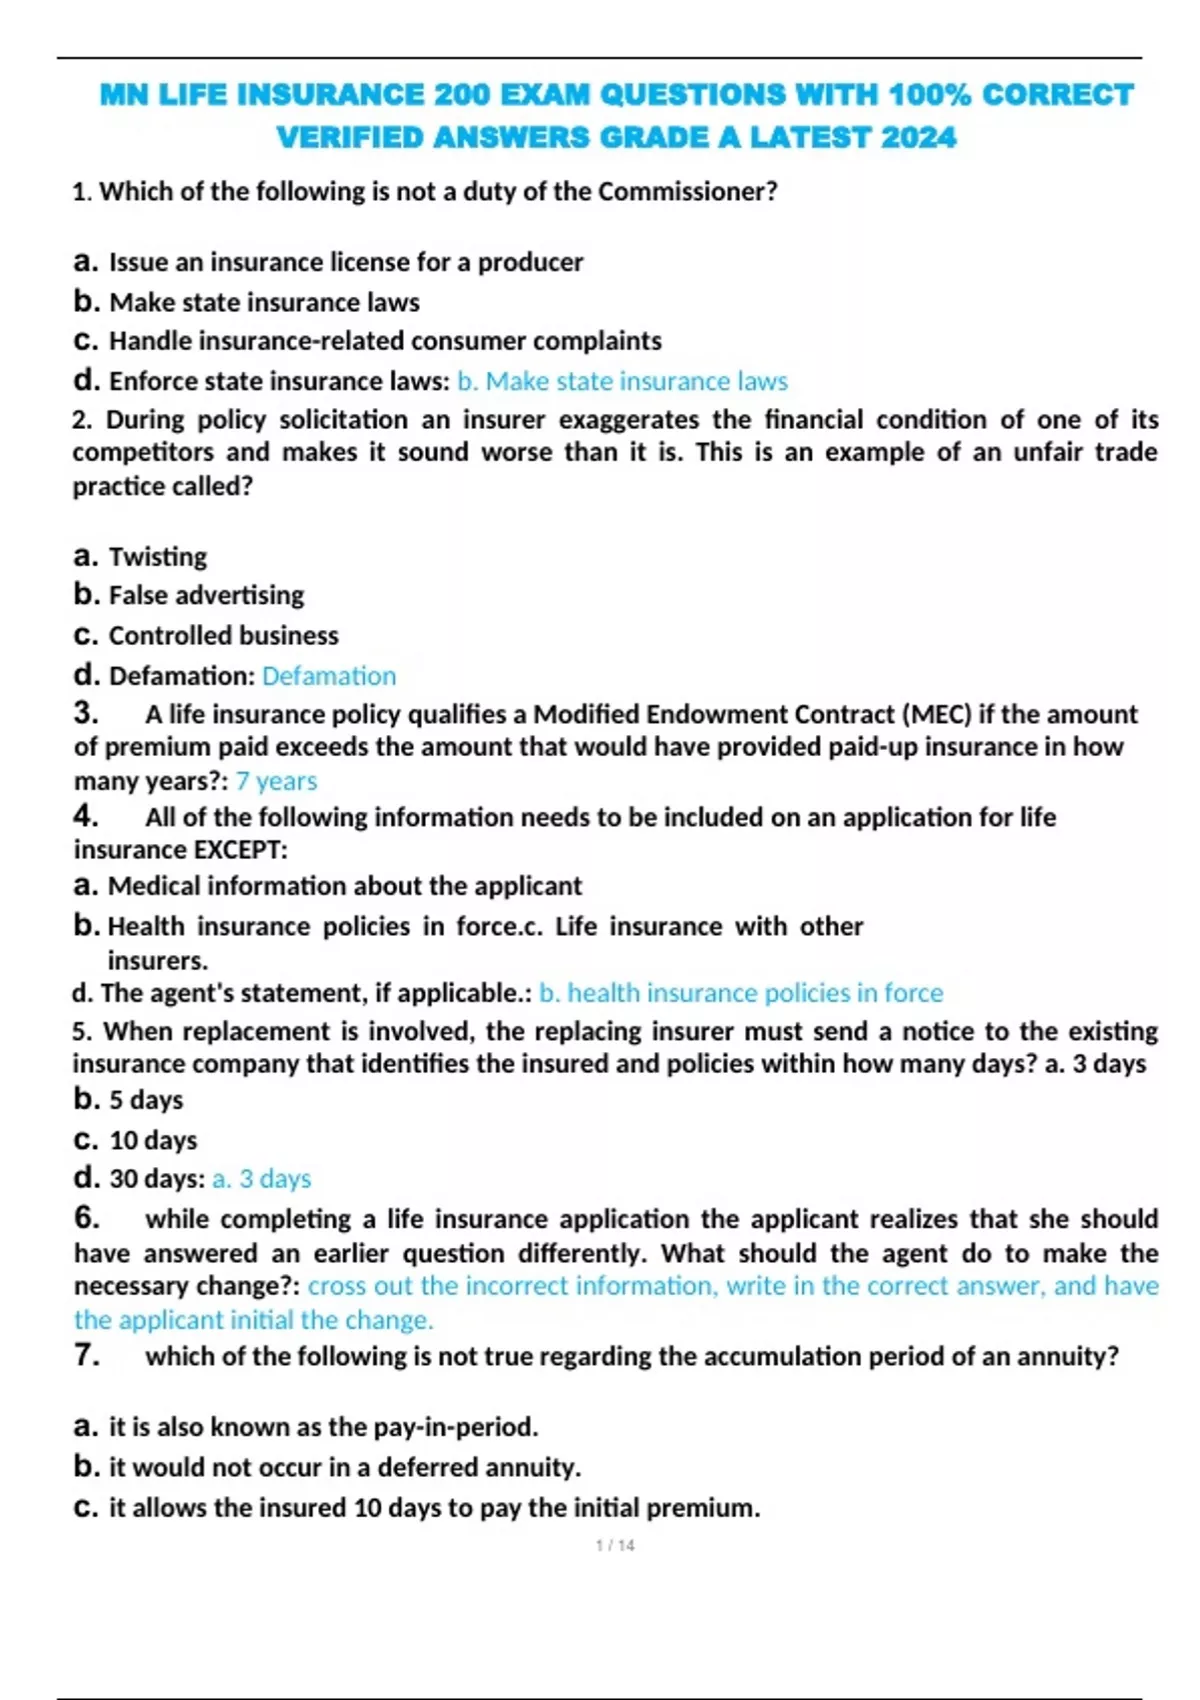
The Minnesota life insurance licensing exam tests your knowledge of state-specific insurance laws, general insurance principles, and the fundamentals of life insurance products. It is administered by Pearson VUE on behalf of the Minnesota Department of Commerce. You need to pass it before you can get appointed by an insurer. The exam is multiple choice, typically 60 to 75 questions, and you get about 75 minutes to finish it. Passing score is set by the state and has historically been around 75 percent, but you should verify the current threshold on the Department of Commerce website before you show up. Practice exams are the most reliable way to gauge whether you are actually ready. Most people study material passively and walk into the testing center confident they know the content, then struggle with how questions are phrased. The Minnesota exam does not just ask for definitions. It asks you to apply rules to scenarios. A practice test that mirrors the actual exam format is essential for building that skill. I have seen candidates spend weeks reading textbooks and still fail because they never practiced under timed conditions. The real problem is not that the content is hard. It is that the questions are wordy and deliberately tricky. They include distractor answers that sound correct if you skim. I learned this the hard way during my own prep. I took a practice test and scored 82 percent, which I assumed was solid. Then I tried a second one and dropped to 67 percent because the first test had been too easy and gave me a false sense of readiness. The workaround was simple: I started using only practice exams that explicitly said they were modeled after the Minnesota state portion, and I tracked my scores across at least five different sets. Once I was consistently scoring above 80 percent on those, I scheduled the real exam. I passed on the first attempt.
Here is a practical guide to actually getting value from practice exams instead of just grinding through them.
How to Use Practice Exams Effectively
Start by taking one full-length practice test cold, without any notes or study material. This gives you a baseline. You will likely score poorly and that is fine. The point is to see exactly where your gaps are before you start studying. Pay attention to which topics you get wrong most often. For Minnesota specifically, the state law section tends to be the weakest area for most candidates because it is highly specific and not intuitive. After the baseline test, study the topics you missed. Do not try to learn everything at once. Focus on the areas that cost you the most points. Then take another full practice test. Repeat this cycle until your scores stabilize above 80 percent across multiple attempts. Random high scores mean nothing. Consistency is what matters. When you review incorrect answers, do not just move on. Write down why the correct answer is right and why each wrong answer is wrong. The exam writers deliberately make every option plausible. Understanding the reasoning behind each distractor is what separates people who pass on the first try from people who do not.
Get the Full Details
One specific issue I ran into involved annuity questions. The Minnesota exam includes a section on annuities, and several practice tests I used had outdated illustrations that did not match the current tax treatment of annuity distributions under the IRS rules as they apply in Minnesota. This caused confusion because the practice test answer key seemed internally inconsistent. The workaround was to cross-reference any annuity question I got wrong with the actual Minnesota insurance code and the relevant IRS publication, rather than trusting the practice test explanation. It took longer, but it prevented me from memorizing incorrect logic.
Common Pitfalls to Avoid
Most candidates make the same mistakes. They study content without understanding how the state applies it. Minnesota has specific requirements around solicitation, policy delivery, and replacement procedures that differ from national norms. If you are preparing using a generic life insurance exam prep course, you may miss these state-specific nuances. Always supplement your study with materials that are explicitly tailored to Minnesota. Another trap is relying on memory for numbers. The exam tests specific numerical thresholds, like the free look period, which in Minnesota is 10 days. You will encounter questions that require exact figures. Flashcards or a cheat sheet for state-specific numbers is worth the effort. Timing is also a bigger factor than people expect. Some questions are straightforward. Others require reading three long paragraphs before you can identify what is actually being asked. I have timed myself on practice tests and found that spending more than 90 seconds on any single question almost guarantees you will not finish. If a question feels unclear, mark it, move on, and come back to it later. Most people do not allocate enough time for this strategy.
Where to Find Reliable Practice Exams
The most trustworthy sources are prep courses that are specifically designed for the Minnesota state exam. Organizations like preplify, Damion Lattimore, or state-specific prelicensing schools often include practice tests that align closely with the actual exam. The preplify Mn Life Insurance Practice Exam platform, for example, provides full-length practice tests that are frequently updated and reflect current Minnesota regulations. You can find it through their official website. Free practice questions exist online, but they are uneven in quality. Some are accurate. Many are outdated or written by people who do not fully understand the material. I recommend using free resources only as supplementary material, not as your primary source. If a free practice test explains an answer incorrectly, it will actively harm your preparation. Also check the Minnesota Department of Commerce candidate handbook. It outlines the exam structure, content distribution, and any recent changes to the testing requirements. This is the authoritative source for what you will actually see on exam day.
What to Do on Exam Day
Bring two forms of ID. One must be a government-issued photo ID. The other can be a secondary form like a credit card or another piece of mail with your name on it. Arrive 15 minutes early. The testing center will check your identity and get you settled. Once the exam starts, the clock is running and there is no pause button. Use the process of elimination aggressively. Even if you are unsure, cross out the clearly wrong answers first. That usually leaves you with two options, and one of them is often a half-truth or an answer that is correct in a different context. Read the question stem carefully. Watch for words like EXCEPT, NOT, or LEAST. Those change the entire meaning of what is being asked. If you finish early, do not rush to submit. Go back and review the questions you marked. Most of those will become clearer on a second read. I have seen candidates fail by spending too long on hard questions early in the exam and running out of time on easier ones at the end.
The exam itself is not designed to trick you unfairly. It is designed to ensure that people selling life insurance in Minnesota actually understand the rules they are subject to. Your goal is to demonstrate that you know the material well enough to apply it. Practice exams are the best tool for that. Use them correctly and you will be in good shape.